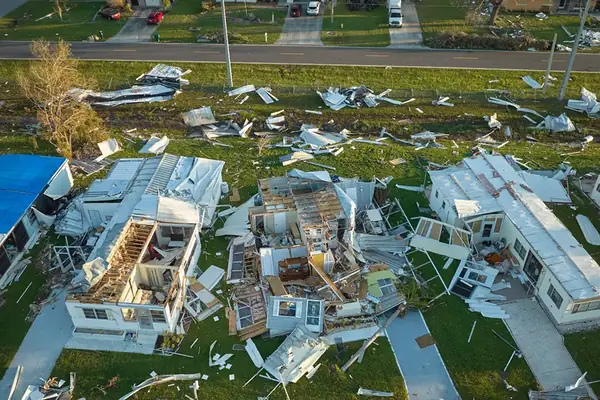
In the Golden Triangle, a hurricane claim is rarely the building's first. Hurricanes Rita (2005), Ike (2008), Harvey (2017) and Laura (2020) all affected Beaumont, Port Arthur and Orange, and many roofs, walls and slabs here carry repairs from earlier storms. That history is what carriers use to reduce new claims. Our job is to show what the latest storm did, price it correctly in Xactimate, and hold the insurer to its policy and its Texas deadlines.
We work out of Belton and travel to Jefferson, Orange and Hardin counties to inspect homes and commercial property.
Old repairs, new damage
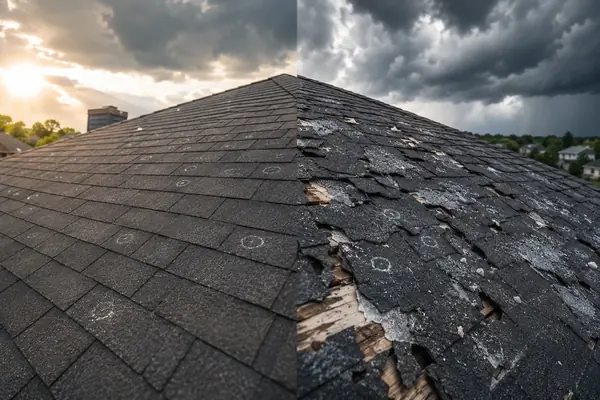
The most common argument we see on Golden Triangle claims is "pre-existing." An adjuster finds patched shingles, a replaced section of metal panel, or old water staining, and writes the whole area off as prior damage. Sometimes that's right. Often the new storm damaged repaired and unrepaired areas alike.
What helps:
- Invoices, permits and photos from repairs after earlier storms
- Prior claim numbers and the carrier's closing letters on those claims
- Recent photos of the property (real estate listings, inspection reports, phone pictures) showing its condition before this storm
- Fresh damage evidence: clean breaks, bright metal at fastener holes, torn rather than weathered edges
If you never fixed damage from a previous paid claim, tell us. The carrier can deduct what it already paid for, and it's better to address that up front than have it surface during a re-inspection.
Which policy covers the wind
Jefferson County is one of the 14 first-tier coastal counties where the Texas Windstorm Insurance Association writes wind and hail coverage, so many homes and businesses in Beaumont, Port Arthur, Nederland and Port Neches have a TWIA policy alongside a homeowners or commercial policy that excludes wind. Orange and Hardin counties are not TWIA counties, so wind coverage there comes from private carriers.
to file a TWIA claim after the date of damage
for TWIA to generally accept or deny after it has what it asked for
for a private insurer to acknowledge and start investigating
written notice required before suing on a weather claim
The one-year TWIA filing deadline comes from Tex. Ins. Code §2210.573; private carriers follow the Chapter 542 prompt-payment rules and their own policy conditions. Flood is separate on either side: it needs an NFIP or private flood policy.
Commercial and industrial property
The Golden Triangle has a heavier mix of commercial and industrial property than most of Texas: warehouses and shops serving the refineries and ports, churches with large roof areas, strip retail, restaurants and hotels along the interstate. These claims have their own problems.
Roof systems
Metal panel and low-slope membrane roofs cover a lot of square footage, so small disagreements per square become large numbers. Metal roofs often carry a cosmetic-damage exclusion; the dispute is whether a panel's seams, fasteners or coatings were functionally damaged. Membrane roofs need core samples and seam inspection, not just a walk-over. Our guide to cosmetic vs. functional damage explains the line carriers draw.
Business income and extra expense
If your policy includes business income coverage, the claim isn't only the building. Keep records of closure dates, lost sales and the extra costs of operating elsewhere. Those figures need the same documentation as the physical damage.
Higher deductibles
Commercial wind deductibles in coastal counties are often a percentage of the insured value, which on a large building is a significant amount. An estimate that leaves out code-required items or equipment can fall below the deductible when the true loss doesn't.
See our pages for warehouse claims and church claims, or the broader commercial claims overview.
After a storm in Beaumont, Port Arthur or Orange
- Find all your policies. In Jefferson County, check whether you have a TWIA wind policy in addition to your homeowners or commercial policy, and whether you carry flood.
- Report to each carrier separately. TWIA, your property carrier and your flood carrier each need their own notice and will send their own adjuster.
- Document before cleanup crews arrive. Photograph the roof, every wall line where water stood, and equipment and inventory. For commercial property, record serial numbers and model plates.
- Protect the property. Tarp, board up and start drying. Keep invoices for every temporary repair.
- Gather your storm history. Pull together records from repairs after earlier hurricanes before the carrier asks for them.
The claim documentation checklist lists what to collect for each loss type.
When the estimate comes back low
We write our own Xactimate estimate from a full inspection, compare it line by line with the carrier's, and submit the difference with photos and measurements. If the dispute is about the amount of loss rather than whether it's covered, appraisal may be an option under your policy. We charge a percentage of the claim payment, capped at 10% by Texas law, and nothing upfront. Read more about our hurricane and windstorm claim work.
Free toolTexas claim deadline calculatorTurn your claim dates into the insurer's Chapter 542 deadlines to acknowledge, decide and pay.Communities covered from this page
Don't see your town? We serve every Texas county. Ask us about your property.
Frequently asked questions
Is Beaumont in the TWIA coverage area?
Yes. Jefferson County, which includes Beaumont, Port Arthur, Nederland and Port Neches, is a first-tier coastal county where TWIA writes wind and hail coverage. Orange and Hardin counties are not.
My roof was repaired after an earlier hurricane. Can the insurer deny new damage as pre-existing?
It can argue that, but it has to be supported. Repair invoices, earlier closing letters and photos of the roof before this storm are the best way to show the new damage is new.
Does a TWIA policy cover flooding?
No. TWIA covers wind and hail. Rising water needs an NFIP or private flood policy.
Do you handle claims on industrial and commercial buildings in the Golden Triangle?
Yes. We handle warehouses, shops, churches, retail, restaurants and hotels, as well as homes. See our commercial claims page.