After a hurricane in Texas, the question that decides your claim is not how bad the damage is but what caused each part of it. Wind damage and wind-driven rain through a storm-created opening are generally covered by your homeowners or windstorm policy, which may be TWIA if you are on the coast. Rising water and storm surge are flood, which a standard homeowners policy excludes and only an NFIP or private flood policy covers. One house can have all three, with a separate deductible for each.
Here is how the common types of hurricane damage sort out, how to document them so they land under the right policy, and what Hurricane Beryl showed Houston homeowners about the parts of a claim people forget.
The types of hurricane damage
Wind damage
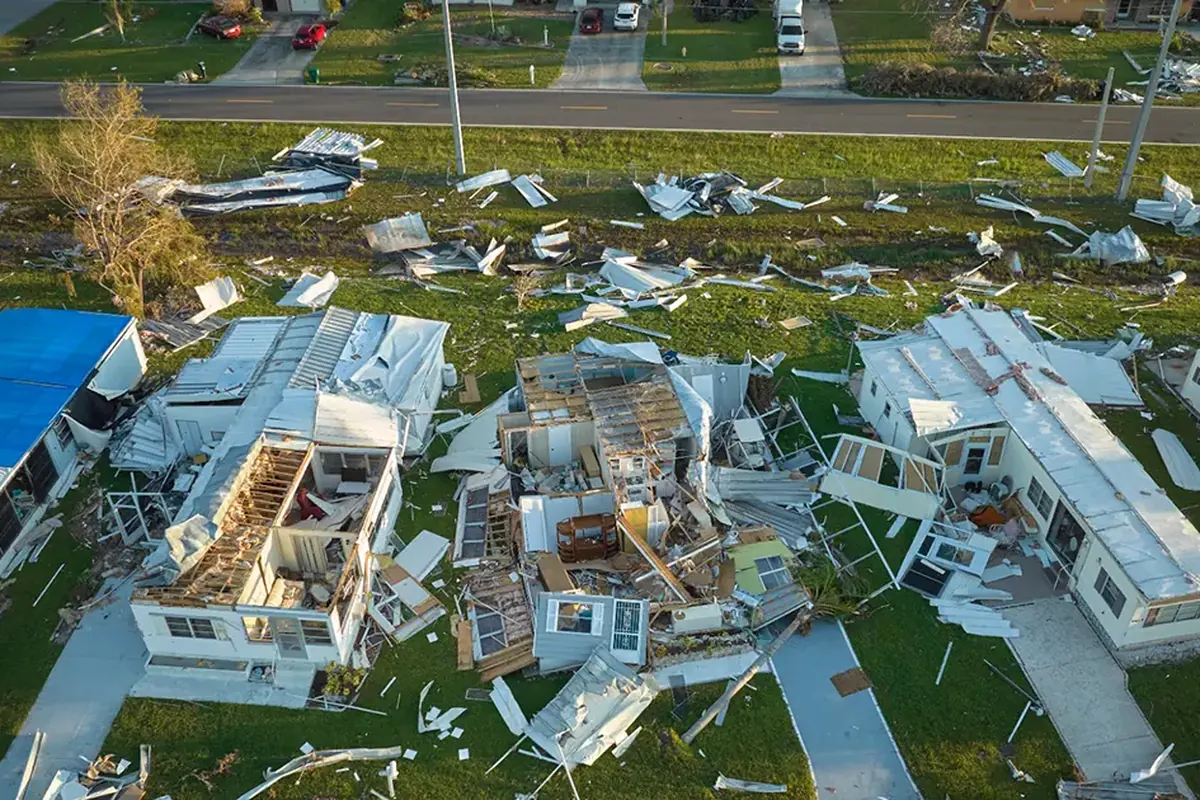
Missing or creased shingles, lifted ridge caps, torn flashing, damaged soffit and fascia, broken windows, bent gutters, blown-down fences and damaged siding. Wind damage is the core of most hurricane claims. Check the whole roof, not just the obvious missing tabs: shingles that were lifted and resealed can lose their bond without falling off.
Wind-driven rain
Water that enters through an opening the storm created, such as a missing section of roof, a broken window or a torn soffit, is usually treated as part of the wind loss. Rain that enters without a storm-created opening, for example through an old window seal, is a harder argument under many policy forms. That is why the first photos of the roof and openings matter so much.
Storm surge and flooding
Surge pushed inland by the storm and rainwater that rises from the ground are flood. Standard homeowners policies and TWIA exclude it. Hurricane Ike brought surge damage to Galveston, and Hurricane Harvey caused widespread rain flooding in Houston and along the Coastal Bend. If water came in at floor level and left a waterline, expect the insurer to look for a flood policy.
Falling trees and debris
A tree that falls on the house, garage or a covered structure is generally covered, including removing the tree from the structure. A tree that falls in the yard without hitting anything is often covered only for limited debris removal, if at all. Check your policy's trees, shrubs and debris removal provisions; these limits are usually small and specific.
Power outage losses
Spoiled food in the refrigerator and freezer is the most common outage loss. Some policies cover it, often with a small limit, and some only when the outage traces to a covered cause on your own property. Hotel stays while the house is without power are a separate question: Additional Living Expense typically applies when the home is unlivable because of covered damage, not because of a grid outage alone.
Mold
Wet drywall and insulation left in a closed, hot house can grow mold within days. Mold that follows covered wind-driven rain is treated very differently from mold that follows flood or long-term moisture, and many policies cap mold with a sublimit. Prompt drying is both your best defense against mold and your best evidence that you mitigated.
Which policy covers what
| Damage | Homeowners policy | TWIA (if you have it) | Flood policy (NFIP or private) |
|---|---|---|---|
| Roof, siding, windows from wind | Yes, unless the policy excludes wind | Yes | No |
| Rain through storm-created openings | Usually, if wind is covered | Usually | No |
| Storm surge and rising water | No | No | Yes |
| Tree on the house | Usually | If wind caused it | No |
| Spoiled food from outage | Depends on policy, often limited | Depends on policy | No |
| Mold | Often sublimited | Depends on cause | Depends on cause and policy |
On the coast, many homeowners policies exclude wind and hail, and that coverage comes from a separate TWIA policy. Inland, including most of Houston, wind is normally on the homeowners policy. Your declarations page will show which you have.
Separate deductibles
Hurricane claims often involve more than one deductible:
- Wind and hail or named storm deductible. In Texas this is often a percentage of your dwelling coverage, commonly 1–2%, especially in coastal counties. On a large home that can be a substantial amount, and it is calculated from your Coverage A limit, not from the damage.
- Flood deductible. A flood policy has its own deductible, applied separately.
- All other perils deductible. A fixed-dollar deductible may apply to non-wind parts of the loss, depending on the policy.
If both wind and flood damaged the home, you may pay two deductibles. Use the claim settlement calculator to see how a percentage deductible and depreciation change your payment.
How to document hurricane damage
The goal is to show the cause of each piece of damage, not just that it exists.
- Photograph the roof and every exterior elevation before tarping, plus close-ups of each opening
- Photograph waterlines inside and out, with a tape measure for height; this separates flood from wind-driven rain
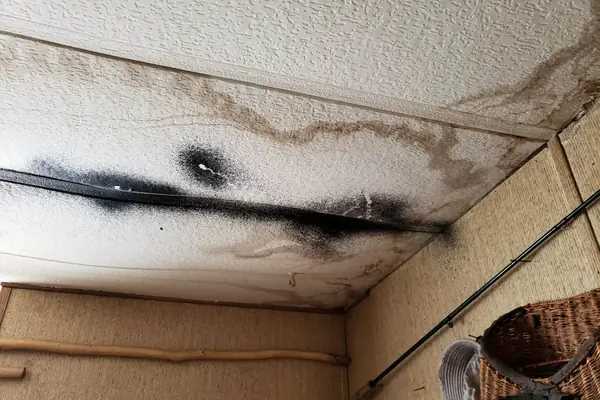
- Photograph ceiling stains and wet insulation that sit below roof damage
- Photograph fallen trees where they landed, before removal, with the point of impact
- Note the date and time the power went out and came back; keep any utility notices
- List spoiled food before throwing it out, with photos of the open refrigerator and freezer
- Keep receipts for tarps, chainsaw work, generators, fuel, drying equipment and hotel stays
- Look up the storm reports for your address with our storm report lookup
File with each insurer that may be involved, and report each claim separately. If you have TWIA, remember that claims must be filed within one year of the date of damage. For private homeowners policies, check your own policy's duties after loss and suit conditions for the deadlines that apply.
Lessons from Hurricane Beryl
Hurricane Beryl came ashore in July 2024 and pushed damaging wind across the Houston area, followed by widespread power outages that lasted days for many households in summer heat. The claims that followed taught some practical lessons.
- Wind damage was easy to underestimate. Many roofs looked intact from the ground but had lifted shingles, damaged ridge caps or torn flashing. A roof-level inspection found damage a drive-by did not.
- Interior damage showed up late. Ceiling stains and attic moisture from wind-driven rain often appeared days later, after the power came back and people looked closely. Reopen or supplement the claim when you find new damage.
- Outage losses were missed entirely. Owners threw out spoiled food without photos or a list. Whether or not your policy pays for it, document it first.
- Heat and no power meant mold. Wet materials in houses without air conditioning grew mold fast. Owners who documented their drying efforts were in a better position when mold came up.
- Flood vs. wind disputes followed heavy rain. When water entered, the cause decided coverage. Photos of the opening, the roof and the absence of a ground-level waterline made the difference.
- Adjusters were stretched. After a declared catastrophe, the Chapter 542 deadlines are extended by 15 days, and first contact often came from out-of-state independent adjusters. See how long an adjuster has to contact you.
When to get help
Hurricane claims are where cause disputes, stacked deductibles and multiple insurers all meet. If you have a denied wind-driven rain claim, an estimate that skips half the roof, or both a flood and a wind claim on the same house, our hurricane and windstorm claims service covers how we document and negotiate those losses. For water inside the house, see dealing with the adjuster after water damage.
Frequently asked questions
Does homeowners insurance cover hurricane damage in Texas?
It usually covers wind damage and rain that enters through storm-created openings, unless your policy excludes wind (common on the coast, where TWIA provides it). It does not cover flood or storm surge.
Is storm surge covered by TWIA?
No. Storm surge is flood. It requires an NFIP or private flood policy.
What is a hurricane deductible in Texas?
Many Texas policies use a wind and hail or named storm deductible set as a percentage of dwelling coverage, often 1–2%. A flood policy has its own separate deductible.
Is food spoiled in a hurricane power outage covered?
Sometimes, often with a small limit, and some policies only cover it when the outage traces to a covered cause on your property. Photograph and list the food before discarding it.
How long do I have to file a hurricane claim with TWIA?
Within one year of the date of damage. The commissioner may extend that by up to 180 days for good cause.
Joseph inspects, documents and negotiates residential and commercial property claims across Texas, working only for policyholders.