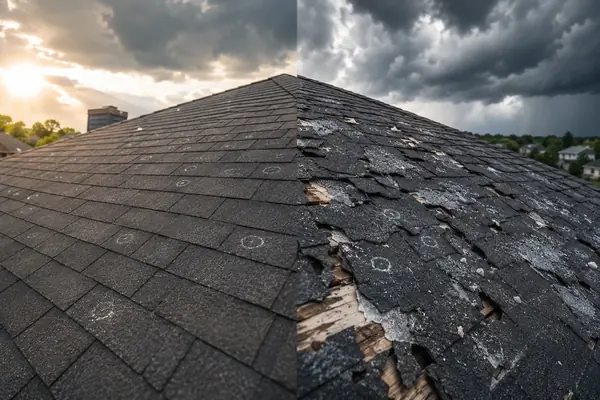
On the South Plains, spring hail and wind are the main source of property claims, and how the claim goes depends on who owns the property and how it's insured. A homeowner in Wolfforth, a landlord with three houses near Texas Tech, and a family farming outside Levelland may all be hit by the same storm and end up with very different claims. We review each claim for free, inspect in person, and write an Xactimate estimate that matches the property and the policy.
Our office is in Belton. We travel to Lubbock and the surrounding towns to inspect property.
Spring on the South Plains
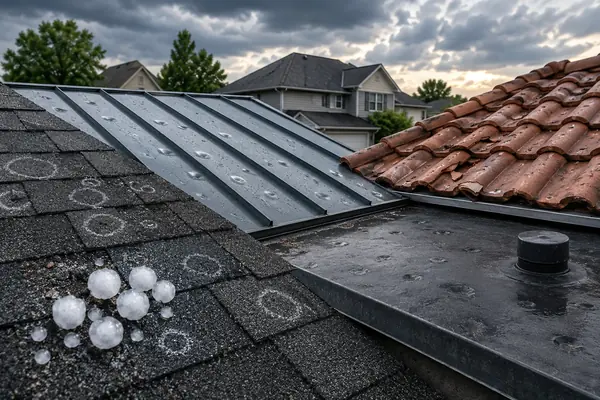
The flat, open country around Lubbock gives spring thunderstorms room to build and nothing to slow their wind. A strong storm can drop hail across a wide swath and bring straight-line wind behind it. The damage list after one of these storms runs long: shingles, ridge caps, vents, gutters, siding, window glass and screens, AC condenser fins, fences, carports, and anything metal left outside. For a closer look at what hail does to each roof material, see how to identify hail damage by roof type.
If you own your home
For most homeowners, the claim turns on the roof, and two policy terms decide how much of it you are paid:
- The wind and hail deductible. It's often a percentage of your dwelling coverage, 1% or 2%, rather than a flat amount. Find it on the declarations page.
- How the roof is paid. Some policies pay roofs at replacement cost; others use an actual cash value schedule or endorsement that depreciates the roof by age. On an older roof, an ACV schedule can cut the payment sharply. Read the endorsements before you compare estimates.
Don't stop at the roof. Siding, windows and the AC unit are often damaged by the same storm and left off a first estimate. Our roof and hail damage claims service goes through the full exterior.
If you rent property near Texas Tech
A lot of Lubbock's rental housing sits near the Texas Tech campus. Landlord claims differ from homeowner claims in a few practical ways:
- Rentals are often insured on a dwelling policy, and some dwelling forms pay roofs at actual cash value or cover fewer causes of loss.
- Lost rent is covered only if the policy includes fair rental value or loss of rents coverage.
- Tenants' furniture, electronics and clothing are covered by their renters policies, not yours.
- Student leases turn over on a schedule. If a unit needs repairs before move-in, document the timeline; it supports a lost-rent claim if you have that coverage.
Each property is usually its own claim with its own deductible, even when one storm hits several houses.
If you farm or own acreage
Agricultural property on the South Plains is often insured on a farm and ranch policy rather than a homeowners policy, or on a homeowners policy with farm structures scheduled separately. How a barn or shop is listed decides its limit and how it's valued. Before the adjuster arrives, find:
- Which policy covers each structure, and the limit for each
- Whether the structures are valued at replacement cost or actual cash value
- Any cosmetic damage exclusion on metal roofs and walls
- Whether equipment and stored grain or feed are covered, and under which section
Crop damage is a separate matter. Crop losses are handled through crop insurance, not your property policy, and we don't adjust crop claims.
Metal outbuildings: dents vs. damage
Hail dents metal panels easily, and many policies on metal roofs and outbuildings exclude damage that is only cosmetic. The question becomes whether the hail affected how the panel works. Functional damage includes cracked or loosened fasteners, split seams, punctures, dented panel ribs that now let water pond or leak, broken skylight panels, and crushed gutters and trim. We photograph these close up and tie them to the storm date. More on the distinction in cosmetic vs. functional hail damage.
When you and the insurer disagree on the number
Many South Plains disputes aren't about whether hail hit the property but about how much it will cost to fix: how many squares of shingles, whether the siding can be patched, whether the metal panels can be repaired or must be replaced. When the gap is about the amount of loss, most Texas policies include an appraisal clause. Each side picks an appraiser, the two appraisers pick an umpire, and the panel sets the amount. Appraisal doesn't decide coverage questions, such as whether a cosmetic exclusion applies. Our guide to appraisal for hail damage claims explains when it makes sense.
After a storm in Lubbock and the South Plains
- Photograph everything metal. Gutters, vents, AC fins, mailboxes and outbuilding panels show hail size and direction.
- List every structure. House, garage, barn, shop, carport, fence, each with a note of what is damaged.
- Cover openings. Tarp roof damage and board broken windows. Keep receipts.
- Pull your policies. Homeowners, dwelling or farm. Note the deductible and any roof payment schedule.
- Report the claim and check your policy's deadline for reporting wind and hail damage.
Our fee is a percentage of the claim payment, capped at 10% by Texas law, with no upfront charge.
Free toolClaim settlement calculatorSee what your claim should pay after depreciation and your deductible, and what you net with or without a public adjuster.Communities covered from this page
Don't see your town? We serve every Texas county. Ask us about your property.
Frequently asked questions
My insurer depreciated my roof heavily. Is that allowed?
If your policy has an actual cash value roof schedule or endorsement, the insurer can pay the roof at a depreciated amount. If it is a replacement cost policy, depreciation is usually recoverable after repairs. Check your endorsements.
Are hail dents on my metal barn covered?
It depends on the policy covering the barn. Many exclude purely cosmetic damage to metal, but damage to fasteners, seams and panels that affects how the roof sheds water is functional and typically covered.
I own a rental near Texas Tech. Who pays for my tenant's damaged belongings?
The tenant's renters insurance, if they have it. Your landlord policy covers the building and property you own, such as appliances you supply.
How long do I have to file a hail claim in Lubbock?
There is no single answer for private policies; many set a deadline to report wind and hail damage, so read your policy's "Duties after loss" section. Our guide to hail claim deadlines in Texas explains what to look for.