Why documentation decides claims
An insurance adjuster can only pay for what is documented and tied to a covered cause of loss. When a claim comes back short, it's usually because something wasn't recorded before it was cleaned up, thrown away or repaired, or because there's no evidence linking the damage to a specific storm date. This checklist covers both.
Three habits that matter more than any single photo
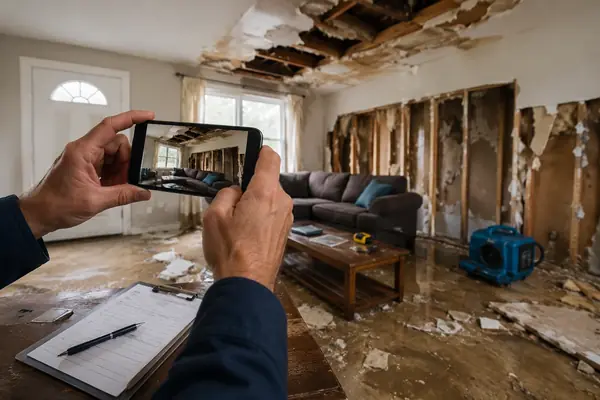
- Document before you change anything. Photograph and video every room and roof slope before mitigation, tear-out or debris removal. Emergency repairs to prevent more damage are expected, but record the condition first.
- Put everything in writing. Follow every phone call with an email summary. Written requests also start the Texas prompt payment clocks; see the deadline calculator.
- Keep one claim file. One folder (paper or cloud) for the policy, the estimate, letters, receipts and photos, organized by date. Our guide to documenting damage walks through the method.
Frequently asked questions
Where is my progress saved?
Only in this browser, using local storage. Nothing is sent to us. Clearing your browser data or switching devices starts a fresh list.
Should I throw away damaged items after I photograph them?
Not until the insurer says it doesn't need to inspect them. Keep samples of damaged flooring, carpet and roofing where you can, and photograph serial numbers and labels.
Do I need receipts for everything?
No. Receipts help, but photos, bank statements, manuals and online order histories also prove ownership and value. Start with the high-value items.