Property damage in Crowley can turn into a complicated insurance claim faster than many owners expect. A North Texas thunderstorm may damage shingles, vents, gutters, fencing, siding, and interior finishes in a matter of minutes. A broken pipe can spread water beneath flooring and behind walls before the visible stain appears. When the insurance company’s estimate does not include the full scope of the loss, a public adjuster in Crowley can help you document the damage and present the claim properly.
As a licensed Texas public adjuster, TX Public Adjusting represents homeowners, landlords, commercial property owners, and business operators—not insurance companies. Our team reviews policies, inspects damaged property, prepares claim documentation, evaluates carrier estimates, and negotiates on behalf of the policyholder.
TX Public Adjusting is operated by Rise Public Adjusting LLC, a licensed Texas public adjusting firm under Texas License #3356839.
Need insurance claim help in Crowley? Request a free claim review. There are no upfront fees.
Local Property Damage Challenges in Crowley
Crowley sits primarily in southern Tarrant County, with a small portion extending into Johnson County. The city borders Fort Worth and lies directly north of Burleson, placing it within the fast-growing southern portion of the Dallas–Fort Worth region.
That location gives Crowley property owners convenient access to the larger Metroplex, but it also exposes homes and commercial buildings to North Texas weather. Severe thunderstorms can bring hail, sudden wind gusts, heavy rain, lightning, and occasional tornado activity. During colder months, freezing temperatures can contribute to burst plumbing lines, damaged exterior systems, and water losses.
Crowley’s mix of established homes, newer subdivisions, retail buildings, schools, churches, offices, and light commercial properties creates a wide range of insurance claim concerns. A roof claim in an older property near central Crowley may involve repairability and matching questions. A newer home in a developing neighborhood may have damage to contemporary roofing materials, fencing, windows, or exterior finishes. A business property along a major roadway may also face signage, equipment, inventory, or business-interruption issues.
Local places such as Bicentennial Park, the Crowley Recreation Center, Main Street, and the FM 1187 and FM 731 corridors reflect the city’s combination of established community spaces and continued development. Bicentennial Park itself includes hills, creeks, wooded areas, and open space in northeast Crowley.
Why Property Owners Hire a Public Adjuster in Crowley
Insurance companies assign adjusters to investigate claims for the carrier. A public adjuster serves a different role. We represent the policyholder and work to present the covered loss from the property owner’s perspective.
Crowley homeowners and business owners often contact TX Public Adjusting when:
- The carrier’s estimate appears too low.
- The adjuster approved a small repair but the damage may be more extensive.
- Roofing, gutters, vents, flashing, siding, or interior damage was omitted.
- A water claim was limited because the cause or timeline was disputed.
- The claim has been delayed or communication has become difficult.
- The property owner does not understand depreciation or replacement-cost requirements.
- The carrier denied all or part of the claim.
- A contractor’s estimate is substantially higher than the insurer’s estimate.
- A commercial loss involves multiple buildings, tenants, equipment, or interrupted operations.
- The owner wants experienced claim representation before accepting a settlement.
A licensed public insurance adjuster in Crowley can inspect the property, compare the observed damage with the insurer’s scope, organize supporting evidence, and communicate with the carrier throughout the adjustment process.
No public adjuster can guarantee a specific settlement. The goal is to make sure the claim is carefully investigated, accurately documented, and supported under the terms and conditions of the policy.
Common Insurance Claims in Crowley
Hail Damage Claims
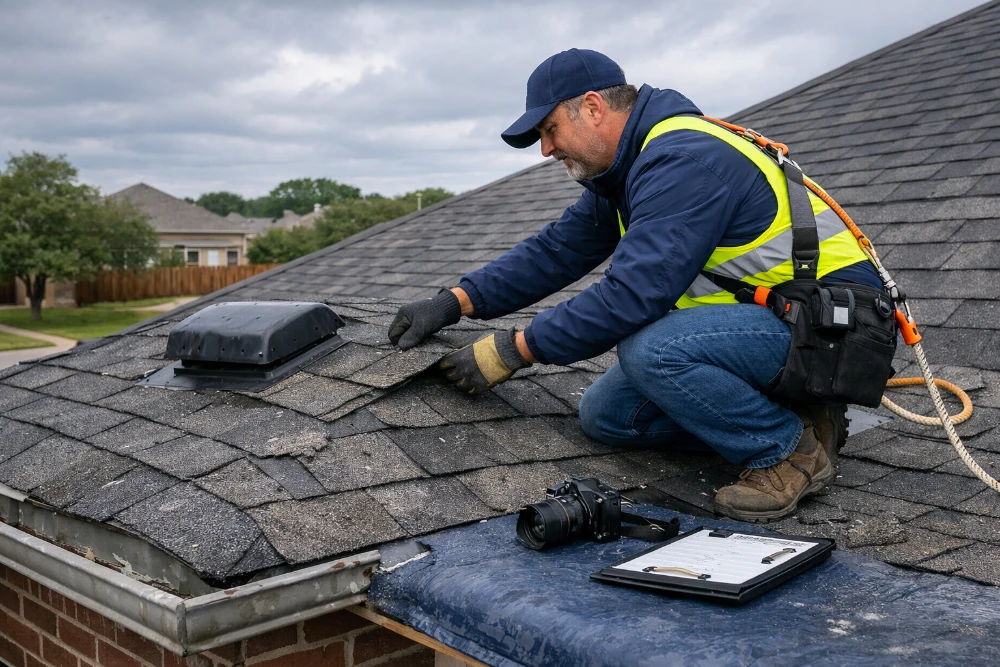
Hail is one of the most common property-loss concerns across North Texas. Property owners dealing with a hail damage roof insurance claim should look beyond the most obvious marks because even a short storm may affect roofing, vents, gutters, fencing, siding, and HVAC components.
A complete Crowley hail claim may involve:
- Asphalt shingle bruising or fractured mats
- Granule displacement
- Dents to roof vents and flashing
- Damage to gutters and downspouts
- Window-screen and frame damage
- Dented garage doors
- Fence and exterior paint damage
- Siding damage
- HVAC fin damage
- Skylight damage
- Interior water staining caused by compromised roofing
Photographs should show both close-up damage and wider views that establish where each condition appears on the property. Our guide explains how to document hail damage for an insurance claim before repairs or cleanup remove useful evidence. Some hail damage is difficult to identify from the ground. Other damage is visible but omitted from the original carrier estimate. We inspect the property as a complete system rather than treating each dent or stain as an isolated issue.
Wind and Storm Damage Claims
Crowley thunderstorms can produce wind strong enough to lift shingles, loosen flashing, damage fences, break tree limbs, and create openings in the building envelope. City alerts have warned residents that severe storms may bring large hail and winds capable of damaging roofs, siding, and trees.
Wind claims can become disputed when the insurer characterizes damage as wear, age, deterioration, or improper installation. Proper documentation should address the storm-related condition, the location of damage, resulting water intrusion, and the repairs needed to restore the property.
A storm claim may include:
- Missing, lifted, or creased shingles
- Damaged ridge caps
- Displaced metal panels
- Detached gutters
- Damaged fencing
- Fallen tree or limb impact
- Broken windows
- Wind-driven rain
- Interior ceiling or wall damage
- Detached exterior fixtures
- Damage to commercial signs or rooftop equipment
Roof Damage Claims
Roof claims are rarely as simple as counting missing shingles. The scope may need to consider underlayment, flashing, vents, decking, ridge materials, drip edge, gutters, code-related requirements, access, steep-slope charges, and matching concerns.
A carrier may estimate a localized repair even when the proposed repair cannot reasonably restore the roof to its pre-loss condition. It may also overlook collateral damage to soft metals, adjacent elevations, interior finishes, or roof-mounted equipment.
A public adjuster for a roof claim can review the insurer’s estimate line by line and compare it with the roof, exterior, and interior conditions documented at the property.
Water Damage Claims
A water damage public adjuster can help identify claim components beyond the area that appears visibly wet. Moisture may travel beneath tile, laminate, vinyl plank, carpet, cabinets, baseboards, drywall, and insulation. A small supply-line failure can affect several rooms.
Common Crowley water claims include:
- Burst or leaking pipes
- Failed plumbing connections
- Water-heater failures
- Appliance supply-line leaks
- Toilet or drain overflows
- Roof leaks after storms
- Water entering around windows or doors
- Ceiling and drywall damage
- Flooring and cabinet damage
- Disputes over mitigation or drying costs
The cause of loss matters. The policy may distinguish between sudden water discharge, long-term seepage, groundwater, floodwater, and rain entering through storm damage. We review the policy and available evidence to help present the claim accurately.
Fire and Smoke Damage Claims
A fire insurance adjuster working for the policyholder should evaluate far more than the area touched directly by flames. Smoke, soot, heat, water, chemical residue, and firefighting activity can affect the structure and personal property throughout the building.
A residential or commercial fire claim may include:
- Structural repairs
- Smoke and soot cleaning
- Odor treatment
- Electrical-system evaluation
- HVAC contamination
- Personal-property inventory
- Debris removal
- Temporary housing
- Code upgrades
- Business interruption
- Additional living expenses
Detailed inventories and organized documentation are especially important in fire claims. Our experience reviewing residential and commercial losses helps us identify claim categories that may be missed when the initial focus remains only on the burned area.
Freeze and Burst-Pipe Claims
Although Crowley is known more for spring storms, winter freezes can create widespread plumbing damage. Pipes in attics, exterior walls, vacant buildings, and poorly insulated areas may freeze and rupture.
The resulting loss can damage ceilings, walls, insulation, flooring, cabinets, electrical components, and personal property. In a commercial building, the water can also affect inventory, equipment, offices, or tenant spaces.
Freeze claims may become complicated by questions involving heat maintenance, emergency mitigation, pre-existing conditions, or the timing of discovery. Early documentation can make a major difference.
Commercial Property Claims
Commercial claims usually require more extensive coordination than a typical residential claim. A damaged roof may affect several tenant suites. Water intrusion may interrupt operations. Equipment or inventory may need specialized evaluation.
TX Public Adjusting assists Crowley owners with commercial property claims involving:
- Retail buildings
- Restaurants
- Churches
- Offices
- Warehouses
- Apartment and multifamily properties
- Self-storage facilities
- Light industrial properties
- Medical or professional spaces
- Mixed-use buildings
Commercial claim documentation may need to address building damage, contents, equipment, tenant improvements, mitigation invoices, operating expenses, and business-income concerns. We work to organize these moving parts into one clear claim presentation.
Why Insurance Claims Become Underpaid
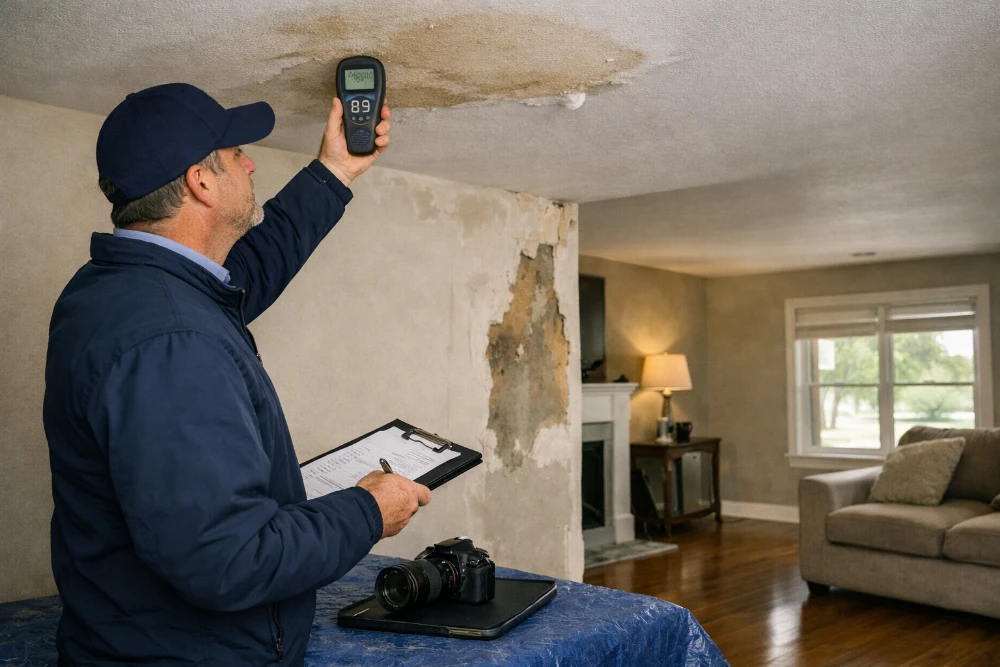
An underpaid claim does not always result from one obvious mistake. It is often the combined effect of several scope and documentation problems.
Missed Damage
The first inspection may be brief, particularly after a large regional storm when adjusters are handling a heavy claim volume. Damage to elevations, gutters, fencing, vents, interiors, or secondary structures can be missed.
Scope Omissions
The insurer may acknowledge damage but leave necessary work out of the estimate. Common omissions include material removal, underlayment, flashing, detach-and-reset work, access charges, debris handling, surface preparation, or related interior repairs.
Low Pricing
The insurer’s estimate may use pricing that does not reflect the actual labor and material costs needed to complete repairs in the Crowley and Fort Worth area.
Depreciation Issues
Property owners are often confused by the difference between actual cash value and replacement cost. Recoverable depreciation may depend on completing repairs and submitting required documentation within the policy’s deadline.
Repairability and Matching Problems
A proposed spot repair may not be practical if materials are brittle, discontinued, incompatible, or unable to match the surrounding surface. These issues need clear documentation rather than a general statement that the owner wants a full replacement.
Cause-of-Loss Disputes
The insurer may attribute damage to wear and tear, maintenance, age, settling, deterioration, or another excluded cause. A stronger claim presentation connects the observed damage to the reported event using photographs, weather information, inspection findings, and repair evidence.
Weak Documentation
A valid claim can still become underpaid when the file lacks detailed photographs, measurements, estimates, moisture records, inventories, receipts, or explanations tying each repair item to the covered loss.
Already received a low estimate? TX Public Adjusting offers a free Crowley claim review with no upfront fees.
Our Public Adjusting Process
Property owners who are unfamiliar with the profession can also review our guide explaining what a public adjuster does before deciding how to proceed.
1. Claim Review
We begin by learning what happened, when the loss occurred, what the carrier has done, and what concerns you have about the claim.
We may review:
- The insurance policy
- Claim correspondence
- Carrier estimates
- Denial or coverage letters
- Contractor proposals
- Photographs and videos
- Mitigation documents
- Repair invoices
- Personal-property inventories
This first review helps us determine where the claim stands and whether public adjusting assistance may be appropriate.
2. Property Inspection
We inspect the accessible damaged areas and document the conditions connected to the loss. Depending on the claim, this may include the roofing system, elevations, interior rooms, detached structures, commercial spaces, or damaged contents.
The purpose is to understand the full scope—not simply repeat the carrier’s inspection.
3. Documentation and Estimating
A strong claim file needs evidence. We organize photographs, measurements, scope notes, estimates, inventories, invoices, and other available support.
The estimate should describe the work required to restore the covered property, including related labor, materials, access, and repair steps.
4. Claim Presentation
We submit the documented claim position and communicate with the insurance company. When the carrier requests clarification or additional support, we respond with the relevant claim information.
5. Negotiation and Resolution
We compare carrier responses with the documented loss and negotiate disputed scope or pricing issues. The timeline depends on the complexity of the claim, the carrier’s response, inspections, requested documents, and any coverage questions.
Throughout the process, we keep the policyholder informed so that the claim does not feel like a closed conversation between insurance professionals.
How Crowley’s Location Affects Property Claims
Crowley is not simply a smaller extension of Fort Worth. Its location creates a distinct claim environment.
Properties near established central Crowley may have older roofs, additions, detached structures, mature trees, or building materials that are difficult to match after a loss. Developing areas near the city’s edges may include newer roofing systems, recently installed fencing, larger subdivisions, and ongoing construction.
The 76036 ZIP code also extends beyond Crowley’s municipal boundaries. Some properties with a Crowley mailing address are located in Fort Worth, unincorporated Tarrant County, Johnson County, or an extraterritorial jurisdiction.
That distinction can matter when documenting permits, code requirements, service locations, and the correct property address. Our focus remains on the actual insured location and policy—not merely the name used in the mailing address.
Crowley Neighborhoods and Communities We Serve
TX Public Adjusting serves property owners throughout Crowley and the surrounding 76036 area, including homes and businesses near:
- Deer Creek
- Crescent Springs Ranch
- Lasater Ranch
- Bridges
- Bent Creek Farms
- Carson Ranch
- Crestview
- Crystal Creek
- Emily Estates
- Laurenwood
- Longhorn Crossing
- Rancho Vista
- Rocky Creek Ranch
- Sendero Oaks
- Country Hill
- Central Crowley
- Main Street
- Crowley Road
- FM 1187
- FM 731
- Bicentennial Park
We also assist property owners who need a public adjuster in Fort Worth, as well as policyholders in Burleson, Joshua, Everman, Edgecliff Village, Rendon, Benbrook, Mansfield, and other communities across southern Tarrant County and northern Johnson County.
A storm does not stop at a city-limit sign. Our team evaluates the insured property and the claim circumstances wherever the loss occurred.
Why Choose TX Public Adjusting
Texas-Focused Claim Experience
Texas property claims have their own weather patterns, policy issues, building practices, and carrier disputes. Our work is focused on helping Texas policyholders after hail, wind, water, fire, freeze, roof, and commercial losses.
Licensed Representation
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839. Property owners should verify that anyone offering public adjusting services is properly licensed.
Independent Policyholder Representation
We do not work for the insurance company. Our responsibility is to the policyholder who hires us.
That independent role matters when the insurer’s estimate is low, the scope is incomplete, or the carrier disputes whether certain damage belongs in the claim.
Residential and Commercial Knowledge
Residential and commercial claims require different documentation. A home claim may involve roofing, interiors, contents, and additional living expenses. A business claim may also include specialized systems, tenants, inventory, equipment, and interrupted operations.
Our team has reviewed thousands of claim files and brings experience with both residential and commercial property losses.
Detailed Claim Preparation
A persuasive claim is not built on a demand for “more money.” It is built on evidence.
We focus on:
- Policy review
- Damage documentation
- Accurate scope development
- Estimate comparison
- Claim correspondence
- Supporting records
- Clear negotiation
Free Claim Review and No Upfront Fees
You can speak with TX Public Adjusting about your Crowley property claim without paying an upfront review fee. We explain what we see, where the claim may have problems, and what the next step could involve.
Frequently Asked Questions
What does a public adjuster in Crowley do?
A public adjuster represents the policyholder during a property insurance claim. We inspect damage, review the policy and carrier estimate, prepare supporting documentation, communicate with the insurer, and negotiate disputed claim issues.
Unlike the insurance company’s adjuster, a public adjuster does not represent the carrier. TX Public Adjusting works for the Crowley property owner who hires us.
When should I hire a Crowley public adjuster?
Many owners contact us after receiving a low estimate, partial denial, full denial, delayed response, or repair scope that does not match the visible damage. You can also hire a public adjuster earlier, particularly when the loss is large or involves a commercial property.
The best time depends on the claim. Our guide explains when it is too late to hire a public adjuster and why it is generally better to request help before signing releases, completing all repairs, or allowing important policy deadlines to pass.
Can you help after my insurance company has already inspected the property?
Yes. A carrier inspection does not prevent you from obtaining a separate claim review. Understanding the difference between a public adjuster versus an independent adjuster is helpful: the public adjuster represents the policyholder, while the independent adjuster is typically retained by the insurance company.
Keep the carrier estimate, photographs, letters, emails, and contractor documents so they can be reviewed together.
What types of Crowley insurance claims do you handle?
We assist with hail, wind, roof, water, fire, smoke, freeze, burst-pipe, storm, residential, and commercial property claims.
The specific policy terms and facts of the loss determine what may be covered. Our role is to document and present the claim under the applicable policy.
How much does a public adjuster cost in Texas?
Public adjusters commonly work under a contingency-fee agreement based on the claim recovery. The agreement should explain the fee clearly before work begins.
TX Public Adjusting offers a free initial claim review and does not charge an upfront fee for that review.
Can a public adjuster reopen an underpaid claim?
Some underpaid claims may be eligible for supplemental review, reconsideration, appraisal, or another policy-based claim process. The available option depends on the policy, claim status, dates, prior payments, and carrier correspondence.
We review the existing claim file before recommending a path. No result can be guaranteed, but an underpaid claim should not automatically be treated as final without reviewing the relevant documents.
What should I do immediately after hail or wind damage in Crowley?
Protect people first. Once conditions are safe, take photographs and video of the property, note the date and approximate time of the storm, and prevent additional damage where reasonably possible.
Avoid permanent repairs until the damage has been documented. Save receipts for temporary work, tarping, cleanup, lodging, or emergency services. Do not climb onto a wet or damaged roof.
Does homeowners insurance cover roof damage in Crowley?
Many homeowners policies cover sudden roof damage caused by hail, wind, falling objects, or other covered events. Coverage depends on the policy language, exclusions, deductible, roof-payment schedule, endorsements, and the cause of damage.
Some policies pay roof losses differently based on age or material. Review the declarations, endorsements, and settlement provisions rather than relying only on a general coverage summary.
Can you help with a commercial property claim near Crowley?
Yes. We assist commercial property owners, landlords, churches, retail operators, office owners, apartment owners, warehouse operators, and other businesses in and around Crowley.
Commercial claims may require building estimates, equipment records, tenant information, inventory documentation, mitigation records, and business-income support.
How long does a property claim take?
There is no single timeline. A straightforward residential claim may resolve faster than a large commercial, fire, water, or disputed roof claim.
Timing can depend on inspection scheduling, carrier response, requested documentation, expert involvement, repair estimates, coverage questions, and the extent of negotiation. We work to keep the file organized and moving while giving the carrier the support needed to evaluate the claim.
Get Insurance Claim Help in Crowley
A damaged property is stressful enough without spending weeks trying to determine what the insurance estimate missed. TX Public Adjusting helps Crowley homeowners and business owners document their losses, understand their claims, and communicate with the insurance carrier from a position supported by evidence.
If your roof claim was underpaid, your water claim was limited, your storm damage was overlooked, or your commercial loss has become difficult to manage, speak with a licensed Texas public adjuster.
Contact TX Public Adjusting for a free Crowley property claim review.
- No upfront review fees
- Residential and commercial claims
- Licensed Texas public adjuster
- Independent policyholder representation
- Rise Public Adjusting LLC
- Texas License #3356839