The short answer: a staff adjuster is an employee of your insurance company, an independent adjuster is a contractor your insurance company hires, and a public adjuster is a licensed professional you hire. The first two are paid by the insurer and report to the insurer. The third is paid by you and, under Texas law, represents only you.
All three can be honest, skilled people. The difference is whose estimate they are writing and who signs off on it.
The three adjusters side by side
| Staff adjuster | Independent adjuster | Public adjuster | |
|---|---|---|---|
| Hired by | Your insurance company (employee) | Your insurance company (contractor or adjusting firm) | You, the policyholder |
| Paid by | Insurer salary | Insurer, per claim or per day | You, as a percentage of the claim payment (capped at 10% in Texas) |
| Represents | The insurer | The insurer | The insured only |
| Typical role | Field inspections, or desk review of estimates and payment decisions | Field inspections and estimates, often brought in after large storms | Documents the loss, writes your estimate, negotiates with the insurer |
| Final say on payment | Within their authority limit; larger amounts go up the chain | Usually none; recommends, and the carrier approves | None; presents and argues your claim |
| Can you choose them? | No | No | Yes, and you can cancel the contract within 72 hours of signing |
Staff adjusters: the company's own employees
A staff adjuster works directly for the insurance company. Some are field adjusters who come to your property. Many are desk adjusters who never see it: they review the field estimate, photos and reports, apply the policy, and decide what gets paid. On a lot of Texas claims the person you talk to on the phone is a desk adjuster, and the person on your roof was someone else.
Staff adjusters follow the company's guidelines on things like when a roof slope is repaired versus replaced, how depreciation is applied, and when to call in an engineer. Those guidelines are written by the insurer, for the insurer.
Independent adjusters: contractors the insurer hires
The word "independent" confuses people. It means independent of any single insurance company, not independent of insurers. An independent adjuster works for an adjusting firm, or for themselves, and takes assignments from insurance carriers. When a hailstorm or hurricane produces thousands of claims at once, carriers often bring in independent adjusters, sometimes from out of state, to handle the volume.
The independent adjuster inspects, photographs and writes an estimate, then sends it to the carrier. They are paid by the insurer, and their future assignments depend on the insurer being satisfied with their work. They usually cannot approve a payment; the carrier's staff makes that call. So when an independent adjuster says "I'll recommend it," that is often literally all they can do.
Tip: Ask any adjuster who comes to your property two questions: "Who do you work for?" and "Who pays you?" Write the answers in your claim notes with their name, company and phone number.
Public adjusters: the one you hire
A public adjuster is licensed by the Texas Department of Insurance to represent policyholders. The contract must be on a TDI-approved form and must state "WE REPRESENT THE INSURED ONLY" (Tex. Ins. Code §4102.103). The fee comes out of the claim payment, so the public adjuster is paid only if the insurer pays. Texas caps that fee at 10% of the settlement.
A public adjuster does the same technical work as the insurer's adjusters, inspection, measurement and an Xactimate estimate, but presents the result as your claim and argues for it. For the full description of the job, see what is a public adjuster.
Same roof, different estimates: a Texas hail example
Here is a pattern we see on hail claims. The numbers below are a made-up example to show the mechanics, not a real claim.
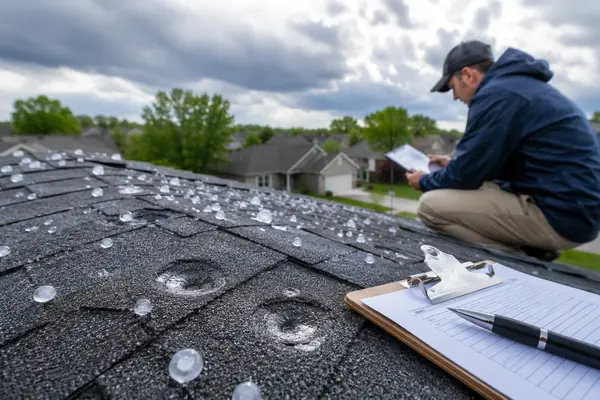
A storm moves across Central Texas. An independent adjuster inspects a two-story home, marks hits on the south and west slopes, and writes an estimate to replace those two slopes, plus a few gutter runs. The desk adjuster applies the policy's 1% wind and hail deductible and depreciation, and the homeowner receives a check for a fraction of what their roofer quoted.
A public adjuster looks at the same roof and asks different questions:
- Were the north and east slopes test-squared, or skipped because the hits were harder to see?
- Can the replaced slopes actually be matched to the old ones, or is the shingle discontinued? (Texas has no matching statute, so this turns on the policy wording and the facts. See matching rules for Texas roofs.)
- Did the estimate include drip edge, starter, ridge cap, flashing, vent boots and code-required items, or just shingles?
- Were soft metals, window screens, fence stain, and the AC condenser fins documented?
- Is the depreciation recoverable under this policy, or is there an ACV roof endorsement?
None of that requires the insurer's adjuster to have acted in bad faith. They inspected quickly, under the company's guidelines, during a week with a pile of other claims. The public adjuster's job is to make the evidence for everything that was missed impossible to overlook. More on how carriers grade roofs is in how insurance companies evaluate hail damage.
How the three work together on one claim
Hiring a public adjuster does not remove the insurer's adjusters. Your claim still has a staff or independent adjuster on the company's side; what changes is that someone now answers them with equal technical detail. On a typical claim it goes like this:
- Letter of representation. The public adjuster notifies the insurer in writing that they represent you, so correspondence and inspection requests are copied to them.
- Joint inspection. The insurer's field adjuster and the public adjuster walk the property together, ideally on the roof at the same time, so disagreements are about the same hail hits and the same wet walls.
- Estimate against estimate. Both sides usually write in Xactimate, so the comparison is line by line rather than a total against a total.
- Desk review and negotiation. The staff desk adjuster reviews the public adjuster's estimate and evidence and decides what to add. Disputed items go back and forth, sometimes with a re-inspection.
- Appraisal if needed. If the two sides still disagree on the amount, either may demand appraisal where the policy allows it.
Engineers and other people the insurer may send
On larger or disputed claims, the insurer may also send a structural engineer, a roofing consultant, a contents specialist or a building consultant. These are not adjusters, but their reports carry weight. They are hired by the insurer too. Ask the insurer in writing for a copy of any report it relies on to limit or deny your claim; a public adjuster can then answer it point by point.
How to tell which adjuster you are dealing with
- The insurer's acknowledgment letter or email usually names the assigned adjuster. Under §542.055 the insurer must acknowledge your claim and start its investigation within 15 days of notice. If the person who shows up is from a different company, they are likely an independent adjuster on assignment.
- The business card or email signature shows either the carrier's name (staff) or an adjusting firm's name (independent).
- Someone who knocks on your door after a storm offering to "handle your claim" is not from your insurer. They may be a public adjuster, or a contractor who is not allowed to do that under §4102.163. Check the license before you talk numbers. Our guide to choosing a public adjuster covers the red flags.
Do you need all three?
No. Every claim has an insurer's adjuster, staff or independent. Whether you add a public adjuster is your decision, and plenty of small, straightforward claims do fine without one. We lay out an honest way to decide in should I use a public adjuster, and our short self-assessment walks through the same questions.
Frequently asked questions
Does an independent adjuster work for me?
No. An independent adjuster is hired and paid by your insurance company to inspect and estimate the claim. "Independent" means they are not a company employee, not that they are neutral or on your side.
What is the difference between a public adjuster and an insurance adjuster?
An insurance adjuster, staff or independent, works for the insurer. A public adjuster is licensed by TDI to represent the policyholder, is hired by you, and is paid a percentage of the claim payment, capped at 10% in Texas.
Can I talk to the insurance adjuster if I hire a public adjuster?
Yes. You can stay involved, but most people route claim communication through the public adjuster so nothing is said off the record that conflicts with the documented claim.
Can I request a different insurance adjuster?
You can ask the insurer to reassign the claim or escalate to a supervisor, but the insurer decides. Putting the request and your reasons in writing creates a record either way.
Joseph inspects, documents and negotiates residential and commercial property claims across Texas, working only for policyholders.