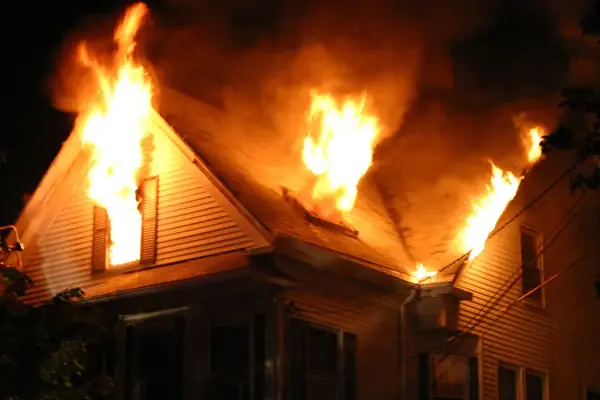
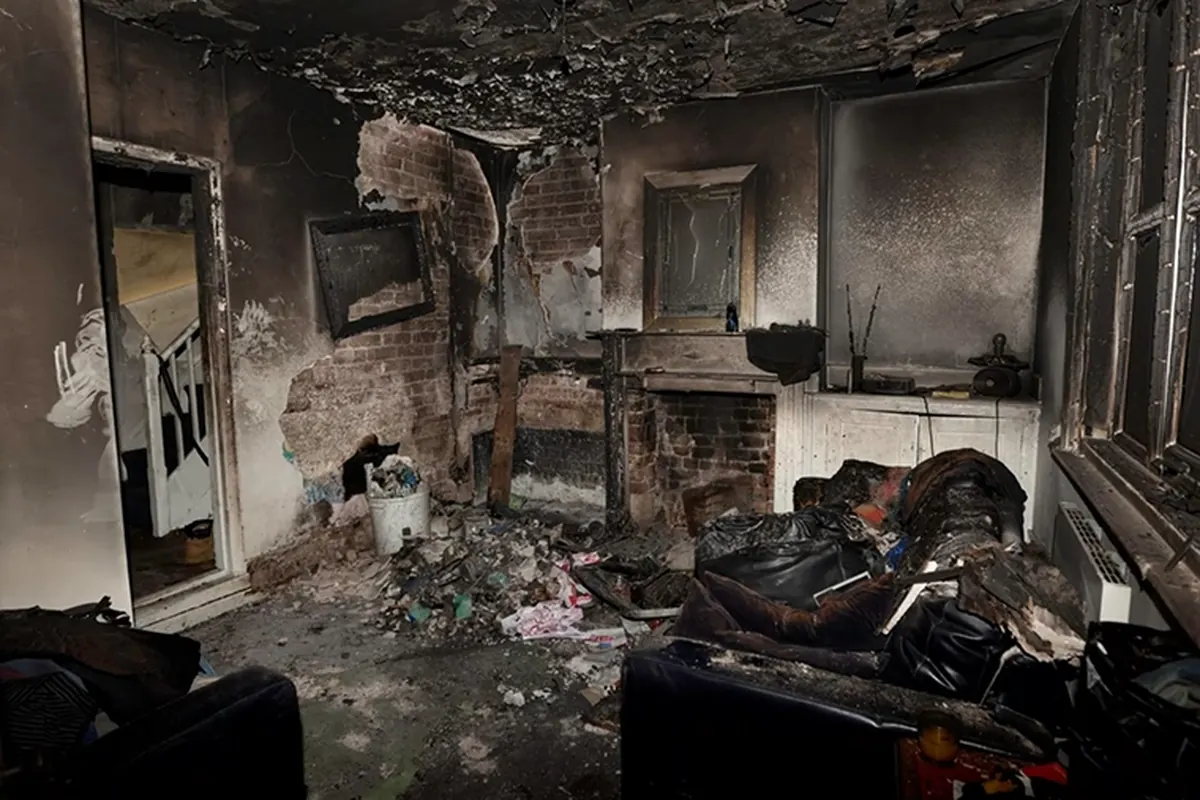
The cost of removing fire debris depends on four things more than anything else: how much material has to come out, whether it includes hazardous materials such as asbestos, how easily crews and trucks can reach it, and what the local landfill charges to take it. A one-room kitchen fire might need a crew and a dumpster for a few days. A total loss can need testing, abatement, heavy equipment and many truckloads. The price spread between those two jobs is enormous, which is why any single "average cost" figure is close to useless for your house.
The better news: on a covered fire, most Texas homeowners policies pay to remove the debris of covered property, and many add extra money for debris removal when the dwelling limit is used up. Before you pay a hauler or sign a demolition contract, check what your policy says and document the scene.
What fire debris removal includes
"Debris removal" on a fire claim usually covers more than hauling away burned lumber:
- Demolition and removal of building materials that can't be saved: framing, drywall, insulation, roofing, flooring and cabinets.
- Removal and disposal of destroyed contents and furniture, after they have been inventoried.
- Hazardous material testing and abatement where needed.
- Loading, hauling, and landfill or transfer station fees.
- On a total loss, removal of the foundation or slab if an engineer finds it can't be reused, and leaving the lot ready to rebuild.
It doesn't include soot cleaning and deodorizing of the parts of the house that stay, or the rebuild itself. Those are separate lines on the estimate.
What drives the cost
| Cost driver | Why it matters |
|---|---|
| Volume of debris | Most jobs are priced by the load, the ton or the dumpster. A second story, a full attic and a house full of contents all add volume. |
| Wet debris | Firefighting water soaks drywall, insulation and contents. Wet debris weighs far more, and weight is what landfills charge for. |
| Hazardous materials | Older homes may contain asbestos in flooring, ceiling texture, siding or pipe insulation, and lead in paint. Testing comes first, and abatement is specialized work that costs far more than ordinary demolition. |
| Partial vs. total loss | Selective demolition inside a standing house is slower, hand-carried work. A total loss may allow machine demolition, which moves more material per hour but needs heavy equipment and haul trucks. |
| Access | Narrow lots, tight alleys, fences, overhead lines, mature trees and neighboring houses all slow the work or limit equipment. |
| Disposal fees and distance | Landfill and transfer station rates vary across Texas, and so does the distance to the nearest facility that accepts construction debris. |
| Permits and utilities | Demolition usually needs a permit and confirmed disconnection of gas, electric and water. |
| Foundation | If the slab or pier-and-beam foundation is damaged by heat, removing it adds significant cost. |
A rough sense of scale
We don't publish price ranges, because they vary so widely by city, house and contractor that a number would mislead more often than help. As a rough sense of scale only:
- A contained room fire usually means selective demolition of one or two rooms, a dumpster or two, and contents disposal. The smallest debris job.
- A multi-room fire with heavy smoke and water means more demolition, much heavier wet debris, and often testing before work starts in an older home.
- A total loss means full demolition, possible abatement, heavy equipment, many loads to the landfill and possibly foundation removal. Often many times the cost of a room fire.
The only number that matters for your claim is the one built from your house's scope: an itemized bid or an Xactimate estimate based on actual quantities.
Does homeowners insurance pay for fire debris removal?
On a covered fire, usually yes. How much depends on the policy, so look for these provisions:
- Debris removal coverage. Most homeowners policies pay to remove the debris of covered property damaged by a covered loss. Check whether it is included within the dwelling limit, and whether the policy adds an additional amount, usually stated as a percentage of the limit, when the limit is exhausted.
- Dwelling and other structures limits. Debris from a detached garage or shed falls under the other structures coverage.
- Personal property. Removing destroyed contents is generally part of the contents claim.
- Ordinance or law coverage. If the city requires demolition of undamaged parts of the house, or code upgrades when you rebuild, this coverage may pay. It is often a percentage of the dwelling limit, and some policies don't include it unless it was added.
- Tree debris. Policies often have a separate, smaller limit for removing trees.
On a total loss, debris removal competes with the rebuild for dollars if it is paid inside the dwelling limit. That is exactly when an additional debris removal amount matters, so read that section of the policy before you agree to any figure. Our guide to fire damage insurance in Texas covers the rest of the policy.
Get more than one bid, on the same scope
Bids for demolition and debris removal vary widely, often because contractors are pricing different jobs. Ask each one to bid the same written scope, and check that the bid:
- Itemizes demolition, hauling, disposal fees and permits separately.
- States how many loads or tons are included and what happens if there are more.
- Says whether hazardous material testing and abatement are included or excluded.
- Includes protection of the parts of the house that stay, if it is a partial loss.
- Comes from a contractor with liability insurance who can show it to you.
Send the bids to your adjuster and compare them to the debris lines on the carrier's estimate. If the carrier's estimate is short, the gap is usually in quantities, wet-debris weight or abatement.
Tip: A demolition or restoration contractor can bid the work, but under Tex. Ins. Code §4102.163 a contractor cannot act as your public adjuster on property they are repairing or may repair. Keep the negotiation of the claim with you or a licensed public adjuster.
Document everything before it's removed
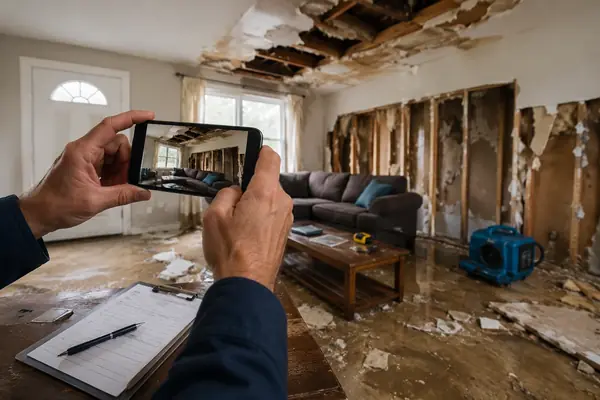
Debris is evidence. Once it is in a landfill, nobody can count it, measure it or see what it was. Before removal starts:
- Wait for the scene to be released. The fire department, and often the insurer's cause-and-origin investigator, may need to examine the scene first. Ask your adjuster in writing whether the carrier needs access before demolition.
- Photograph and video every room. Use the wide, medium and close-up method from our damage documentation guide. Capture ceilings, attic, framing and contents.
- Inventory the contents. List what you can identify, room by room, before it is hauled. The contents inventory builder helps.
- Get hazardous material testing done first in older homes. Results affect the scope and the cost, and the carrier will want to see them.
- Get the carrier's agreement on the scope. Ask the adjuster to confirm in writing that the debris removal scope is approved before the work begins.
We document fire losses with photos and a Matterport 3D scan before demolition, so the condition of each room is preserved for the claim after the debris is gone.
Who gets the check
If you have a mortgage, the lender is likely to be named on the dwelling payment, and you will need its endorsement. That can slow payment to a demolition contractor, so ask the contractor how they handle mortgage-company checks before you sign. If you hire a public adjuster, Texas law requires that you remain a payee on every claim check, and the adjuster may never sign or endorse a check for you (Tex. Ins. Code §4102.104).
If your fire claim involves a total loss, heavy smoke, or a debris and demolition scope the carrier won't agree to, see how we handle fire and smoke damage claims.
Frequently asked questions
How much does it cost to clean up after a house fire?
It varies widely. A contained room fire may need only selective demolition and a dumpster or two, while a total loss can need testing, abatement, heavy equipment and many loads to the landfill. The real number comes from an itemized bid based on your house.
Does homeowners insurance cover debris removal after a fire?
On a covered fire, most homeowners policies pay to remove debris of covered property. Many add an additional amount, often a percentage of the dwelling limit, when the limit is used up. Check your policy's debris removal section.
Is debris removal included in the dwelling limit?
It depends on the policy. Some pay debris removal within the dwelling limit and add extra coverage only if the limit is exhausted, which matters most on a total loss. Read the policy wording before agreeing to a figure.
Can I start clearing debris before the adjuster sees it?
Wait until the fire department and the insurer have released the scene, and photograph and inventory everything first. Ask your adjuster in writing whether they need access before demolition starts.
Who pays for asbestos removal after a house fire?
Testing and abatement needed to remove fire debris are generally part of the debris removal and dwelling claim on a covered loss. Get test results and an itemized abatement bid to the adjuster before the work starts.
Joseph inspects, documents and negotiates residential and commercial property claims across Texas, working only for policyholders.