

Property damage in Beach City can become complicated quickly. This is a small Chambers County community, but its location along Trinity Bay puts local homes and businesses directly in the path of many of the problems that make Gulf Coast insurance claims difficult: hurricane winds, wind-driven rain, severe thunderstorms, roof damage, water intrusion, and flooding concerns.
If your insurance company has underestimated damage, omitted repairs, delayed the claim, or issued a payment that does not appear sufficient to restore the property, a public adjuster in Beach City, TX can give the claim a second set of eyes.
TX Public Adjusting represents policyholders—not insurance companies. We review policies, inspect property damage, document the scope of loss, prepare estimates and supporting evidence, and negotiate with the carrier based on the damage and applicable coverage.
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839. We work with residential and commercial property owners throughout Texas and have experience reviewing thousands of property claims.
Concerned about an insurance settlement in Beach City? Request a Free Claim Review. There are no upfront fees to have your situation reviewed.
Property Claims Are Different in Beach City
Beach City is not a typical inland Texas suburb.
Homes spread along FM 2354 and Tri-City Beach Road toward Trinity Bay include waterfront properties, custom homes, larger rural-style lots, docks, detached structures, fences, and improvements exposed to the open bay environment. Neighborhoods and residential areas such as Bayridge, Beach Haven, North Point, Oaks at Houston Point, Bay Place, and Barrow Ranch give Beach City a distinct mix of bayfront and low-density residential property.
That setting changes the way property losses need to be evaluated.
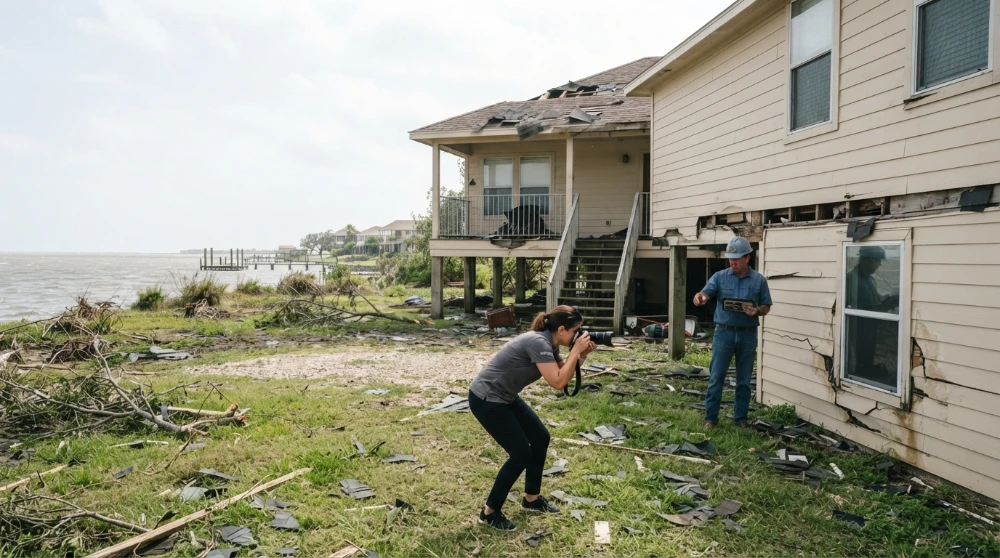
A tropical system may produce obvious roof damage, but it can also create less visible problems around flashing, roof penetrations, soffits, fascia, windows, siding, interior ceilings, insulation, detached structures, and exterior equipment. Wind-driven rain may enter through storm-created openings and spread beyond the room where staining first appears.
Properties closer to the Trinity Bay shoreline can present additional questions involving water source and causation. Those distinctions matter because storm-driven property damage and rising-water flooding may be treated differently under insurance policies.
Beach City property owners therefore benefit from documenting not only what was damaged, but also how the damage occurred and how far it extends.
Why Property Owners Hire a Public Adjuster in Beach City
Your insurance company’s adjuster evaluates the loss for the carrier. A public adjuster represents the policyholder. Understanding the difference between a public adjuster vs. insurance adjuster can be especially helpful when there is disagreement over the scope or value of storm damage.
That difference becomes especially important when there is disagreement over the scope or value of a claim.
A Beach City public insurance adjuster can help when:
- The carrier’s estimate leaves out visible or hidden damage.
- The roof was approved for a small repair when broader storm damage may exist.
- Interior water damage extends farther than the insurer documented.
- The insurance company applies depreciation you do not understand.
- Contractor pricing and the carrier estimate are far apart.
- The claim involves multiple buildings or categories of damage.
- A commercial claim is disrupting operations.
- The carrier has denied all or part of the claim.
- You received payment but are unsure whether the settlement reflects the complete loss.
- You simply want an experienced review before accepting the carrier’s position.
Our job is not to manufacture damage or promise a particular settlement. It is to identify, document, estimate, and present covered damage as completely and accurately as possible.
Beach City’s Storm and Property-Damage Risks
Beach City’s position on the upper Texas Gulf Coast creates a different insurance environment than communities farther inland.
Hurricanes and Tropical Storms
Trinity Bay may provide a peaceful backdrop most of the year, but Beach City remains exposed to Gulf tropical systems.
Beach City remains exposed to tropical storms and hurricanes moving through the upper Texas Gulf Coast. Property owners dealing with hurricane property damage may face a combination of roof damage, exterior damage, wind-driven rain and interior water intrusion.
Hurricane and tropical-storm claims can involve combinations of:
- Missing or lifted roofing materials
- Creased or damaged shingles
- Metal-roof damage
- Damaged flashing and roof accessories
- Fascia and soffit damage
- Broken or leaking windows
- Exterior siding damage
- Fence and detached-structure losses
- Wind-driven rain
- Wet drywall and insulation
- Flooring damage
- Contents losses
After a large regional storm, adjusters may be handling many files simultaneously. That makes thorough policyholder documentation especially valuable.
Flooding and Rising Water
Beach City’s waterfront location also makes flood exposure part of local property ownership.
Flood claims need careful attention because rising surface water is not the same as rain entering through storm damage. Coverage depends on the policy and cause of loss. Standard property insurance and separate flood insurance may respond differently.
A public adjuster’s first task should therefore include understanding the reported cause of damage and the policies available—not simply labeling every water loss the same way.
Severe Thunderstorms, Wind, and Hail
Hurricanes are not the only storms capable of generating claims in Beach City. Strong thunderstorms can produce damaging straight-line wind, hail, intense rainfall, and flying debris.
Hail damage can be particularly difficult for property owners to identify from the ground. The roof may appear intact while shingles, metal components, vents, gutters, flashing, or other exterior surfaces show impact damage during a closer inspection.
Freeze and Pipe Damage
The Gulf Coast is better known for heat and storms than freezes, but hard-freeze events can create major claims when plumbing fails.
A burst supply line can release large quantities of water into walls, cabinets, ceilings, flooring, and insulation before the source is found. The visible water is only part of the claim; drying, demolition, access, reconstruction, and damaged contents may also need to be evaluated.
Common Insurance Claims in Beach City
| Claim Type | Damage We Commonly Review |
| Hail Damage | Shingles, metal components, gutters, vents, siding and exterior systems |
| Wind & Storm Damage | Roofing, flashing, windows, siding, fences and detached structures |
| Water Damage | Drywall, insulation, flooring, cabinets, ceilings and contents |
| Roof Claims | Missing materials, uplift, penetrations, flashing and related interior damage |
| Fire & Smoke | Structure, smoke residue, contents, cleanup and additional expenses |
| Commercial Claims | Building damage, contents, equipment and business-related property losses |
Hail Damage Claims
A proper hail damage roof insurance claim involves more than counting visible dents. We evaluate roofing materials, accessories, soft metals, exterior components and related building damage to determine whether the carrier’s inspection captured the complete storm scope.
For Beach City properties with larger roof surfaces or multiple detached structures, missed items can add up quickly.
Water Damage Claims
Water moves. When a leak affects multiple rooms or building components, working with a water damage public adjuster can help the property owner determine whether the insurance company’s scope accounts for the complete loss.
A leak that begins near a roof penetration or plumbing fixture may affect insulation, framing cavities, drywall, flooring, cabinets and adjacent rooms. An estimate based only on the most obvious stain may fail to address the full repair sequence.
We document the affected areas and compare the carrier’s scope against what may actually be required to restore the property.
Fire Damage Claims
Fire losses frequently involve several categories at once. A fire insurance adjuster working for the policyholder can help document direct burn damage, smoke residue, odor, water from suppression efforts, personal property, demolition and other covered portions of the loss.
A Beach City fire claim may therefore require considerably more documentation than the visible burned area suggests.
Storm Damage Claims
Storm losses are common claim scenarios in the Chambers County and upper Galveston Bay area.
We examine the relationship between the storm event, exterior damage, interior water entry, and the carrier’s proposed repairs so that the claim tells a clear and supported story.
Roof Damage Claims
Roof claims are a frequent source of disagreement because the dispute is often not about whether some damage exists. It is about how much exists and what repairs are reasonably required. A public adjuster for a roof claim can compare the carrier’s scope with the documented roof and related building damage.
Carrier estimates may differ from contractor scopes on:
- Roofing quantities
- Flashing
- Underlayment
- Ventilation
- Valleys
- Drip edge
- Steep or high-access charges
- Detach-and-reset items
- Related interior repairs
A detailed scope review can reveal those differences.
Commercial Property Claims
TX Public Adjusting also serves as a commercial public adjuster for business and commercial property owners in Beach City and surrounding Chambers County communities.
Commercial losses can involve roofing systems, exterior walls, inventory, equipment, interior finishes, tenant improvements, multiple structures and operational disruption. These files often require more extensive documentation and coordination than a typical residential claim.
Why Insurance Claims Become Underpaid
An underpaid claim does not always begin with a dramatic denial. Frequently, the problem is a collection of smaller omissions.
Missed Damage
The inspection may identify the main damaged area while overlooking adjoining components or secondary damage.
Scope Omissions
A carrier may acknowledge a repair but leave necessary labor, materials, access work, removal, replacement, or associated trades out of the estimate.
Depreciation Issues
Replacement-cost and actual-cash-value calculations can be confusing. Property owners may not understand what was depreciated, whether depreciation can be recovered, or what documentation the carrier requires.
Low or Incomplete Estimates
Contractor bids sometimes come in substantially above the insurer’s estimate because the two documents contain different quantities, materials, labor assumptions, or repair methods. When legitimate roofing materials, labor, quantities or related repairs are missing, hail damage claim supplements may be used to document items that were not included in the carrier’s original scope.
The right question is not simply, “Which number is higher?”
The question is why the numbers are different.
Documentation Problems
Photos without context, incomplete inventories, missing measurements, and poorly organized contractor paperwork can weaken an otherwise legitimate claim.
A well-prepared claim file connects the loss, evidence, estimate, policy provisions, and requested payment.
Our Public Adjusting Process
1. Claim Review
We begin by discussing what happened, when the loss occurred, what the carrier has done so far, and why you are concerned.
When available, we review the insurance policy, carrier estimate, correspondence, payment information, denial letters, photographs, contractor estimates, and other claim documents.
2. Property Inspection
We inspect the reported damage and compare existing conditions with the carrier’s scope.
For Beach City storm claims, that may include roofing, exterior elevations, windows, interior water damage, detached structures and other affected areas.
3. Documentation and Estimate Review
We organize photographs, measurements, inventories, estimates and supporting information.
The goal is to create a clear scope showing what was damaged and what work may reasonably be required.
4. Claim Presentation and Negotiation
TX Public Adjusting communicates with the insurance company on the policyholder’s behalf and presents documented differences in scope or valuation.
This may involve answering carrier questions, reviewing revised estimates, supplying additional documentation and addressing omitted items.
5. Settlement and Claim Resolution
We continue working through the adjustment process until the documented issues are addressed or the claim reaches the appropriate resolution available under the circumstances.
No licensed public adjuster can guarantee a particular outcome. What we can provide is independent representation built around documentation, policy review and claim experience.
Already received an estimate or payment? You do not necessarily have to accept the carrier’s first scope as the final word. Contact TX Public Adjusting for a Free Claim Review.
Local Claim Considerations Near Trinity Bay
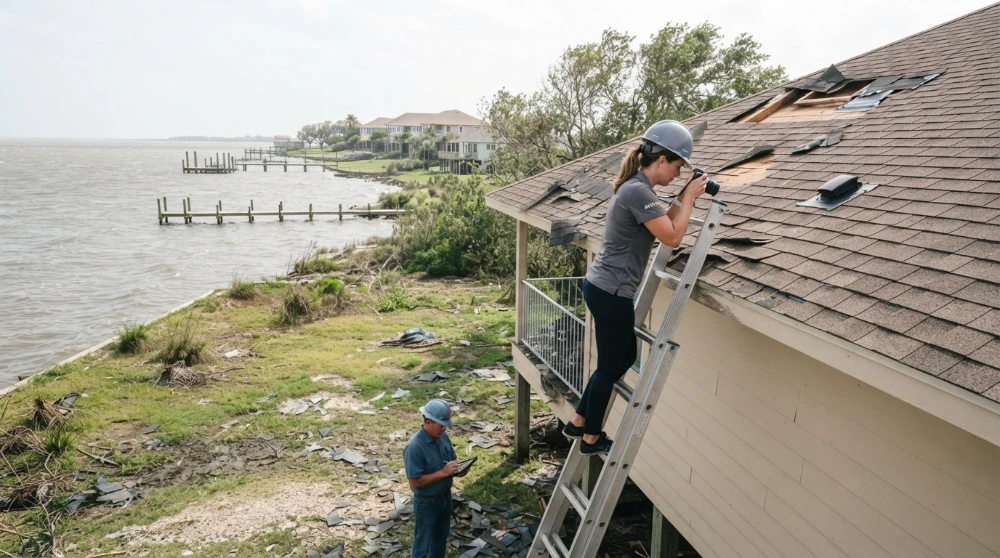
Beach City’s waterfront character deserves special attention during an insurance inspection.
Around Bayridge and the Trinity Bay shoreline, wind can affect roofs, docks, fences and exterior components while rain enters through openings elsewhere in the structure.
Properties around North Point and Oaks/Houston Point may include larger custom homes, more complex roofs and substantial exterior improvements. A missed elevation, roof section or detached structure can materially change the claim scope.
Along Tri-City Beach Road and FM 2354, properties range from traditional homes to larger lots with accessory structures. Each building should be evaluated based on its own damage rather than through a one-size-fits-all storm estimate.
McCollum Park, overlooking Trinity Bay, is a reminder of how closely Beach City’s identity is tied to the water. That waterfront setting is one of the community’s strengths, but it also makes wind, rain and water-source questions central to many local property claims.
Why Choose TX Public Adjusting
TX Public Adjusting focuses on representing Texas policyholders after property damage.
Licensed Texas Public Adjuster
Services are provided through Rise Public Adjusting LLC, Texas License #3356839.
We Represent the Policyholder
An insurance-company adjuster works for or on behalf of the carrier.
A public adjuster is retained by the insured and represents the policyholder’s interests in the claim.
Residential and Commercial Experience
Our experience includes residential homes, commercial properties, roof losses, water claims, fires, severe storms and complex losses involving multiple categories of damage.
Our team has reviewed thousands of property claims, giving us practical experience comparing carrier estimates with the documentation and scope required by real losses.
Texas-Focused Claim Experience
Texas properties face hail, tropical weather, windstorms, freezes, fires and water losses. Beach City’s Trinity Bay location adds another layer of local storm and water exposure.
Independent Scope Review
We do not work for your insurance company.
Our role is to evaluate the claim from the policyholder’s side and identify legitimate damage, omissions, estimating differences and documentation issues that deserve attention.
Free Claim Review
You can discuss your situation with TX Public Adjusting before deciding how to proceed.
There are no upfront fees for the initial claim review.
Areas We Serve Near Beach City
TX Public Adjusting assists property owners throughout Beach City and surrounding communities, including Cove, Mont Belvieu, Baytown, Old River-Winfree, and Anahuac, as well as other areas of Chambers County and the greater Houston-Galveston region.
Frequently Asked Questions About Public Adjusters in Beach City
What does a public adjuster in Beach City do?
A public adjuster represents the property owner during an insurance claim. That can include reviewing the policy and carrier estimate, inspecting damage, preparing documentation, developing a repair scope and negotiating disputed claim issues.
For Beach City property owners, that work is especially useful when storm damage involves both exterior and interior components or when there is disagreement about wind, water intrusion or roof repairs.
When should I hire a public adjuster after a Beach City storm?
You can contact a public adjuster early in the process or after receiving the insurance company’s estimate. Many property owners also want to know when it is too late to hire a public adjuster after a claim has already been inspected, paid, denied or partially settled.
Many property owners seek help when the loss is substantial, the claim becomes difficult to manage, the carrier misses damage, or the initial settlement appears too low. Waiting too long can create deadline and evidence issues, so earlier review is generally preferable when you already see a problem.
Can you help if my Beach City insurance claim has already been paid?
Potentially, yes.
A prior payment does not automatically mean every issue in the claim has been resolved. We can review the carrier estimate, payment documents and property damage to determine whether meaningful scope or valuation questions remain.
Can a public adjuster help with hurricane damage in Beach City?
Yes. Hurricane and tropical-storm claims are particularly relevant in Beach City because of its Chambers County and Trinity Bay location.
These claims can combine roof damage, exterior damage, wind-driven rain, water intrusion and contents losses. A public adjuster helps separate and document the different components of the loss.
What if the damage involves flooding?
The source of the water matters.
Rising surface water and water entering through storm-created damage can involve different policy provisions or policies. We review the available insurance documents and loss circumstances so the claim is presented according to the actual cause and applicable coverage.
Can you help with a denied Beach City property claim?
We can review a denied claim to understand the insurer’s stated reasoning, available evidence and policy language. If the loss involves hail, our guide explaining what to do if your hail claim was denied covers several of the issues property owners should review after receiving a denial.
A denial does not guarantee that it can be reversed, but an independent review can identify whether the carrier’s position deserves further documentation or challenge.
What if the insurance company’s roof estimate is lower than my contractor’s?
That is common, but the dollar difference alone does not establish which estimate is correct.
We compare quantities, repair methods, materials, labor and omitted components. The goal is to identify exactly why the estimates differ and document legitimate items the carrier may have missed.
Do you handle commercial claims around Beach City?
Yes.
TX Public Adjusting handles residential and commercial property claims. Commercial claims may involve building components, contents, inventory, equipment and other covered property, and they often require a more detailed scope and documentation process.
How much does it cost to have TX Public Adjusting review my claim?
The initial claim review is free, and there are no upfront fees for that review.
If representation makes sense, the public-adjusting agreement explains the services and applicable fee before work begins so you can make an informed decision.
Why choose TX Public Adjusting for a Beach City claim?
Beach City property owners need more than a generic statewide claims explanation. Trinity Bay exposure, tropical weather, waterfront construction and the mix of larger-lot and bayfront homes create local inspection issues that should be reflected in the claim.
TX Public Adjusting combines that locally focused approach with Texas public-adjusting experience through Rise Public Adjusting LLC, Texas License #3356839.
Get a Free Beach City Insurance Claim Review
If your Beach City home or commercial property has suffered hurricane, hail, wind, roof, water, fire or other covered property damage, you do not have to determine by yourself whether the insurance company’s estimate is complete.
TX Public Adjusting can review the documents, inspect the damage and help you understand where the claim stands.
Free Claim Review. No upfront fees. Residential and commercial claims.
Contact TX Public Adjusting today for a Free Claim Review and put a licensed Texas public adjuster on your side.