

Property damage in Old River-Winfree can become complicated quickly. This small Chambers County community sits in the upper Texas Gulf Coast region, where hurricanes, tropical storms, heavy rain, straight-line winds, hail, tornadoes, and flooding can all affect homes and commercial properties. If an insurance estimate does not reflect the damage you can see—or fails to account for damage you cannot easily see—a Public Adjuster in Old River-Winfree, TX can help document the loss and present the claim from the policyholder’s side.
TX Public Adjusting helps residential and commercial property owners evaluate damaged property, review insurance estimates, document missing items, and negotiate covered claims. TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839.
Free Claim Review | No Upfront Fees | Residential & Commercial Claims
If your Old River-Winfree property has suffered storm, roof, water, fire, hail, or other covered damage, contact TX Public Adjusting for a free review of your claim.
Old River-Winfree is located in northwestern Chambers County around the junction of FM 565 and FM 1409, roughly 35 miles east of Houston. The community takes its name partly from Old River, the waterway running through the area, and its history reaches back to early settlement along the river.
Why Property Owners Hire a Public Adjuster in Old River-Winfree
Insurance companies send adjusters to investigate claims, but those adjusters work within the insurer’s claim-handling process. A public adjuster represents the policyholder. If you are unsure about the difference, our public adjuster vs. independent adjuster guide explains who each type of adjuster represents during an insurance claim.
That distinction becomes especially important when a loss involves several components. A windstorm may begin with roof damage but also affect gutters, flashing, siding, fencing, exterior equipment, attic insulation, drywall, flooring, and personal property. An estimate that addresses only the most obvious damage can leave a large gap between what happened and what the insurance claim actually documents.
An Old River-Winfree public adjuster can help by:
- Reviewing the policy and available claim documents
- Inspecting residential or commercial property damage
- Photographing and documenting affected areas
- Comparing the insurer’s estimate with observed damage
- Identifying possible scope omissions
- Preparing supporting claim documentation
- Communicating with the insurance company
- Negotiating the claim on behalf of the policyholder
TX Public Adjusting has experience reviewing thousands of property claims involving residential and commercial losses across Texas. The objective is not simply to produce another estimate. It is to develop a defensible claim file that connects the physical damage, repair scope, documentation, and applicable policy provisions.
Property Damage Risks in Old River-Winfree
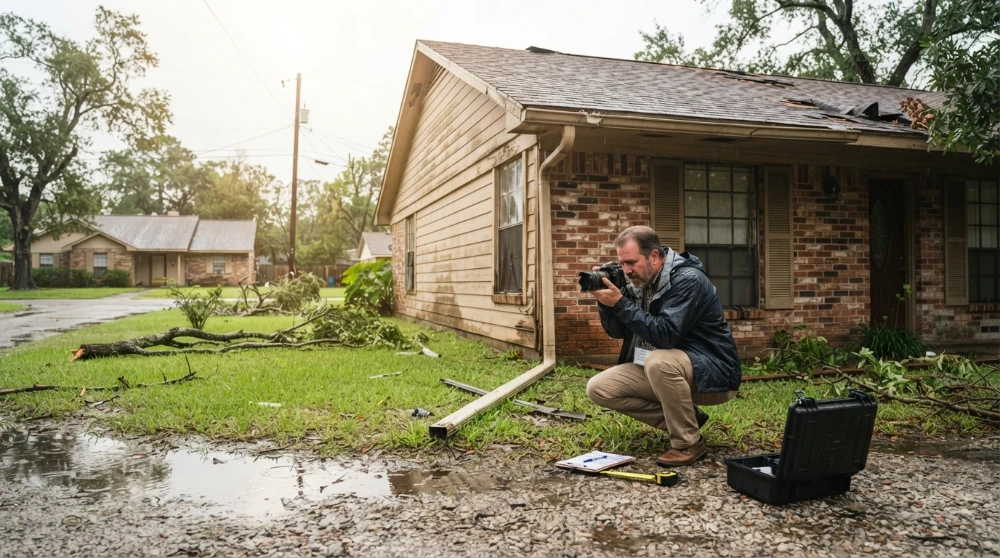
Old River-Winfree has a storm-risk profile that is distinctly tied to Chambers County and the upper Gulf Coast.
Chambers County identifies flooding, hurricanes, and tornadoes among its major hazards. The county notes that its coastal-plain geography, rivers, bayous, drainage patterns, and proximity to the Gulf leave it exposed to substantial rainfall and tropical weather. Hurricane Harvey produced extreme rainfall in the county, while other tropical systems including Rita, Ike, Imelda, Nicholas, Laura, and Beta have affected the wider Chambers County planning area.
Hurricanes and Tropical Storms
For Old River-Winfree property owners, tropical systems can produce more than one type of insurance loss at the same time.
Tropical systems can produce several categories of damage at the same property. Property owners dealing with a major loss can also review our guide to hurricane property damage in Texas before moving forward with their insurance claim.
- Lifted, creased, or missing shingles
- Wind damage to metal roofing and commercial roof systems
- Damaged flashing and roof penetrations
- Wind-driven rain entering through damaged building components
- Broken windows and doors
- Siding and exterior-envelope damage
- Fallen-tree or debris impact
- Interior ceiling and wall damage
- Damaged electrical or mechanical equipment
Hurricane Ike illustrates the seriousness of the region’s exposure. Federal reporting after Ike recorded extensive damage throughout Chambers County and specifically listed damage involving Old River-Winfree public facilities and infrastructure.
That history is one reason storm claims in this part of Texas deserve careful inspection rather than a quick roof-only review.
Heavy Rain and Water Damage
Old River-Winfree’s relationship with waterways is part of the community’s identity. The Old River itself helped shape early settlement, and the Texas Historical Commission maintains an Old River historical marker along FM 1409 north of FM 565.
That geography also makes water awareness especially relevant.
Chambers County warns property owners that flooding can originate from rivers, bayous, tributaries, drainage systems, tropical rainfall, and storm surge. The county specifically encourages residents to determine the flood risk of individual properties rather than assuming a property is safe because it is outside a familiar high-risk area.
There is an important insurance distinction here: flood damage and covered water damage are not automatically the same thing. Standard property policies commonly treat rising surface water differently from losses caused by a burst pipe, roof opening, plumbing failure, or another covered cause. Coverage always depends on the actual policy and cause of loss.
A public adjuster can help examine how the loss occurred and what documentation the insurance carrier needs.
Wind, Hail, and Severe Thunderstorms
A Gulf Coast property does not need a named hurricane to suffer significant roof or exterior damage.
Strong thunderstorms can produce:
- Hail impacts to shingles and metal
- Wind-lifted roofing
- Damaged ridge caps
- Bent gutters and downspouts
- Fence damage
- Window-screen and glazing damage
- Siding impacts
- Tree and limb damage
- Water intrusion after roof or wall openings
Texas Department of Insurance windstorm information places the Winfree community within Chambers County’s designated windstorm geography, reinforcing the importance of wind-resistant construction and careful inspection after storms.
Tornado and Straight-Line Wind Damage
Chambers County also identifies tornadoes as a recurring hazard and reports multiple documented tornadic events in the county. Even lower-rated tornadoes and severe straight-line winds can tear roofing materials loose, damage outbuildings, topple trees, and create openings that allow rain into a structure.
For a property owner, the claim question becomes: Did the estimate capture the entire chain of resulting damage?
That is where detailed documentation matters.
Common Insurance Claims in Old River-Winfree
Hail Damage Claims
Hail damage is not always obvious from the driveway. Shingle bruising, fractured mats, displaced granules, dented soft metals, damaged vents, and impacts to commercial roof components may require a closer inspection. Our guide to hail damage roof insurance claims explains what Texas property owners should look for after a storm.
A hail claim should also look beyond shingles. Depending on the storm, damage may affect:
- Gutters
- Downspouts
- Roof vents
- Flashing
- HVAC fins
- Window screens
- Siding
- Fencing
- Exterior lighting and fixtures
Documentation can become especially important when the damage is disputed or difficult to see. Property owners can follow our guide on how to document hail damage for an insurance claim for practical steps involving photos, damaged components, and claim records. If an Old River-Winfree hail claim was denied or the estimate covers only isolated repairs, TX Public Adjusting can review the available scope and supporting evidence.
Water Damage Claims
Covered water losses can come from burst pipes, plumbing failures, appliance leaks, roof openings, and other sources. A water damage public adjuster can help evaluate whether the carrier’s scope accounts for the resulting damage throughout the property.
A proper water-damage scope may need to consider:
- Wet drywall
- Insulation
- Flooring
- Cabinetry
- Baseboards and trim
- Moisture trapped behind walls
- Contents damage
- Mitigation work
- Related painting and finishing
- Access required to reach damaged components
One common problem is an estimate that acknowledges the source of the leak but does not fully address everything damaged afterward.
Fire Damage Claims
Fire claims are rarely limited to the area where flames were visible. A fire insurance adjuster working for the policyholder can help document structural damage together with smoke, soot, contents, and related components of the loss.
Smoke, soot, heat, water used in suppression, damaged contents, debris removal, electrical systems, and odor contamination may all need evaluation. Larger losses can also involve temporary living expenses or business interruption considerations, depending on the policy.
TX Public Adjusting helps Old River-Winfree policyholders organize these complicated claims so that structure, contents, and related damages are documented together rather than treated as disconnected problems.
Storm Damage Claims
In Old River-Winfree, storm claims deserve particular attention because one weather event may cause wind, roof, exterior, interior, and water damage.
For example, high winds can damage the roof covering. The resulting opening may allow rain into the attic. Water can then affect insulation, ceilings, walls, flooring, and electrical components.
If the insurance estimate stops at replacing a handful of shingles, significant resulting damage can remain outside the carrier’s initial scope.
Roof Damage Claims
Roof claims are among the most common property claims we review. Property owners dealing with a disputed or underpaid loss can learn more about working with a public adjuster for a roof claim before accepting the carrier’s initial scope.
Potential issues include:
- Missing or lifted shingles
- Hail impacts
- Metal-roof damage
- Flashing damage
- Damaged penetrations and vents
- Wind-created openings
- Interior leaks
- Insufficient repair scopes
- Omitted accessories or associated materials
Properties along the FM 565 corridor, FM 1409 corridor, the Old River side of the community, and the traditional Winfree area may differ in age, construction, roof type, and surrounding vegetation. Old River-Winfree does not have the extensive named-neighborhood structure of a large metro, so local property references are often tied more naturally to these roads, waterways, and historic community sections.
Commercial Property Claims
The western Chambers County area has long been influenced by nearby industrial and petrochemical development around Mont Belvieu. The region also includes retail, warehouse, agricultural, church, office, and other commercial properties. The Handbook of Texas notes that industrial growth in southwestern Chambers County was an important factor in Old River-Winfree’s development and incorporation.
Commercial property insurance claims can become particularly technical because they may involve multiple building components, equipment, inventory, and business-related coverage considerations.
- Low-slope or metal roofing systems
- Large exterior elevations
- Mechanical equipment
- Inventory
- Interior buildouts
- Tenant improvements
- Business personal property
- Code-related repairs
- Business interruption provisions, when applicable
TX Public Adjusting works with both residential and commercial policyholders, including businesses dealing with warehouse property damage claims and other large commercial losses.
Have an underpaid or complicated Old River-Winfree claim? Request a Free Claim Review from TX Public Adjusting. There are no upfront fees.
Why Insurance Claims Become Underpaid
A low estimate does not always result from one major mistake. More often, several smaller omissions add up.
Missed Damage
A short inspection can overlook roof accessories, adjacent elevations, interior moisture, detached structures, mechanical equipment, or less-visible damage.
Scope Omissions
The insurer may acknowledge that something is damaged while leaving necessary related work out of the estimate.
Replacing one component can require removal, access, matching, finishing, or reconstruction of another component. The claim scope should tell the complete repair story.
Depreciation Issues
Property estimates may include depreciation depending on the policy, age and condition of materials, and the type of coverage involved.
Confusion often occurs when policyholders do not understand what has been depreciated, what may be recoverable, or what documentation is needed after repairs.
Low Repair Estimates
Carrier estimates and contractor pricing can differ considerably.
The important question is not simply which total is higher. Each line item, quantity, repair method, material, labor component, and necessary associated cost should be evaluated.
Documentation Problems
Insurance claims are evidence-driven.
Photographs without context, incomplete inventories, missing contractor documents, unclear dates, and poorly organized correspondence can weaken an otherwise legitimate claim. A public adjuster helps assemble the documentation into a coherent file.
Our Public Adjusting Process
1. Claim Review
We start by reviewing the circumstances of the loss, the claim status, available estimates, photographs, correspondence, and relevant policy information.
If you have already received an insurance payment, denial, or estimate, bring it to the review.
2. Property Inspection
We inspect the affected property and compare the physical conditions with what has already been included in the insurance company’s scope.
For an Old River-Winfree storm loss, that can mean reviewing the roof, elevations, exterior metals, interior spaces, detached structures, and other storm-sensitive components.
3. Documentation
We organize evidence supporting the claim.
Depending on the loss, documentation can include:
- Detailed photographs
- Measurements
- Damage notes
- Repair estimates
- Contents information
- Contractor documentation
- Mitigation records
- Supporting claim correspondence
4. Claim Presentation and Negotiation
We communicate with the carrier from the policyholder’s side and explain documented differences in the scope or estimate.
The goal is to keep negotiations focused on evidence, repair requirements, and the policy rather than unsupported assumptions.
5. Settlement and Claim Resolution
When the carrier responds, we review changes, requests, and settlement documentation with the policyholder.
Every claim is different, and no particular claim outcome can be guaranteed. Our role is to build and advocate for a properly documented claim based on the loss and applicable coverage.
Local Claim Experience Matters in Chambers County
A city page for Old River-Winfree should not read like a page for Dallas or Austin because the property risks are different.
Old River-Winfree sits at the FM 565 and FM 1409 crossroads, where the historic Old River community and Winfree area developed along waterways and agricultural land before the surrounding region became increasingly connected to Mont Belvieu and the petrochemical economy.
Local reference points include the Old River waterway, the Texas Historical Commission Old River marker, the FM 565/FM 1409 junction, and, just outside the city, the larger Barbers Hill community and school facilities in neighboring Mont Belvieu. Barbers Hill ISD itself serves Old River-Winfree along with Mont Belvieu, Cove, and Beach City.
These details matter because Old River-Winfree combines a small-town residential environment with Gulf Coast storm exposure and proximity to a major commercial and industrial corridor.
Why Choose TX Public Adjusting
Property owners hire TX Public Adjusting because they want someone focused on their side of the insurance claim.
Licensed Texas Public Adjuster
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839.
Independent Policyholder Representation
We represent policyholders—not insurance companies.
Our job is to examine the loss from the property owner’s perspective and document covered damage as thoroughly as possible.
Texas-Focused Experience
Texas weather creates distinctive claim problems. Hail, severe thunderstorms, hurricanes, wind, burst pipes, fires, and large commercial losses require different inspection and documentation approaches.
Residential and Commercial Experience
Our experience includes thousands of claims reviewed across residential and commercial property types.
That includes homeowners as well as owners and operators of warehouses, retail properties, offices, churches, multifamily properties, restaurants, and other business facilities.
Detailed Claim Documentation
Good negotiation begins with good evidence.
We focus on documenting the property, evaluating the carrier’s scope, and identifying differences that can be supported rather than simply demanding a larger number.
Areas We Serve Near Old River-Winfree
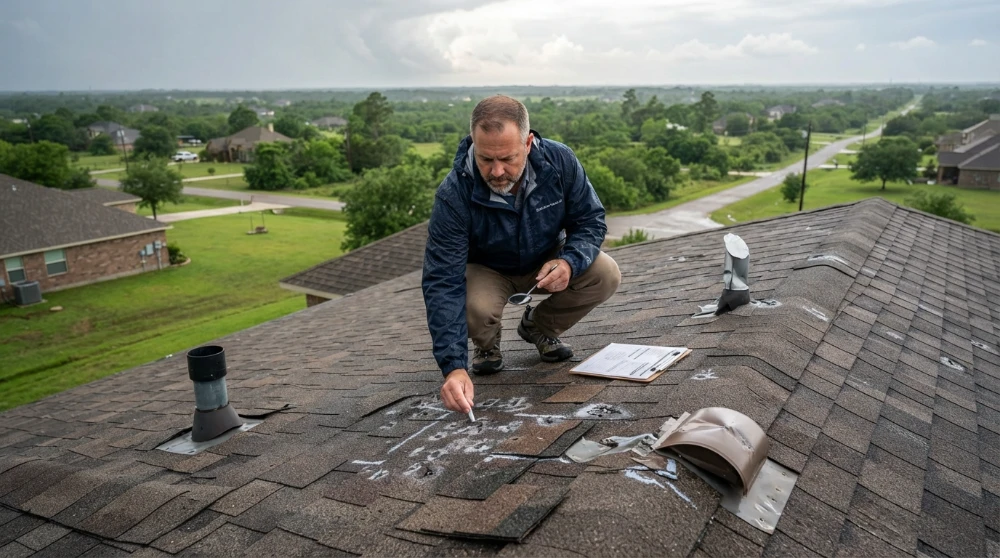
TX Public Adjusting serves Old River-Winfree and surrounding Chambers County and east-Houston-area communities.
Nearby service areas include:
- Mont Belvieu
- Cove
- Beach City
- Anahuac
- Baytown
- Dayton
- Wallisville
- Highlands
- Barrett
- Sheldon
Mont Belvieu, Cove, Beach City, and Old River-Winfree also share strong regional ties through Barbers Hill ISD, which covers these four Chambers County communities.
Frequently Asked Questions About Public Adjusters in Old River-Winfree
What does a public adjuster in Old River-Winfree do?
A public adjuster represents the policyholder during a property insurance claim. That can include inspecting damage, reviewing the insurer’s estimate, organizing documentation, identifying omitted items, communicating with the carrier, and negotiating disputed claim amounts.
TX Public Adjusting works for the property owner rather than the insurance company.
When should I call a public adjuster after a storm in Old River-Winfree?
You can contact a public adjuster before the claim becomes disputed, but many property owners call after receiving an estimate that appears too low, experiencing delays, receiving a denial, or discovering damage that was not included in the first inspection.
After a major Chambers County storm, calling early can also help preserve photographs and other evidence before repairs change the condition of the property.
Can you help with a hurricane damage claim in Old River-Winfree?
Yes. Hurricane and tropical-storm claims may involve roofing, siding, wind-created openings, interior water intrusion, fencing, windows, detached structures, and commercial equipment.
Because Chambers County has a documented history of tropical-cyclone impacts, hurricane-related property damage is a particularly relevant claim type for Old River-Winfree property owners.
Can a public adjuster help if my roof claim was underpaid?
Yes. We can compare the carrier estimate with the observed roof and related property damage.
An underpaid roof claim may involve omitted roofing components, underestimated quantities, missed exterior damage, or interior water damage that resulted from the same storm.
Does homeowners insurance cover flooding in Old River-Winfree?
A typical homeowners property policy generally does not cover rising-water flooding in the same way that a separate flood policy may. Coverage depends on your actual contracts and the cause of the water damage.
This distinction matters in Chambers County because the county specifically identifies flooding as one of its leading hazards and encourages residents to review their individual flood risk and coverage.
What if the insurance company already paid my claim?
Receiving an initial payment does not necessarily mean every legitimate claim issue has been resolved.
If you believe damage or necessary repair work was omitted, TX Public Adjusting can review the estimate, supporting documentation, and claim history to determine what issues may still warrant further evaluation, subject to the policy and applicable deadlines.
Can you help with commercial property damage near Old River-Winfree?
Yes. We handle residential and commercial claims.
The Old River-Winfree and Mont Belvieu area includes residential properties alongside a broader industrial and commercial economy, so claims may involve warehouses, offices, retail buildings, churches, multifamily properties, restaurants, and other business facilities.
How much does it cost to hire TX Public Adjusting?
We offer a Free Claim Review and no upfront fees.
If representation makes sense for your situation, the fee arrangement is explained before you enter into a public-adjusting agreement so you can understand the terms before moving forward.
Is it too late to hire a public adjuster after my claim has been denied?
Not necessarily. A denial does not automatically mean that a public adjuster can change the result, but it may still be worthwhile to have the claim documents, cause of loss, policy issues, and available evidence reviewed. For a more detailed explanation of claim timing, read our guide answering when is it too late to hire a public adjuster.
Deadlines and contractual rights can matter, so it is usually better to have a disputed claim evaluated sooner rather than later.
Why hire a local Texas public adjuster instead of handling the claim myself?
Property owners can handle their own claims, but larger losses require time, documentation, estimating knowledge, and repeated communication with the insurer.
A licensed Texas public adjuster can manage much of that work while representing the policyholder’s interests. For Old River-Winfree property owners dealing with Gulf Coast wind, hurricane, hail, roof, water, fire, or commercial damage, that added claim experience can be particularly useful.
Get a Free Old River-Winfree Insurance Claim Review
If your home or business in Old River-Winfree has been damaged, you do not have to rely solely on the insurance company’s first inspection or estimate.
TX Public Adjusting can review your claim, inspect the damage, identify potential scope issues, prepare supporting documentation, and negotiate from the policyholder’s side.
TX Public Adjusting
Rise Public Adjusting LLC
Texas License #3356839
Free Claim Review
No Upfront Fees
Residential & Commercial Claims
Contact TX Public Adjusting today for insurance claim assistance in Old River-Winfree, Chambers County, Texas.