

Property damage in West Columbia can become complicated quickly. A Gulf storm can damage the roof and allow wind-driven rain inside. A severe thunderstorm can leave hail impacts across shingles, vents, gutters, and metal components. Heavy rainfall can overwhelm drainage and create water problems throughout a property. For homeowners and businesses in Brazoria County, the damage itself is only part of the problem—the insurance claim has to accurately account for everything that was affected.
TX Public Adjusting provides public adjuster services in West Columbia, TX for residential and commercial property owners dealing with damaged, delayed, denied, or underpaid insurance claims. Rise Public Adjusting LLC, Texas License #3356839, represents policyholders—not insurance companies. Texas regulators likewise define a public insurance adjuster as a licensed professional hired by the policyholder to negotiate a claim.
West Columbia has a different property-risk profile from North Texas or the Hill Country. The city sits in Brazoria County, near the Brazos River and within the broader Texas Gulf Coast storm environment. Hurricane preparation is taken seriously enough that the City of West Columbia publishes Brazoria County evacuation guidance for major storms.
If your carrier’s estimate does not seem to match the damage you can see—or you suspect damage was missed—request a Free Claim Review from TX Public Adjusting before accepting the claim at face value. There are no upfront fees.
Why Property Owners Hire a Public Adjuster in West Columbia
West Columbia may be a smaller community, but property claims here can involve the same expensive disputes found in larger Gulf Coast cities.
The difference is local exposure.
Brazoria County is one of the Texas coastal counties included in the state’s designated catastrophe-area framework for windstorm purposes. Depending on the property and policy, wind and hail coverage may also involve different insurance arrangements than a standard homeowners policy.
For a West Columbia property owner, one storm may produce several categories of loss at once:
- Lifted, creased, or missing shingles
- Damaged flashing, vents, gutters, and roof accessories
- Wind-driven rain entering attic or wall assemblies
- Wet insulation and drywall
- Ceiling and flooring damage
- Broken windows or damaged exterior components
- Fallen-tree or debris impacts
- Damage to detached structures
- Business equipment or inventory losses
- Interior moisture that is not obvious during the first inspection
A carrier inspection may be brief, particularly after a widespread storm when adjusters are handling many losses. The resulting estimate can look detailed while still leaving out affected materials, labor operations, code-related items, or portions of the property that were never documented.
A public adjuster in West Columbia works from the policyholder’s side of the claim. Our role is to evaluate the loss, document the damage, review the carrier’s scope, prepare supporting estimates and evidence, communicate with the insurance company, and negotiate the claim under the applicable policy.
West Columbia Storm Risks and Property Damage
West Columbia’s location creates a mix of hurricane, tropical storm, wind, rain, flooding, lightning, and thunderstorm exposure that deserves more than a generic Texas storm paragraph.
Hurricanes and Tropical Storms
Hurricane Beryl demonstrated how quickly Gulf weather can affect communities across Southeast Texas. Beryl made landfall near Matagorda on July 8, 2024, as a Category 1 hurricane before crossing Southeast Texas.
West Columbia sits inland from the immediate coastline, but that does not eliminate hurricane-related property risk. Strong winds can damage roofs well inland, while wind-driven rain can exploit openings around shingles, flashing, windows, doors, vents, and exterior cladding.
After a tropical system, the visible damage is sometimes only the beginning. Property owners dealing with Texas hurricane property damage may discover roof openings, moisture intrusion, damaged exterior components, and interior problems well after the storm has passed.
Heavy Rain and Flooding
Water is an especially important issue in West Columbia.
The community lies near the Brazos River, and NOAA storm records document historic flooding on the Brazos extending to areas below West Columbia. In January 2024, heavy rain also flooded roads and sent water into several homes in West Columbia.
Coverage depends heavily on the source of the water. Texas Department of Insurance guidance states that most homeowners policies do not cover flood damage from rising water, while sudden and accidental interior water losses such as some burst-pipe events may be covered depending on the policy.
That distinction matters after a storm. Rain entering through storm-created roof damage can present a very different coverage question from rising surface water entering a structure.
Wind and Hail
Thunderstorms can produce damaging wind and hail even when there is no named hurricane.
Roof claims may involve bruised shingles, granule displacement, damaged ridge materials, dented soft metals, cracked vents, damaged gutters, siding impacts, or other exterior damage. On commercial properties, metal panels, rooftop equipment, membranes, flashing systems, and exterior components may all require review.
The most important question is not simply whether a storm occurred. It is whether the resulting damage was accurately identified, connected to the loss, and included in the insurance estimate.
Common Insurance Claims in West Columbia
Hail Damage Claims
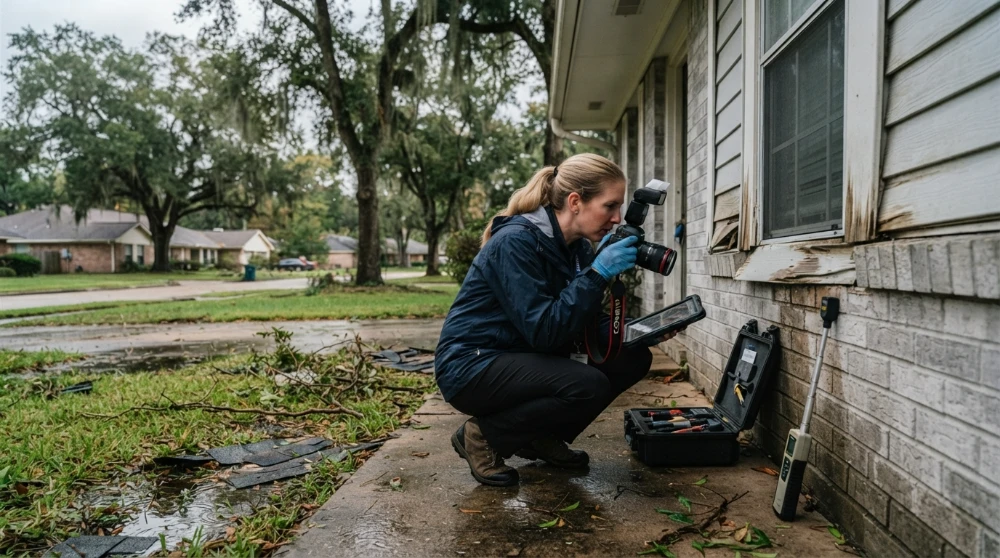
Hail damage is easy to underestimate because many impacts are difficult to identify from ground level. Our hail damage roof insurance claim guide explains how roof impacts can affect different roofing materials and what property owners should look for after a severe storm.
TX Public Adjusting reviews hail claims for damage involving:
- Asphalt shingles
- Metal roofing
- Roof vents and flashing
- Gutters and downspouts
- Exterior siding
- Windows and screens
- HVAC components
- Commercial roofing systems
Property owners who are gathering evidence can also review how to document hail damage for an insurance claim before repairs begin. If the carrier has already rejected the loss, see what to do if your hail claim was denied for additional claim considerations. If your carrier inspected the property but the payment does not appear to address the complete damage, a second review may reveal scope differences that deserve attention.
Water Damage Claims
Water claims can spread far beyond the original source. A water damage public adjuster can review the carrier’s scope when covered water damage affects multiple materials, rooms, or concealed areas of the property.
A pipe failure, roof opening, appliance leak, or wind-driven rain event can affect drywall, insulation, flooring, cabinets, electrical components, contents, and concealed cavities.
The insurance estimate should account for the actual extent of the covered loss—not simply the first wet area that was visible.
Fire Damage Claims
Fire claims often involve several interconnected categories. For larger smoke, soot, and structural losses, a fire insurance adjuster working for the policyholder can help document how damage extends beyond the immediate burn area.
- Structural fire damage
- Smoke and soot
- Contents
- Odor remediation
- Demolition and debris removal
- Electrical components
- Temporary living arrangements when covered
- Rebuilding costs
A fire may be contained to one room while smoke travels throughout much more of the building. Proper documentation should reflect that broader impact where supported by the loss.
Storm Damage Claims
West Columbia storm claims may combine roof damage, wind, water intrusion, broken exterior materials, fallen debris, and contents damage.
That makes causation and documentation especially important. The claim should distinguish what happened during the covered storm from unrelated maintenance or pre-existing conditions.
Roof Damage Claims
Roof claims are among the most disputed property claims because roof condition, age, cause of damage, repairability, depreciation, matching, and the extent of required work can all affect the carrier’s estimate. Property owners facing a significant disagreement can learn more about working with a public adjuster for a roof claim before accepting an incomplete scope.
We compare the insurance scope against the observed damage and supporting property information to identify omissions or inconsistencies.
Commercial Property Claims
West Columbia and the surrounding Brazoria County area include retail properties, restaurants, offices, agricultural operations, warehouses, churches, multifamily properties, industrial-related facilities, and other businesses.
Commercial claims may involve much more than the building itself. A commercial public adjuster can assist with documentation involving the building, equipment, inventory, tenant improvements, business personal property, mitigation costs, and other covered portions of a commercial loss.
If a West Columbia commercial claim is substantial or the carrier’s scope does not reflect the full damage, contact TX Public Adjusting for a Free Claim Review.
Why West Columbia Insurance Claims Become Underpaid
An underpaid claim does not always begin with an obvious denial. Sometimes the carrier accepts the loss but writes a scope that is simply incomplete.
Missed Damage
The adjuster may inspect the roof but not fully document interior moisture. Exterior components may be missed. Secondary rooms may never appear in the estimate.
Small omissions can add up quickly.
Scope Omissions
Insurance estimates are built line by line. If a necessary operation is absent, its cost is absent too.
Common disagreements can involve demolition, removal, disposal, access, material replacement, flashing, underlayment, insulation, painting, contents handling, or other work required to complete repairs.
Depreciation Issues
Replacement-cost and actual-cash-value calculations can be confusing. Depreciation may substantially affect an initial payment, and policy requirements can determine when recoverable depreciation becomes available.
We review how the carrier applied these calculations and whether they correspond with the policy and documented loss.
Low Repair Estimates
A carrier’s estimate and a contractor’s repair proposal may not match.
The important step is determining why. Quantities may differ. Materials may differ. Labor operations may be missing. The insurer may have assumed a repair where replacement is being proposed.
A public adjuster’s job is to identify and document those differences rather than simply argue that one number should be higher.
Documentation Problems
Insurance companies make decisions based on the claim file.
Photos, measurements, inventories, invoices, estimates, mitigation records, expert findings, correspondence, and policy information can all affect how a loss is evaluated.
Weak documentation leaves room for damage to be overlooked.
Our Public Adjusting Process
Our West Columbia claim process is built around evidence and clear communication.
1. Claim Review
We begin by reviewing what happened, the status of the claim, available policy information, the carrier estimate, payments, correspondence, and any denial or coverage letters.
The goal is to identify where the claim currently stands before determining the best next step.
2. Property Inspection
We inspect the affected property and compare actual conditions with the carrier’s documented scope.
For a storm claim, that might include the roof, exterior elevations, interior rooms, detached structures, and affected commercial components.
3. Documentation and Scope Preparation
We organize supporting evidence and prepare a detailed claim position.
Depending on the loss, documentation may include:
- Damage photographs
- Measurements
- Estimates
- Contents information
- Repair documentation
- Contractor information
- Mitigation records
- Supporting reports
4. Insurance Company Negotiation
TX Public Adjusting communicates with the carrier on the policyholder’s behalf and presents documented differences in the claim.
The focus is not on inflating the loss. It is on making sure covered damage is properly identified, supported, and evaluated.
5. Settlement Review
As the carrier responds, we review revisions, supplemental estimates, payments, depreciation, and outstanding items.
The process continues until the claim reaches an appropriate resolution under the policy or requires another available dispute-resolution path.
Local Claim Help Across West Columbia
West Columbia’s residential character varies from established homes near the historic center to larger subdivisions and properties on the outskirts of town.
Local subdivisions and residential areas include Columbia Lakes, Wildwood, Pecan Oaks, Lincoln Heights, Green Meadow, Crocker Heights, and Columbia City Outlots.
The area also has a distinctive historic identity. West Columbia is tied closely to the early Republic of Texas, and local landmarks include the Columbia Historical Museum and Rosenwald School, 1836 Pocket Park, and the Varner-Hogg Plantation State Historic Site.
Those historic references matter because they reflect what West Columbia actually is: an established Brazoria County community with older homes, newer subdivisions, commercial properties, rural acreage, and structures built across very different construction eras.
Claims on an older home near the historic core can require a different repair analysis than a newer residence in Columbia Lakes or a commercial building along a primary local corridor.
Why Choose TX Public Adjusting in West Columbia?
Licensed Texas Public Adjuster
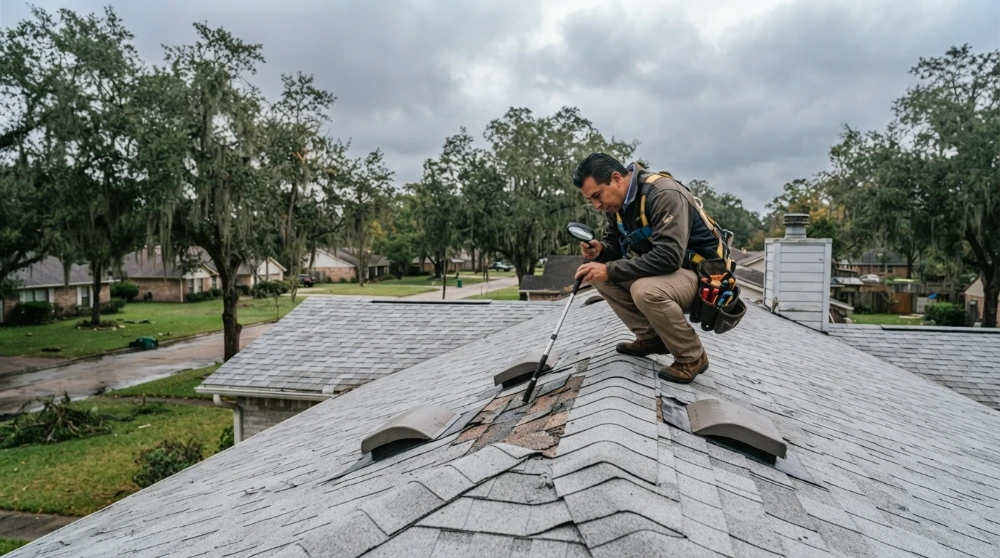
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839. Our company website identifies the same legal entity and license information.
We Represent Policyholders
An insurance company adjuster or independent adjuster working for the carrier has a different role from the professional hired by the property owner. Our guide to public adjuster vs. independent adjuster explains that distinction in more detail.
A public adjuster is hired by the policyholder. TX Public Adjusting represents the insured’s interests during the property claim—not the insurance company’s.
Texas-Focused Claims Experience
Our work centers on Texas property claims, including the types of losses Texas owners regularly face:
- Hail
- Wind
- Hurricanes
- Water
- Fire and smoke
- Roof damage
- Commercial losses
Residential and Commercial Expertise
We work with homeowners as well as business owners, landlords, property managers, investors, and commercial property owners.
Our experience includes thousands of Texas claim reviews across residential and commercial losses.
Free Claim Review and No Upfront Fees
You do not have to guess whether your claim deserves another look.
TX Public Adjusting offers a Free Claim Review with no upfront fees.
Areas We Serve Near West Columbia
We also assist property owners throughout Brazoria County and surrounding communities. For nearby claim assistance, visit our pages for Public Adjuster Angleton, TX, Public Adjuster Lake Jackson, TX, Public Adjuster Sweeny, TX, and Public Adjuster Brazoria, TX. We also serve property owners looking for claim assistance in Clute and Freeport.
Nearby areas include:
- Brazoria
- Sweeny
- Angleton
- Lake Jackson
- Clute
- Freeport
- Alvin
- Pearland
- Bay City
- Other communities throughout Brazoria County and Southeast Texas
This local cluster is already represented throughout the TX Public Adjusting area-page structure, including Angleton, Lake Jackson, Clute, Freeport, Alvin, Bay City, and other nearby communities.
Frequently Asked Questions About Public Adjusters in West Columbia
1. What does a public adjuster in West Columbia do?
A public adjuster represents the property owner during an insurance claim. We inspect the damage, review the policy and carrier estimate, prepare documentation, identify missing claim items, and negotiate with the insurance company.
Unlike the carrier’s adjuster, our responsibility is to the policyholder.
2. When should I hire a public adjuster after property damage?
Consider a public adjuster when the loss is substantial, complicated, underpaid, delayed, partially denied, or difficult to document.
You can also request a review before accepting the carrier’s estimate if you are unsure whether it includes the full scope of damage.
3. Can you help with hurricane damage in West Columbia?
Yes. Hurricane and tropical-storm claims can involve roof damage, wind, exterior components, water intrusion, contents, and commercial losses.
Because Brazoria County is part of Texas’s coastal catastrophe-area framework, property owners should also verify which policy provides their wind and hail coverage.
4. Can you help if my West Columbia roof claim was underpaid?
Yes. We can compare the carrier’s roof estimate with the observed damage, measurements, materials, repair requirements, and supporting documentation.
An underpaid roof claim may involve omitted components, disputed storm damage, depreciation issues, or differences in the necessary repair scope.
5. Is flood damage covered by homeowners insurance in West Columbia?
Usually not under a standard Texas homeowners policy. The Texas Department of Insurance states that most home policies do not cover flood damage, so separate flood insurance may be necessary.
However, not every water loss is a flood. A burst pipe or storm-created roof opening may involve different coverage. The cause of the water should be carefully documented.
6. Can a public adjuster help after my insurance company already paid me?
Potentially. Receiving an initial payment does not automatically mean every issue has been resolved.
We can review the estimate, scope, documentation, and claim status to determine whether covered damage appears to have been omitted and whether the policy still provides a path to address it.
7. How much does a public adjuster cost in Texas?
Texas public adjuster fees are regulated. The Texas Department of Insurance states that a public adjuster’s fee may not exceed 10% of the claim settlement, and the fee must be disclosed in the written contract.
TX Public Adjusting offers a free initial claim review and no upfront fees.
8. Do I need a public adjuster for a small insurance claim?
Not every claim requires professional representation.
If the damage is minor, the carrier’s estimate is complete, and you are comfortable handling the documentation yourself, hiring a public adjuster might not be necessary. Our free review can help you determine whether there are meaningful issues worth addressing before you decide.
9. Can you help with commercial property claims in West Columbia?
Yes. TX Public Adjusting handles residential and commercial claims.
Commercial losses can require additional documentation for roofing systems, equipment, inventory, tenant improvements, mitigation costs, and other covered property. Large commercial losses particularly benefit from organized documentation and a detailed scope.
10. Is it too late to hire a public adjuster if my claim is already open?
Not necessarily. Public adjusters are often hired after the policyholder receives a low estimate, encounters a disagreement, or realizes the claim has stalled.
The important issue is the status of your claim, applicable policy requirements, and any deadlines. The sooner those issues are reviewed, the more options you may have available. For a more detailed explanation of deadlines and different stages of an insurance claim, read when it may be too late to hire a public adjuster.
Get a Free Claim Review in West Columbia
A property claim should reflect the damage that actually occurred.
If your West Columbia home, rental property, commercial building, or business has suffered roof, hail, water, wind, hurricane, fire, storm, or other covered property damage, TX Public Adjusting can review what the insurance company has documented and help identify whether something important was missed.
TX Public Adjusting
Rise Public Adjusting LLC
Texas License #3356839
- Free Claim Review
- No Upfront Fees
- Licensed Texas Public Adjuster
- Residential & Commercial Claims
- Independent Representation for Policyholders
Contact TX Public Adjusting today to request your Free Claim Review in West Columbia, TX.