

Property damage in Morgan’s Point can become complicated quickly. This small Harris County community sits where Galveston Bay meets the Houston Ship Channel, putting homes and commercial properties in an environment shaped by tropical storms, hurricane winds, wind-driven rain, coastal water, severe thunderstorms, and intense Gulf Coast humidity. If your insurer has underpaid a loss, omitted damaged property from its estimate, or left you uncertain about what your policy should cover, a public adjuster in Morgan’s Point can represent your interests throughout the claim.
TX Public Adjusting helps residential and commercial policyholders document property damage, review insurance estimates, identify missing scope items, and negotiate covered claims. We are operated by Rise Public Adjusting LLC, Texas License #3356839, and our responsibility is to the policyholder—not the insurance company.
If you have an open, delayed, denied, or underpaid property claim in Morgan’s Point, contact TX Public Adjusting for a Free Claim Review. There are no upfront fees.
Morgan’s Point is unlike most Houston-area communities. The city occupies a waterfront location approximately 30 miles east of Houston and is directly adjacent to Galveston Bay and the Houston Ship Channel. The city also contains the Morgan’s Point National Historic District and Port Houston’s Barbours Cut container terminal. Those characteristics create a distinctive mix of historic residences, waterfront properties, newer homes, and major commercial and industrial property exposures.
Why Property Owners Hire a Public Adjuster in Morgan’s Point
After property damage, an insurance company typically sends its own adjuster or claims representative to investigate the loss. That person works within the insurer’s claims process.
A public adjuster works differently. Understanding the difference between a public adjuster vs. independent adjuster can help explain who each professional represents during the claim process.
A licensed public adjuster represents you, the policyholder, in connection with the property insurance claim. Our job is to examine the loss from your side of the claim and determine whether the damage has been properly identified, documented, scoped, and valued under the applicable policy.
Property owners in Morgan’s Point may seek public adjusting assistance when:
- An insurance estimate appears too low to complete necessary repairs
- A carrier recognizes roof damage but omits related exterior or interior damage
- Wind-driven rain has affected several parts of a building
- The insurer applies depreciation that needs closer review
- Multiple trades are required to restore the property
- Water damage extends beyond the visibly wet area
- A commercial loss involves inventory, equipment, finishes, or business operations
- The adjuster’s scope does not match contractor findings
- A supplemental claim has become difficult to document
- The claim has stalled or communication has become confusing
- A denied claim deserves a closer review of the policy and evidence
A Morgan’s Point insurance claim can involve more than the obvious damaged component. A storm that affects roofing, for example, may also affect flashing, gutters, siding, windows, fencing, exterior fixtures, insulation, ceilings, interior finishes, and personal property.
Our role is to build a clear record of the covered loss so the claim can be evaluated using a complete scope rather than a rushed inspection.
Morgan’s Point Property Claims Require Gulf Coast Experience

Morgan’s Point sits at a particularly exposed point along the Upper Texas Coast. The city describes itself as being adjacent to Galveston Bay at the inlet to the Houston Ship Channel. For property owners, that geography matters.
Hurricanes and Tropical Storms
Hurricanes do not have to make a direct landfall at Morgan’s Point to cause a substantial property loss.
Outer bands can produce:
- High winds
- Wind-driven rain
- Roof uplift
- Damaged shingles and metal roofing components
- Broken or leaking windows
- Siding and fascia damage
- Falling trees and limbs
- Power-related damage
- Interior water intrusion
Hurricane Beryl demonstrated the area’s exposure in July 2024. National Weather Service data recorded a maximum water level of 5.54 feet above mean higher high water at Morgan’s Point, while Harris County experienced widespread wind and power-line damage. Morgan’s Point property owners affected by similar storms can also review our guide to the claims process after Hurricane Beryl for additional information about documenting and presenting a storm loss.
That is precisely why a storm claim here should be evaluated as a building-wide event rather than reduced automatically to a few obvious roof repairs. After major property damage after a hurricane, the claim should account for all affected building components rather than only the most obvious roof damage.
Storm Surge and Coastal Water
Morgan’s Point also has a claim risk that many inland Harris County communities do not share: direct proximity to Galveston Bay and the Houston Ship Channel.
During Hurricane Harvey, the National Weather Service recorded a 3.88-foot storm surge at the Morgan’s Point gauge. Tropical Storm Imelda also produced an elevated water level at Morgan’s Point.
Coverage involving rising surface water or storm surge can differ significantly from coverage for rain entering through storm-created openings. Policy language, exclusions, deductibles, and the actual path of water all matter.
A public adjuster cannot create coverage that a policy does not provide. What we can do is carefully document the physical damage, review the policy, identify the reported cause of loss, and make sure covered damage is not casually grouped with excluded damage without proper investigation.
Severe Thunderstorm and Wind Damage
Tropical systems are not the only wind threat.
Strong Gulf Coast thunderstorms can produce damaging straight-line winds, lightning, intense rain, and occasionally hail. In July 2026, the National Weather Service reported a 68 mph marine thunderstorm wind gust two miles east of Morgan’s Point, illustrating how powerful localized storms can become around the bay and Ship Channel.
A short storm can still damage:
- Shingles
- Roof membranes
- Flashing
- Metal panels
- HVAC equipment
- Fences
- Exterior cladding
- Windows and screens
- Detached structures
Some of this damage is subtle during a ground-level inspection. That is one reason scope disagreements can develop later.
Heavy Rain and Interior Water Damage
Morgan’s Point property owners also deal with the consequences of heavy rainfall and wind-driven moisture.
Water may enter through a roof opening, failed flashing, damaged exterior components, windows, or other storm-affected portions of a building. Once inside, moisture can migrate through insulation, drywall, ceilings, flooring, cabinets, and concealed cavities.
What looks like one ceiling stain can represent a larger repair scope.
Common Insurance Claims in Morgan’s Point
Because Morgan’s Point combines Gulf Coast residential property with waterfront, commercial, and industrial surroundings, losses can vary considerably from one property to another.
| Claim Type | Damage We Commonly Review |
| Hurricane & Tropical Storm | Roofing, exterior, openings, wind-driven rain, interior finishes |
| Wind Damage | Shingles, flashing, gutters, siding, fencing, detached structures |
| Hail Damage | Roofing, metal components, vents, gutters, HVAC equipment |
| Water Damage | Ceilings, walls, flooring, cabinetry, insulation, contents |
| Roof Claims | Shingles, membranes, underlayment, flashing and related components |
| Fire & Smoke | Structural damage, soot, smoke, contents and restoration scope |
| Commercial Claims | Building components, equipment, inventory and business property |
Hail Damage Claims
Morgan’s Point is better known for tropical and coastal weather than North Texas-style hail exposure, but hail remains a legitimate Gulf Coast thunderstorm risk. If you are dealing with a hail damage insurance claim, documenting the roof and collateral damage early can help establish what occurred during the storm.
Hail damage may affect asphalt shingles, metal roof systems, vents, gutters, rooftop equipment, soft metals, siding, screens, and outdoor property.
The challenge is proving what happened and separating storm-created damage from prior wear.
Photographs, weather information, roof conditions, collateral damage, repair requirements, and the insurance policy can all become important.
Water Damage Claims
Water claims can be among the most difficult losses to scope correctly because moisture travels. Property owners who are dealing with an insurance adjuster after water damage should keep photographs, mitigation records, invoices, and communications organized throughout the claim.
Damage may be visible on one wall while continuing behind baseboards, under flooring, above ceilings, or inside insulation.
For Morgan’s Point properties, we examine both the visible loss and reasonable areas of concealed or secondary damage. We also pay close attention to cause of loss, because coverage for plumbing discharge, wind-driven rain, roof openings, and rising water can differ substantially.
Fire Damage Claims
A fire damage insurance claim is rarely limited to the materials touched directly by flames.
Smoke and soot can spread into adjacent rooms and building systems. Water used during suppression can cause additional damage. Contents may need detailed inventory documentation. Electrical, structural, mechanical, and finish components may require separate evaluation.
For larger losses, understanding the role of a fire insurance adjuster can also help property owners recognize how the damage will be inspected and evaluated.
Storm Damage Claims
Morgan’s Point storm losses can involve several causes of damage during the same weather event.
A severe storm may cause:
- Wind damage to roofing or exterior components
- An opening that allows water intrusion
- Wet insulation and drywall
- Flooring or cabinet damage
- Exterior accessory damage
- Power or equipment issues
If an estimate addresses only item one, the settlement may fail to reflect the full covered scope.
Roof Damage Claims
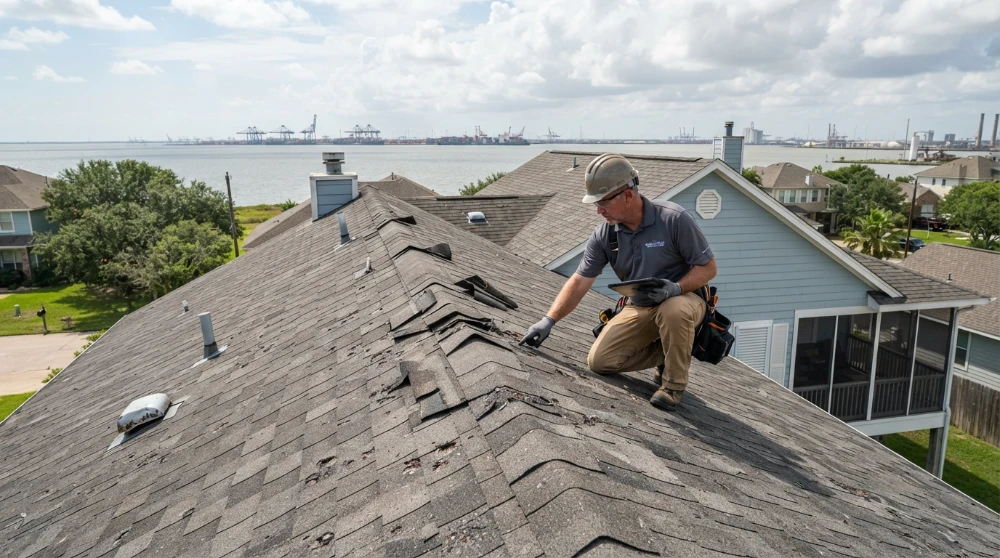
Roof claims frequently become disputed because insurers and property owners may disagree about causation, repairability, material matching, damaged accessories, or the extent of necessary work.
We inspect roof systems in the context of the entire loss.
Depending on the building, that may include:
- Asphalt shingles
- Metal roofing
- Flat or low-slope roofing
- Flashing
- Vents
- Gutters and downspouts
- Edge metal
- Roof penetrations
- Underlayment where applicable
- Interior evidence of water intrusion
A roof claim should account for what is actually damaged and what is reasonably required to perform covered repairs.
Commercial Property Claims
Morgan’s Point has an unusual local property mix because the community sits next to one of the Houston region’s most important maritime corridors. Port Houston’s Barbours Cut Terminal is located within the city, alongside other large industrial operations.
Commercial claims can involve substantially more documentation than a typical residential loss.
Depending on the policy and event, issues may include:
- Structural damage
- Commercial roofing
- Mechanical systems
- Electrical components
- Interior build-outs
- Equipment
- Inventory
- Contents
- Exterior improvements
- Water mitigation
- Business-income-related documentation where covered
TX Public Adjusting handles both residential and commercial claims and can coordinate documentation across multiple trades and loss categories.
Property Damage Around Morgan’s Point’s Residential Core
Morgan’s Point is too small to be divided into the large named neighborhoods found in Houston, Dallas, or San Antonio. Local relevance is better understood through its historic residential and waterfront areas.
Morgan’s Point National Historic District
The Morgan’s Point National Historic District includes the historic City Hall carriage house, the Governor Ross S. Sterling mansion, and other notable properties.
The city’s history page explains that the bluff became a summer retreat for Houston families during the late 1800s, with homes representing architectural styles ranging from Queen Anne and Eastlake influences to Mediterranean Revival, Colonial Revival, and Prairie School design.
Older or historically significant properties can make claim scoping more involved. Materials, craftsmanship, dimensions, finishes, and repair methods may not correspond neatly with modern production-home pricing.
That does not automatically mean every historical feature is covered at any particular value. It means the property should be documented accurately rather than treated as if every component were interchangeable with modern construction.
Bayridge Road and the Historic Residential Area
Properties around Bayridge Road form part of Morgan’s Point’s recognizable residential landscape. Homes here face the same Gulf Coast weather pressures as newer construction, but age, prior repairs, unique materials, and historical architecture can add another layer to a claim.
When evaluating storm damage to an older home, causation matters. An insurer may point to age or wear while the policyholder believes a recent storm caused new functional damage.
Detailed photographs and a component-by-component scope help distinguish those issues.
Galveston Bay Waterfront Properties
Waterfront and near-water properties experience constant environmental exposure.
Salt air, wind, humidity, intense sun, and storms can affect building materials over time. After a covered event, distinguishing recent storm damage from long-term deterioration is particularly important.
A well-prepared claim should document the condition and characteristics of the damaged property—not simply state that a storm occurred.
Yellow Rose Way and the Barbours Cut Corridor
The eastern portion of Morgan’s Point has a very different character from the historic residential bluff. Yellow Rose Way leads toward open space and the Barbours Cut area, placing residential, municipal, commercial, and port-related property within a compact geographic area.
The city’s Colonel James Morgan New Washington Prairie spans 52 acres on Yellow Rose Way and includes wetlands, trails, ponds, and native vegetation.
This combination of developed property, shoreline influences, open land, and major infrastructure is part of what makes Morgan’s Point distinct from an ordinary inland suburb.
Why Insurance Claims Become Underpaid
An underpaid claim does not always begin with an outright denial.
More often, the carrier agrees that a covered event occurred but the estimate does not fully reflect the damage or necessary repairs.
Missed Damage
Some damage is easy to overlook during a brief inspection.
Examples include:
- Flashing
- Roof accessories
- Gutters
- Exterior fixtures
- Window components
- Fence sections
- Interior moisture
- Insulation
- Baseboards
- Paint transitions
- Adjacent rooms
Small omissions can add up quickly.
Scope Omissions
An insurer may include the primary damaged component while excluding work necessary to complete the repair.
A scope review examines not only what needs replacement but also the labor, access, removal, preparation, installation, finishing, and related work needed to restore covered property.
Depreciation Issues
Insurance estimates may apply depreciation depending on the policy, material, age, condition, and coverage structure.
Property owners often see terms such as:
- Replacement Cost Value
- Actual Cash Value
- Recoverable depreciation
- Nonrecoverable depreciation
These are not interchangeable.
We review how depreciation has been applied and whether the estimate is consistent with the policy and documented property conditions.
Low Estimates
Two adjusters can inspect the same loss and produce very different scopes.
Differences may result from:
- Missing measurements
- Different repair assumptions
- Omitted trades
- Material selections
- Labor operations
- Incomplete interior scope
- Failure to account for associated damage
The solution is evidence. Our goal is to present a supported scope showing what needs to be addressed and why.
Documentation Problems
A legitimate claim can become harder to resolve when the file lacks photographs, measurements, inventories, receipts, contractor information, mitigation records, or a clear chronology.
Good documentation creates a factual claim record.
That is one of the central functions of public adjusting.
Incomplete documentation, rushed repairs, and assumptions about coverage are among the common property insurance claim mistakes that can make an already difficult loss harder to resolve.
Our Public Adjusting Process
Every Morgan’s Point claim is different, but our work generally follows five stages.
1. Claim Review
We begin by discussing what happened, reviewing the current status of the claim, and examining relevant documents.
That may include:
- Insurance policy
- Carrier estimate
- Coverage letters
- Payment records
- Contractor estimates
- Photographs
- Prior correspondence
If the loss is already in progress, we identify the areas where additional documentation or clarification may be needed.
2. Property Inspection
We inspect the damaged property and evaluate the loss from the policyholder’s perspective.
For a storm claim, that can mean looking beyond the roof to the exterior envelope, interior evidence, detached structures, mechanical equipment, and other affected components.
3. Documentation and Scope Preparation
We organize the claim evidence.
Depending on the loss, that may include:
- Photographs
- Measurements
- Damage notes
- Contents information
- Repair scope
- Supporting estimates
- Contractor information
- Relevant claim correspondence
The goal is a claim package that explains the loss clearly.
4. Claim Presentation and Negotiation
We communicate with the insurer regarding documented differences in scope and valuation and advocate for the policyholder within the terms of the policy.
Public adjusters do not control what an insurer ultimately agrees to pay. What we can control is the quality of the investigation, documentation, presentation, and negotiation performed on your behalf.
5. Settlement Review
When the carrier responds, we review the revised documentation and settlement information to identify whether material claim issues remain unresolved.
If additional covered damage is discovered or adequately supported supplemental items remain outstanding, those issues can be addressed through the appropriate claim process.
A Public Adjuster Works for the Policyholder
This distinction matters.
The insurance company has professionals handling claims every day. The property owner may be dealing with a major insurance loss for the first time.
TX Public Adjusting gives the policyholder experienced representation.
We do not work for the insurance company.
We help property owners understand the claim, organize evidence, identify scope differences, communicate with the insurer, and advocate for proper consideration of covered damage.
Our team has experience reviewing thousands of property claims across residential and commercial losses. That experience helps us recognize the types of estimating and documentation issues that can be missed when a claim is evaluated too narrowly.
Have a Morgan’s Point claim that looks too low? Request a Free Claim Review from TX Public Adjusting. No upfront fees.
Why Choose TX Public Adjusting in Morgan’s Point?
Licensed Texas Public Adjuster
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839.
Licensing matters. Property owners should know who is representing them and verify that the person or company performing regulated public adjusting work is properly licensed.
Texas-Focused Claim Experience
Texas property claims have their own weather patterns, building systems, policy issues, deductibles, and claim practices.
Morgan’s Point adds another level of local complexity because it is a coastal Harris County community directly connected to the Galveston Bay and Houston Ship Channel environment.
We understand that a Morgan’s Point hurricane claim does not look like a hail claim in Frisco or a freeze claim in Austin.
The claim strategy should fit the property and loss.
Residential and Commercial Experience
We handle claims involving:
- Single-family homes
- Historic residences
- Rental properties
- Multifamily property
- Retail buildings
- Warehouses
- Offices
- Industrial and commercial property
Commercial losses often require broader documentation, coordination among different specialists, and careful attention to policy provisions.
Independent Representation
Our client is the policyholder.
That creates a fundamentally different relationship from the carrier-adjuster model.
We investigate and present the property owner’s claim rather than representing the insurer’s financial interests.
Detailed Scope Review
Many disputes come down to the estimate.
We examine what has been included, what may have been missed, how repairs have been scoped, and whether the available evidence supports additional covered work.
No Upfront Fees
You can begin with a Free Claim Review.
There are no upfront fees for engaging TX Public Adjusting under our contingency-based public adjusting arrangement. The specific fee terms are disclosed in the public adjusting agreement before representation begins.
Morgan’s Point Landmarks and Local Character
Morgan’s Point may be small, but its identity is remarkably distinct.
The community developed around the former New Washington settlement at the junction of Buffalo Bayou and San Jacinto Bay. Colonel James Morgan later promoted the commercial potential of a navigable channel that ultimately became connected to the Houston Ship Channel’s development.
Today, recognizable local places include:
- Morgan’s Point National Historic District
- Governor Ross S. Sterling Mansion
- Colonel James Morgan New Washington Prairie
- Barbours Cut Terminal
- Russell Applebe Hike & Bike Trail
- Emily Morgan Yellow Rose Park
The Colonel James Morgan New Washington Prairie includes a pond, wetlands, observation areas, and trails, while the Russell Applebe trail circles the residential portion of the city.
These details matter because Morgan’s Point should not be treated as simply another Houston-area ZIP code. It is a historic bayside community with direct exposure to some of Southeast Texas’s most powerful weather systems.
Areas We Serve Near Morgan’s Point
TX Public Adjusting assists policyholders throughout Morgan’s Point and surrounding eastern Harris County and Galveston Bay communities, including:
- La Porte
- Shoreacres
- Deer Park
- Pasadena
- Baytown
- Seabrook
- Clear Lake-area communities
- Houston
- Other Harris County communities
Morgan’s Point lies within the La Porte Independent School District and is approximately 30 miles east of Houston.
Property owners across this corridor face many of the same hurricane, wind, rain, roof, and water-damage risks, but individual policies and property conditions differ. We review each claim on its own facts.
Frequently Asked Questions About Public Adjusters in Morgan’s Point
What does a public adjuster in Morgan’s Point do?
A public adjuster represents the policyholder during a property insurance claim. TX Public Adjusting can inspect the damage, review the insurance company’s estimate, document missing items, prepare a claim scope, communicate with the carrier, and negotiate documented differences.
This can be particularly useful in Morgan’s Point when a hurricane or severe storm damages several parts of a property at once and the initial carrier estimate addresses only a portion of the loss.
When should I hire a public adjuster after a Morgan’s Point storm?
You can hire a public adjuster at different stages of a claim. Some property owners bring us in shortly after the loss because they want assistance documenting it from the beginning. Others call after receiving an estimate that appears too low or after the claim becomes delayed or disputed.
The sooner we review the property and available documentation, the easier it may be to preserve evidence and understand the issues. However, an existing claim may still be worth reviewing even if the carrier has already inspected the property.
Can a public adjuster help after hurricane damage in Morgan’s Point?
Yes. Hurricane losses are among the property claims we handle.
A Morgan’s Point hurricane claim may involve roof damage, exterior damage, broken openings, wind-driven rain, interior water intrusion, contents, fencing, trees, equipment, or commercial property. Because the city sits directly on the Galveston Bay/Houston Ship Channel system, coastal water may also become part of the causation analysis.
The insurance policy determines what is covered, so separating different causes of damage can be important.
Does homeowners insurance cover storm surge in Morgan’s Point?
Standard property policies often treat flood or rising surface water differently from wind and rain damage, but the exact answer depends on your specific policy and any separate flood coverage.
That distinction is especially relevant in Morgan’s Point. The National Weather Service recorded elevated water levels at the city during Harvey and Beryl. If a claim involves both wind damage and water, the actual source and path of the water should be documented carefully rather than assumed.
Can you help if my Morgan’s Point roof claim was underpaid?
Yes. Roof claims are a major part of property-claim work.
We can compare the carrier estimate with observed damage and repair requirements, review roofing components that may have been omitted, and document related exterior or interior damage. An underpaid roof claim can sometimes be the result of scope differences rather than a dispute over whether the storm happened at all.
Can I hire TX Public Adjusting after the insurance company has already paid me?
Potentially. Receiving an initial insurance payment does not necessarily mean every claim issue has been resolved.
If you believe damage was missed or the repair scope is incomplete, we can review the claim documents and determine whether there are supportable issues that may still be presented under the policy and applicable claim process.
Deadlines and policy conditions can apply, so waiting unnecessarily is not advisable. If your claim is already underway, you may also want to understand when it is too late to hire a public adjuster and what factors can affect your remaining options.
How much does a Morgan’s Point public adjuster cost?
Public adjusting services are generally performed under a written fee agreement that explains how compensation is calculated. TX Public Adjusting offers a Free Claim Review and no upfront fees.
Before representation begins, the applicable fee arrangement should be explained clearly so you understand it.
Do you handle commercial insurance claims near Barbours Cut and the Ship Channel?
Yes. TX Public Adjusting handles residential and commercial property claims.
Commercial claims can involve roofing, structures, interior improvements, equipment, inventory, contents, water mitigation, and other insured property. Because commercial policies can differ substantially from homeowners policies, we review the actual contract and loss circumstances before developing a claim strategy.
What happens if my insurer says the damage is wear and tear?
Wear, deterioration, and maintenance issues are common points of disagreement in roof and exterior claims. A public adjuster cannot turn old deterioration into covered storm damage.
Our role is to document what happened and distinguish conditions where possible. If a recent storm caused identifiable new damage, photographs, weather information, collateral damage, repair observations, and other evidence may help support that position.
Why choose a Texas public adjuster instead of handling the claim myself?
Property owners are allowed to handle their own claims, and not every loss requires professional representation.
A public adjuster becomes particularly valuable when the loss is substantial, several parts of the building are damaged, the insurer’s estimate appears incomplete, the claim requires significant documentation, or you do not have the time or experience to manage a complicated adjustment.
TX Public Adjusting brings residential and commercial claim experience, detailed scope review, documentation, and policyholder representation to that process.
Get Insurance Claim Help in Morgan’s Point
Property owners in Morgan’s Point live in one of the Houston region’s most distinctive environments: a historic residential community positioned directly between Galveston Bay and the Houston Ship Channel.
That location is part of the city’s appeal. It also means hurricanes, tropical storms, coastal water, wind-driven rain, and severe thunderstorms deserve to be taken seriously when property damage occurs.
If your insurance estimate does not match the damage you see—or you simply want an experienced professional to review the claim before you proceed—contact TX Public Adjusting.
Rise Public Adjusting LLC
Texas License #3356839
Request Your Free Claim Review
- Licensed Texas Public Adjuster
- Residential & Commercial Claims
- Independent Policyholder Representation
- Detailed Damage & Estimate Review
- No Upfront Fees
- Serving Morgan’s Point and surrounding Harris County communities
Contact TX Public Adjusting today for a Free Claim Review.