

Property damage in Kenney can turn into a complicated insurance claim quickly. A severe thunderstorm can damage a metal roof, hail can strike shingles and exterior finishes, wind can lift roofing or damage outbuildings, and a plumbing leak can affect multiple rooms before the source is discovered. For rural homes, ranch properties, workshops, barns, and local businesses, determining the full scope of a loss is often more involved than looking at the most obvious damage.
TX Public Adjusting is a licensed Texas public adjuster representing residential and commercial policyholders during property insurance claims in Kenney. We work for the policyholder—not the insurance company—and help document damage, review estimates, identify missing claim items, and negotiate covered losses.
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839.
If your Kenney insurance claim has been delayed, denied, underpaid, or simply feels incomplete, request a Free Claim Review. There are no upfront fees to have us review your situation and explain the next steps.
Why Property Owners Hire a Public Adjuster in Kenney
Kenney is a small, unincorporated community in northern Austin County located along State Highway 36 between Bellville and Brenham. Its setting is distinctly different from a dense Texas metro: properties around Kenney commonly include larger lots, acreage, detached structures, agricultural improvements, workshops, and rural residences. The community developed around the railroad in the late nineteenth century and remains closely connected with both Bellville and Brenham.
Those property characteristics matter after a loss.
An insurance carrier’s initial inspection may focus heavily on the primary residence or obvious point of damage. A policyholder may also need to account for damage to roofing components, gutters, fencing, detached structures, mechanical equipment, exterior finishes, contents, or interior areas affected by water intrusion.
A public adjuster in Kenney evaluates the claim from the policyholder’s side. Our job is to develop a detailed picture of the covered loss and present documentation that supports the claim.
Property owners commonly contact us when:
- The insurance company’s estimate appears too low.
- Damage was left out of the carrier’s scope.
- A roof claim was approved for repair when broader replacement may need evaluation.
- Hail or wind damage extends beyond the roof.
- Water intrusion affected ceilings, walls, insulation, flooring, or contents.
- A commercial or agricultural property contains multiple damaged structures.
- The carrier has requested substantial documentation.
- The claim has stalled or communication has become difficult.
- A previously settled claim appears to have unresolved damage.
- The policyholder wants independent representation before accepting a settlement.
Need another set of eyes on your claim? Contact TX Public Adjusting for a Free Claim Review.
Property Damage Risks in Kenney, Texas

Kenney’s location in southeastern Central Texas creates a mix of weather exposures. The area’s humid subtropical climate brings hot conditions and precipitation throughout the year, while its position between the Houston region and Central Texas leaves properties exposed to thunderstorms, hail, damaging winds, heavy rain, and occasional severe-weather systems.
Hail and Severe Thunderstorms
Spring and early summer thunderstorms are a major concern for Austin County property owners. Hail does not have to break a roof open to produce a legitimate property-loss issue.
On asphalt roofing, hail may cause bruising, granule loss, fractured mats, and impacts to vents or flashing. On metal buildings and roofs, impacts can create dents and damage finishes. Gutters, downspouts, window screens, fencing, HVAC fins, siding, and other exterior components can also show storm impacts.
Rural properties around Kenney may contain several structures spread across a single parcel. A storm inspection therefore should not stop at the main house.
Wind Damage
Strong thunderstorm winds can lift shingles, damage ridge caps, loosen flashing, tear metal panels, damage fences, and send tree limbs or other debris into structures.
Wind-driven rain can create a second layer of damage when water enters through a storm-created opening. Interior staining may be the first visible sign, while insulation, decking, drywall, and other materials above or behind the finished surface may also require evaluation.
Heavy Rain and Water Intrusion
Kenney’s relatively wet climate can produce significant rainfall during thunderstorms and tropical weather systems reaching inland from the Gulf.
Property owners should distinguish between different causes of water damage because insurance coverage can depend heavily on how water entered the property. A roof opening created by covered wind damage may be handled differently from rising surface water or another excluded source.
Our role as a public adjuster is to document what happened, identify the resulting damage, and evaluate the policy and carrier position—not to assume that every form of water loss is covered.
Tropical Storm and Hurricane Remnants
Kenney sits well inland from the immediate Gulf Coast, but inland communities can still experience heavy rainfall and powerful wind as tropical systems move across Texas. Property owners dealing with property damage after a hurricane should document both the initial storm damage and any resulting interior water intrusion as quickly as conditions safely allow.
A weakening hurricane does not need hurricane-force winds over Kenney to create a property claim. Gusts, prolonged rainfall, falling limbs, roof damage, and wind-driven water can produce substantial losses.
Freeze and Plumbing Losses
Cold snaps create another Texas property risk. Frozen plumbing can rupture inside walls, ceilings, attics, utility spaces, or detached structures.
Once water begins flowing again, a small split in a pipe can cause extensive damage before the problem is found. Claims may involve extraction, drying, damaged drywall, insulation, cabinets, flooring, electrical components, and personal property.
Common Insurance Claims in Kenney
A property insurance claim should reflect the complete covered loss, not simply the first visible damage discovered after the event.
Hail Damage Claims
Hail claims are among the most detail-sensitive storm claims we review. Property owners dealing with a hail damage roof insurance claim should make sure the inspection goes beyond obvious shingle damage. The roof may receive most of the attention, but a thorough inspection can include:
- Asphalt shingles
- Standing-seam and other metal roofing
- Gutters and downspouts
- Roof vents
- Flashing
- HVAC equipment
- Siding
- Windows and screens
- Exterior paint and finishes
- Detached garages and workshops
- Barns and accessory buildings
TX Public Adjusting can review a hail claim when the carrier estimate does not appear to match the damage observed on the property.
Water Damage Claims
Water losses may result from broken supply lines, plumbing failures, appliance leaks, roof openings, or other covered events. A water damage public adjuster can help evaluate whether the carrier’s scope accounts for the full extent of covered damage.
A meaningful scope may need to address more than wet flooring. Depending on the loss, damage can extend into drywall, insulation, cabinetry, trim, ceilings, subflooring, electrical systems, and contents.
Documentation also matters after emergency mitigation. Removed materials, moisture readings, photographs, invoices, and restoration records can become important evidence during the claim.
Fire and Smoke Damage Claims
A structure fire can produce several different types of loss at once. Working with a fire insurance adjuster who represents the policyholder can be especially valuable when the loss involves building damage, contents, smoke, soot, and water from firefighting efforts.
Direct flame damage may be concentrated in one area while smoke, soot, heat, odor, suppression water, and debris affect much more of the building. Contents may require cleaning, evaluation, or replacement. A residence may also become temporarily uninhabitable.
Fire claims can require careful coordination because building damage and contents are often evaluated separately.
Storm Damage Claims
Severe weather claims in Kenney may combine wind, rain, fallen trees, debris impact, hail, and interior water intrusion.
Determining the sequence of events is important. If a storm damages the roof and water subsequently enters the structure, properly documenting the storm-created opening and resulting interior damage can become central to the claim.
Roof Damage Claims
Roof claims frequently become disputed over the extent of damage and appropriate repair method. A public adjuster for a roof claim can compare the carrier’s estimate with documented roof conditions and identify differences in the proposed scope.
Issues can include:
- Missing storm damage
- Repair-versus-replacement disagreements
- Incomplete roof measurements
- Missing flashing or accessories
- Incorrect roofing material assumptions
- Detached structure omissions
- Interior damage omitted from the roof-loss scope
- Depreciation calculations
- Repairability questions
We review the carrier’s estimate alongside the conditions observed at the property and supporting documentation.
Commercial Property Claims
Commercial property claims can involve considerably more than repairing a roof or replacing drywall, especially when multiple buildings, equipment, inventory, or business operations are affected. Kenney and the surrounding Austin County area include rural enterprises, workshops, agricultural-related buildings, retail operations, storage structures, offices, and other commercial properties.
Depending on the policy and loss, a commercial claim may involve:
- Building damage
- Roofing systems
- Interior finishes
- Equipment
- Business personal property
- Inventory
- Code-related repair requirements
- Temporary protection
- Debris removal
- Business-income-related issues where applicable under the policy
Commercial losses often benefit from organized documentation because several categories of damage can be evaluated simultaneously.
Why Kenney Insurance Claims Become Underpaid
An underpaid claim does not always result from one dramatic disagreement. Many claims come up short because multiple smaller omissions compound.
Missed Damage
A fast inspection can overlook secondary damage, particularly on properties with multiple structures.
A residence, workshop, barn, detached garage, fence, and exterior mechanical equipment may all have been exposed to the same hailstorm. If only one structure receives a detailed inspection, the resulting estimate may not represent the entire loss.
Scope Omissions
An estimate may acknowledge damage while leaving out materials or labor required to perform the repair correctly.
Depending on the project, missing items could include removal work, flashing, underlayment, trim, insulation, painting, access requirements, disposal, or associated interior repairs.
Depreciation Issues
Many property policies calculate an initial payment using actual cash value and may allow recoverable depreciation after qualifying repairs are completed, subject to policy terms.
Policyholders sometimes misunderstand what was depreciated, which amounts may be recoverable, or what documentation is required. Reviewing the estimate line by line can make those calculations much easier to understand.
Low Estimates
Two estimates for the same loss can differ substantially when the scopes are not actually describing the same work.
A contractor estimate may include work that is absent from the insurance estimate. The productive question is not simply which total is higher. The important question is why the scopes differ.
Documentation Problems
Property claims rely on evidence.
Photographs taken after materials have already been removed may not show the original conditions. Contents lists without sufficient detail can become difficult to substantiate. Missing invoices or mitigation records can create additional questions.
One of the most valuable things a Kenney public adjuster can do is organize the claim file so supporting information is connected directly to the loss being claimed.
How a Public Adjuster Is Different From the Insurance Company’s Adjuster
The distinction is straightforward.
An insurance company adjuster works for or on behalf of the insurer. A public adjuster is hired by the policyholder.
TX Public Adjusting represents your interests in the property claim. We do not work for the insurance carrier.
That independence allows us to:
- Review the policy and claim documentation from the policyholder’s perspective.
- Inspect and document property damage.
- Compare the insurer’s estimate with the observed scope.
- Identify omitted or disputed claim items.
- Organize supporting documentation.
- Communicate with the carrier concerning the covered loss.
- Negotiate the property claim on your behalf.
A public adjuster cannot guarantee that every requested item will be covered, and policy terms still control. Our role is to help make sure the claim is properly documented and presented.
Our Public Adjusting Process in Kenney
A structured process helps prevent important parts of a property loss from becoming disconnected from the claim.
Step 1: Claim Review
We begin by discussing the loss, current claim status, carrier communications, and the concerns that caused you to seek help.
If an estimate or coverage letter has already been issued, we can review those documents as part of the evaluation.
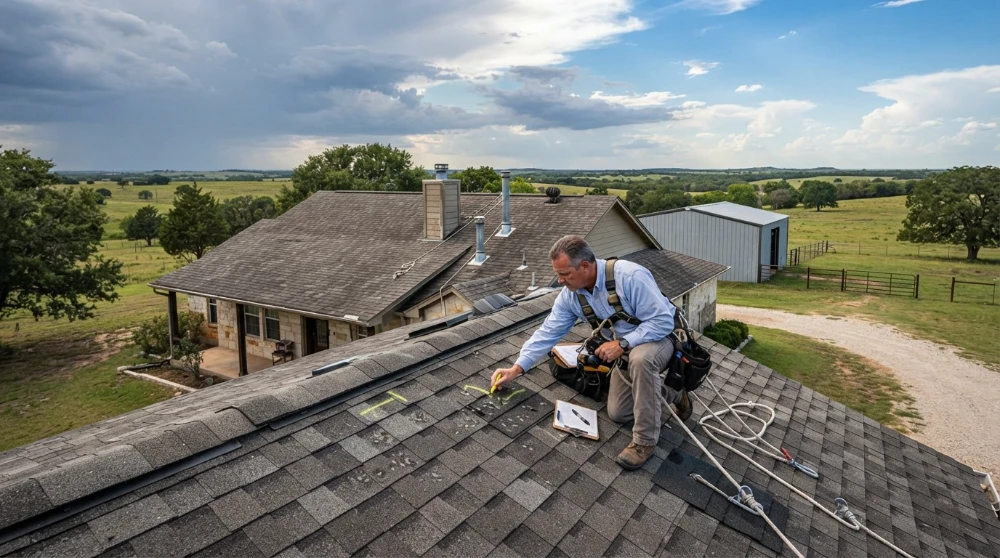
Step 2: Property Inspection
We inspect the damaged property and evaluate the areas related to the reported event.
On acreage or rural properties around Kenney, that can mean inspecting more than one building rather than limiting the review to the primary residence.
Step 3: Damage Documentation
We build documentation supporting the loss. Depending on the circumstances, this can include photographs, measurements, estimates, inventories, invoices, reports, and related records.
The goal is to connect each claimed item to clear supporting information.
Step 4: Claim Presentation and Negotiation
We communicate the documented claim position to the carrier and address differences between our assessment and the insurer’s scope.
When the carrier questions an item, we work through the documentation and policy issues supporting our position.
Step 5: Settlement and Claim Resolution
We continue representing the policyholder through the adjustment process and settlement discussions.
The objective is a properly supported resolution based on the covered damage and applicable policy—not an arbitrary number.
A Closer Look at Kenney and Northern Austin County
Kenney’s identity is closely tied to its rural setting and Texas history. The community sits at State Highway 36 and FM 2754, roughly eight miles north of Bellville and south of Brenham. The railroad helped establish the town in 1880, and the community eventually took the name of pioneer Methodist preacher John Wesley Kenney.
Unlike a large city with formally designated urban neighborhoods, Kenney is better understood through its rural roads, acreage properties, nearby communities, and its State Highway 36 corridor.
Local reference points include:
- State Highway 36, the primary north-south connection toward Bellville and Brenham.
- Loop 497, running through the community.
- The historic railroad corridor, which played a central role in Kenney’s development.
- The John Wesley Kenney historical connection, reflecting the area’s early Texas settlement history.
That rural character creates claim considerations that a generic metropolitan property page would miss. Detached buildings are common. Roof types vary. Large parcels can contain fencing and additional improvements. Storm damage may be spread across a property rather than concentrated on a single structure.
Residential Property Claims in Rural Kenney
A larger property can require more documentation, not less.
For example, a hailstorm may affect the main home’s composition roof while also denting a metal workshop, damaging gutters on another structure, impacting fencing, and striking outdoor HVAC equipment.
Likewise, wind damage may involve tree impact on one part of the property while creating roof openings elsewhere.
When reviewing a residential claim in Kenney, we consider how the loss affected the property as a whole.
Property types we can assist with include:
- Primary residences
- Rural homes
- Acreage properties
- Rental homes
- Detached garages
- Workshops
- Barns and qualifying accessory structures
- Multifamily properties
- Other insured residential improvements
Coverage always depends on the individual policy and circumstances of the loss.
Commercial Insurance Claim Help in Kenney
Small communities still have complex commercial insurance losses.
A business owner may be dealing simultaneously with building repairs, damaged inventory or equipment, temporary protection, cleanup, contractor estimates, and ongoing insurer requests.
TX Public Adjusting helps commercial policyholders organize the property side of that process.
We have experience reviewing residential and commercial claims, including complex property-loss files where the original carrier scope does not appear to account for all documented damage.
Our team has reviewed thousands of property claims, giving us practical experience with claim estimates, documentation requirements, policy provisions, inspections, supplements, and negotiation.
Get a Free Commercial or Residential Claim Review
If you already received an estimate from your insurance carrier, you do not have to guess whether it is complete.
Send it to TX Public Adjusting for a Free Claim Review. We can discuss what the carrier included, what concerns you have, and whether professional public adjusting assistance may be appropriate.
No upfront fees. Licensed Texas Public Adjuster. Residential & Commercial Claims.
Why Choose TX Public Adjusting in Kenney?
Insurance companies have experienced professionals working on their side of a property claim. Policyholders are entitled to hire licensed representation of their own.
TX Public Adjusting offers:
Texas-Focused Claim Experience
We concentrate on property claims in Texas. That means regularly dealing with the types of losses Texas owners encounter—hail, severe thunderstorms, wind, freeze damage, fire, water losses, and major storm events.
Licensed Public Adjuster Representation
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839.
Licensing matters. Property owners should know who is representing them and verify that public adjusting services are being performed by properly licensed professionals.
Independent Representation
We represent policyholders.
We are not the insurance carrier’s adjuster, and our job is not to protect the insurer’s financial interests. Our responsibility is to present and support the policyholder’s property claim.
Residential and Commercial Experience
Property losses vary dramatically. A house with storm damage presents different issues from a commercial building, warehouse, retail property, multifamily structure, or rural property with several insured improvements.
Our experience spans both residential and commercial claims.
Detailed Scope Review
We do more than compare the bottom-line number of two estimates. We look at what was actually included.
That can reveal differences involving materials, quantities, repair operations, affected areas, or supporting documentation.
Areas We Serve Near Kenney
Our work is not limited to the immediate Kenney community. We assist property owners throughout Austin County and surrounding parts of southeastern Central Texas. Property owners can also find claim assistance from our public adjuster in Brenham, public adjuster in Industry, and public adjuster in Sealy.
Kenney’s location along Highway 36 makes Bellville and Brenham especially important nearby service areas. The community lies between the two, with Bellville approximately eight miles to the south.
Frequently Asked Questions About Public Adjusters in Kenney
What does a public adjuster in Kenney do?
A public adjuster represents you, the policyholder, during your property insurance claim. We inspect and document the loss, review the insurance company’s estimate, identify differences or omissions, prepare supporting documentation, and communicate with the insurer concerning the claim.
This can be particularly valuable on rural Kenney properties where a single storm may affect a residence, detached structures, roofing, fencing, HVAC equipment, and other insured improvements.
When should I hire a public adjuster after storm damage in Kenney?
You can contact a public adjuster soon after discovering the loss, but you can also seek help after the insurance company has inspected the property or issued an estimate.
Many Kenney property owners reach out because the first settlement appears too low, roof damage is disputed, or parts of the property were not included in the initial scope. The earlier the documentation is organized, the easier it can be to preserve evidence of the original damage.
Can a public adjuster help if my Kenney claim has already been paid?
Potentially. A payment does not necessarily tell you whether every claim issue has been resolved.
The answer to when it is too late to hire a public adjuster depends on factors such as the claim’s status, policy requirements, applicable deadlines, releases, previous repairs, and other circumstances. We can review the available documentation and explain what options may remain.
Can you help with hail damage to a metal roof or metal building?
Yes. Hail losses involving metal surfaces may require a different evaluation from composition-shingle roofing.
Kenney and the surrounding rural area include properties with metal roofs, barns, workshops, and other metal structures. We can document affected components and review how the insurer evaluated the damage, subject to the property’s coverage and policy terms.
What if the insurance company says my roof only needs repairs?
Repair-versus-replacement disputes are common in roof claims. The correct answer depends on the actual damage, roofing system, affected materials, repairability, policy provisions, and other circumstances.
We can compare the carrier’s proposed repairs with the observed property conditions and supporting documentation. We do not assume every damaged roof requires replacement, but we do make sure the claim position is supported by a detailed evaluation.
Can you help with damage to barns, garages, or workshops around Kenney?
Potentially, provided the damaged structure or property is insured under the policy.
This question is especially relevant around Kenney because many rural and acreage properties contain multiple improvements. We review the policy and claim to determine which structures are involved and document covered damage accordingly.
Do you handle commercial property claims in Kenney?
Yes. TX Public Adjusting assists both residential and commercial policyholders.
Commercial claims may involve roofing, structural components, interiors, equipment, business personal property, inventory, and other categories depending on the loss and coverage. We organize the documentation and represent the policyholder during the adjustment process.
How much does it cost to have TX Public Adjusting review my Kenney claim?
We offer a Free Claim Review with no upfront fees.
After learning about the claim and reviewing the available information, we can explain whether public adjusting services may be appropriate and how fees would apply if you choose to engage us.
Does a public adjuster work for my insurance company?
No. That is one of the most significant differences between a public adjuster and the insurer’s adjuster.
A public adjuster is retained by the policyholder. TX Public Adjusting represents property owners, not insurance companies, during covered property claims.
What should I have ready before requesting a claim review?
If available, gather your insurance estimate, coverage or decision letters, photographs, contractor estimates, mitigation invoices, repair proposals, and relevant emails from the insurance company.
Do not delay contacting us just because you do not have every document. We can start by discussing what happened, where the Kenney property is located, what damage you have found, and what the carrier has done so far.
Get Insurance Claim Help in Kenney, TX
A low estimate does not have to be the last word on a property claim.
If hail, wind, water, fire, roof damage, or another covered event has damaged your home, rural property, or business in Kenney, TX Public Adjusting can review the claim from the policyholder’s perspective.
TX Public Adjusting
Rise Public Adjusting LLC
Texas License #3356839
Request your Free Claim Review today.
- No upfront fees
- Licensed Texas Public Adjuster
- Residential & Commercial Claims
- Independent policyholder representation
- Detailed inspections and claim documentation
- Insurance estimate and scope reviews
- Claim negotiation assistance
Contact TX Public Adjusting and find out whether important damage or claim items may have been missed.