Property damage in Fredericksburg can create a difficult insurance claim long after the storm, leak, or fire is under control. A roof may show obvious hail strikes, but a hail damage insurance claim can still leave out flashing, gutters, interior moisture, code-related work, or damage to detached structures. A plumbing loss may affect flooring, cabinets, insulation, and wall cavities even when the first inspection focuses only on visible water stains.
TX Public Adjusting provides insurance claim help in Fredericksburg for residential and commercial property owners. We represent policyholders—not insurance companies—throughout the claim review, inspection, documentation, and negotiation process. TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839.
Fredericksburg sits in Gillespie County in the heart of the Texas Hill Country. The area’s mix of historic homes, ranch properties, wineries, lodging businesses, retail buildings, metal roofs, older masonry, and newer residential construction creates claim issues that require more than a quick surface inspection. Fredericksburg is also exposed to severe thunderstorms, hail, damaging wind, wildfire conditions, freezes, plumbing failures, and fast-rising Hill Country floodwater. Recent extreme rainfall has reinforced how quickly the Pedernales River and nearby drainage areas can become dangerous.
Get a free claim review from a licensed Texas public adjuster. There are no upfront fees. Contact TX Public Adjusting before accepting an estimate that may not reflect the full scope of your loss.
Why Property Owners Hire a Public Adjuster in Fredericksburg
An insurance company assigns an adjuster to evaluate the claim on behalf of the carrier. A public adjuster works for the policyholder. Property owners who want a clearer comparison can review the differences between a public adjuster vs. independent adjuster.
That distinction matters when the damage is extensive, the scope is incomplete, the claim has stalled, or the settlement offer does not appear sufficient to complete proper repairs. Property owners often hire a public adjuster in Fredericksburg because they need someone who can evaluate both the physical damage and the insurance paperwork supporting the claim.
A public adjuster may assist by:
- Reviewing the policy and claim documents
- Inspecting the damaged property
- Identifying omitted or overlooked damage
- Preparing a detailed repair scope
- Documenting damaged personal or business property
- Reviewing depreciation calculations
- Comparing contractor findings with the carrier’s estimate
- Communicating with the insurance company
- Preparing and negotiating supplemental claim documentation
- Helping the policyholder understand the status of the claim
Fredericksburg claims can involve more than a standard suburban home. A loss may affect a historic residence near Main Street, a short-term rental, a vineyard facility along the US 290 corridor, a ranch property outside city limits, a bed-and-breakfast, a restaurant, a retail storefront, or a commercial lodging operation. Each property type has different construction details, income considerations, contents, equipment, and repair requirements.
The city is known for its German heritage, locally owned businesses, museums, wineries, and Texas Hill Country setting. More than 150 locally owned stores, boutiques, and galleries operate in the Fredericksburg visitor economy, making commercial interruptions and property losses especially consequential for local owners.
Property Claim Challenges Unique to Fredericksburg
Fredericksburg is not a generic Texas market. The city has a distinctive inventory of properties, including older structures, limestone construction, standing-seam metal roofing, ranch improvements, hospitality businesses, tasting rooms, historic storefronts, and homes used partly or entirely as vacation rentals.
These features can complicate an insurance claim.
Historic and Older Buildings
Older Fredericksburg properties may contain plaster, custom millwork, original masonry, uncommon framing, aged electrical systems, specialty windows, and materials that are difficult to match. An estimate based on standard modern construction may not account for the labor and materials required to restore a historic or architecturally distinctive property.
Repairs may also uncover hidden conditions. Water entering through a damaged roof can travel behind stone veneer, soak insulation, stain interior finishes, and affect wood framing before visible symptoms appear.
Wineries, Tasting Rooms, and Hospitality Properties
The Fredericksburg area’s wineries, tasting rooms, inns, restaurants, event venues, and vacation rentals can sustain losses beyond physical building damage. A storm or fire may also affect:
- Refrigeration and temperature-control equipment
- Wine inventory and stored products
- Commercial kitchens
- Guest furnishings
- Point-of-sale systems
- Outdoor event areas
- Signage and landscaping
- Reservations and business income
- Extra expenses required to continue operating
Commercial claims require careful documentation. Damage to the building is only one component of the potential loss.
Ranches and Rural Properties
Properties outside central Fredericksburg may include barns, workshops, fences, gates, wells, pumps, equipment shelters, guest houses, detached garages, and agricultural improvements. Policy language may classify or limit these structures differently. A detailed claim review should identify which property is insured, what coverage applies, and whether the carrier’s inspection included every affected structure.
Short-Term Rentals and Second Homes
Fredericksburg has a strong tourism economy and a substantial number of lodging properties. Owners who live outside Gillespie County may not discover leaks or storm damage immediately. Delayed discovery can make the timeline, mitigation records, maintenance history, and cause-of-loss documentation especially important.
Common Insurance Claims in Fredericksburg
Hail Damage Claims
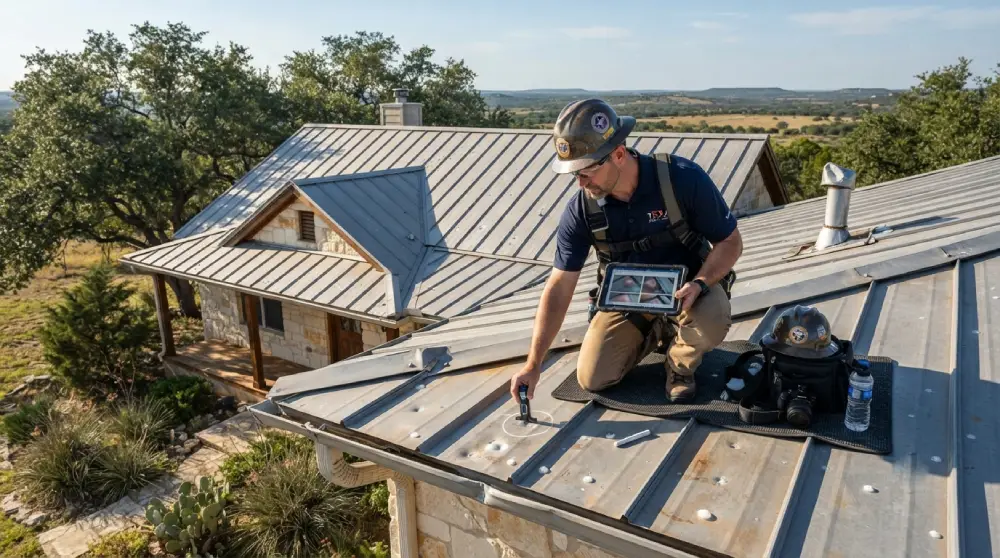
Hail is one of the most common causes of disputed roof claims across Central Texas and the Hill Country. Our guide to filing a hail damage insurance claim explains how roof damage should be identified and documented. A storm can damage asphalt shingles, metal panels, vents, gutters, skylights, exterior lighting, window screens, fencing, and rooftop equipment.
The damage does not always create an immediate leak. Hail may fracture a shingle mat, loosen granules, dent a metal roofing system, damage seams, or compromise roof accessories. Carriers sometimes identify only isolated repairs even when matching, repairability, or widespread impacts should be evaluated.
A Fredericksburg hail damage claim should document:
- Roof covering damage
- Soft-metal impacts
- Gutters and downspouts
- Flashing and vents
- Skylights
- HVAC components
- Windows and screens
- Siding or exterior finishes
- Detached buildings
- Interior water intrusion
Water Damage Claims
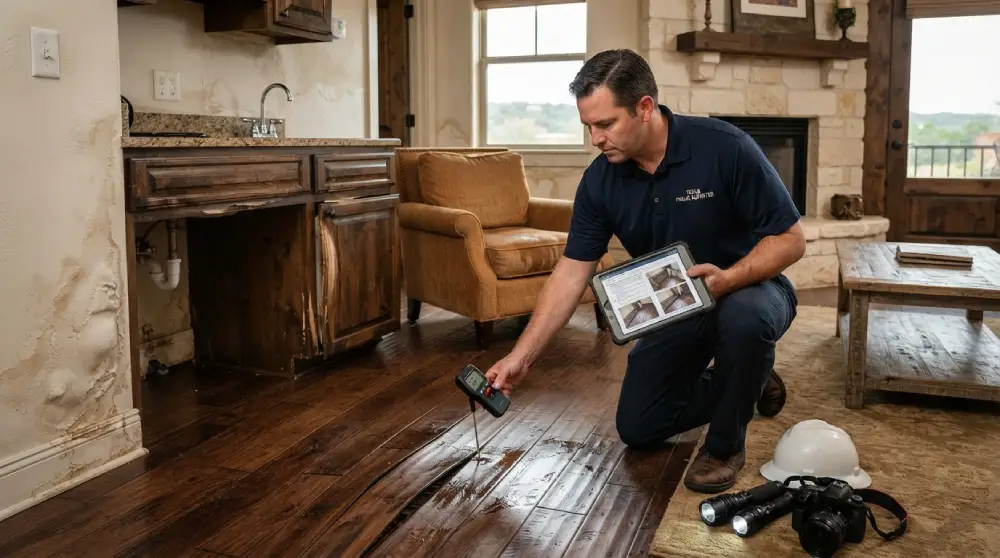
Water damage can begin with a failed supply line, leaking appliance, plumbing backup, roof opening, burst pipe, HVAC drain issue, or hidden leak. The visible water is often only part of the loss, which is why dealing with an insurance adjuster after water damage requires careful documentation of both visible and concealed damage.
Moisture can spread under flooring, behind cabinets, into insulation, beneath baseboards, and through wall cavities. If the initial scope does not include proper drying, removal, access, testing, and reconstruction, the insurance estimate may fall short.
Water claims in Fredericksburg may involve:
- Hardwood or engineered flooring
- Tile assemblies
- Cabinets and countertops
- Drywall and insulation
- Interior stone or masonry
- Electrical components
- Contents and furnishings
- Mold-related concerns
- Temporary lodging or loss-of-use expenses
- Business interruption
Fire and Smoke Damage Claims
A fire damage insurance claim may include structural damage, smoke residue, soot, heat damage, water from firefighting efforts, damaged contents, debris removal, odor remediation, and temporary relocation expenses.
Smoke can travel into rooms that were not directly touched by flames. Porous materials, HVAC systems, insulation, furniture, fabrics, and electronics may require specialized evaluation. Cleaning alone is not always enough.
For commercial properties, the claim may also involve inventory, equipment, tenant improvements, lost revenue, and extra operating expenses.
Storm and Wind Damage Claims
Fredericksburg thunderstorms can produce damaging wind, hail, lightning, and intense rainfall. Wind may lift shingles, separate roof components, damage metal panels, break tree limbs, topple fencing, and allow rain into the building. Property owners dealing with widespread storm losses may also find the guide to property damage after a hurricane useful because it covers roof, interior, structural, equipment, and water-related damage documentation.
Wind-driven rain claims can become disputed when the carrier focuses on the water entry but questions the storm-created opening. Photographs, weather information, roof conditions, interior moisture patterns, and contractor observations can be critical.
Roof Damage Claims
A public adjuster for a roof claim may identify situations where the insurance estimate treats the damage as a small repair without addressing the full roofing system.
Potentially omitted items include:
- Underlayment
- Flashing
- Drip edge
- Ridge materials
- Valley components
- Pipe jacks and vents
- Skylight work
- Solar panel removal and reset
- Gutters
- Interior repairs
- Steep- or high-roof labor
- Debris removal
- Access requirements
- Code-related work when covered
Fredericksburg properties may have asphalt shingles, tile, standing-seam metal, exposed-fastener metal, low-slope commercial roofing, or mixed roof systems. Each material requires a different inspection and repair analysis.
Commercial Property Claims
Commercial claims often involve several layers of loss at once. A winery, hotel, retail building, restaurant, warehouse, office, church, or multifamily property may experience building damage, contents loss, equipment failure, lost income, and extra expenses after one event. When large quantities of furnishings, equipment, merchandise, or stored products are affected, an inventory specialist in Texas may help organize and document the contents portion of the loss.
TX Public Adjusting assists commercial policyholders with documenting the physical scope and organizing the records needed to support the claim.
Fredericksburg Storm and Property-Damage Risks
Flash Flooding and Rapid Runoff
The Texas Hill Country is known for rapid runoff. Hard, dry ground, limestone terrain, creeks, low-water crossings, and intense rainfall can combine to produce dangerous flash flooding with limited warning.
In July 2026, a flash flood emergency affected Gillespie and Blanco counties, including Fredericksburg, Stonewall, and Luckenbach. Reports described 8 to 14 inches of rain in parts of the region and a sharp rise along the Pedernales River.
For property owners, flood and water claims require careful cause-of-loss analysis. Standard property policies often distinguish between water entering from above, plumbing failures, backups, surface water, and river or creek flooding. Coverage depends on the policy and the actual source of the water.
Damage may include:
- Foundation or slab impacts
- Saturated drywall and insulation
- Flooring failure
- Damaged electrical systems
- HVAC contamination
- Contents loss
- Erosion
- Septic or well-system damage
- Damage to retaining walls, fences, and outbuildings
Hail and Severe Thunderstorms
Spring and early summer storms can bring hail, lightning, damaging gusts, and intense rainfall. Hail damage is particularly important for properties with metal roofs because cosmetic-damage exclusions, functional-damage disputes, panel availability, seam conditions, and repairability may affect the claim.
Wildfire and Grass-Fire Conditions
Dry vegetation, heat, wind, and rural acreage can increase wildfire and grass-fire exposure around Gillespie County. Even when flames do not reach the main building, smoke, ash, radiant heat, utility interruption, fencing damage, and debris may create a claim.
Freeze and Burst-Pipe Losses
Hill Country winters are generally milder than those in North Texas, but hard freezes can still damage exposed plumbing, outdoor lines, wells, pumps, irrigation systems, and pipes in unheated areas. A burst pipe can release water for hours if the property is vacant or used as a second home.
Tree, Limb, and Wind Damage
Large trees contribute to the Hill Country landscape but can damage roofs, porches, vehicles, fences, utility connections, and detached structures during high winds. The resulting claim may involve emergency tree removal, temporary roof protection, structural repairs, and water mitigation.
Why Insurance Claims Become Underpaid
An underpaid claim does not always begin with an outright denial. It often begins with an incomplete inspection or a scope that captures only the most visible damage.
Missed Damage
A fast inspection may overlook secondary rooms, detached structures, roof accessories, attic conditions, exterior components, or moisture hidden behind finishes.
Scope Omissions
The carrier’s estimate may acknowledge the damaged roof or wall but omit the work required to complete the repair. That can include removal, access, protection, disposal, detachment and reset, matching materials, specialized labor, or reconstruction of adjacent components.
Depreciation Issues
Insurance estimates may apply depreciation to roofing, finishes, contents, or other property. Recoverable depreciation may require proof that work was completed and costs were incurred. Nonrecoverable depreciation and actual-cash-value provisions can also affect the payment.
Low Unit Prices or Labor Allowances
The estimate may use labor rates, material costs, or repair assumptions that do not reflect the actual work needed in Fredericksburg. Specialty stone, custom finishes, metal roof systems, historic materials, rural access, and busy post-storm markets can affect repair costs.
Documentation Problems
Claims become harder to prove when damaged materials are discarded too early, photographs are incomplete, emergency work is undocumented, or invoices do not clearly describe what was performed. Reviewing the most common property insurance claim mistakes can help owners avoid documentation and communication problems that weaken an otherwise valid claim.
Cause-of-Loss Disputes
The carrier may attribute damage to age, deterioration, wear, faulty installation, maintenance, or a prior condition instead of the reported storm or covered event. A detailed inspection and supporting evidence can help clarify the difference between preexisting conditions and event-related damage.
Our Public Adjusting Process
1. Claim Review
We begin by reviewing the reported loss, available policy information, carrier correspondence, estimates, payments, photographs, and contractor documentation.
The goal is to determine what has already been accepted, what remains disputed, and which parts of the claim need further investigation.
2. Property Inspection
We inspect the affected property and document visible damage. Depending on the claim, this may include roofing, exterior elevations, interior rooms, contents, detached structures, commercial equipment, and areas where moisture may have traveled.
3. Documentation and Scope Preparation
We organize the evidence needed to present the claim. That may include photographs, measurements, inventories, estimates, invoices, mitigation records, repair proposals, expert findings, and a detailed damage scope.
4. Claim Presentation and Negotiation
We submit and discuss the documented scope with the insurance company. When the carrier’s estimate excludes necessary work, we identify the disputed items and provide supporting information.
5. Settlement and Claim Resolution
We continue working through the adjustment process until the covered scope and claim valuation have been addressed. The final outcome depends on the policy, facts, documentation, coverage decisions, and negotiations.
When Should You Contact a Fredericksburg Public Adjuster?
A property owner may contact TX Public Adjusting at the beginning of a claim or after problems develop. Even after a payment or denial, it may not be too late to hire a public adjuster, depending on the policy, deadlines, prior claim activity, and whether a release was signed.
Consider requesting a free claim review when:
- The loss is large or affects several parts of the property
- The insurance estimate appears too low
- Important damage was omitted
- The claim was partially denied
- The carrier attributes storm damage to wear or age
- The roof scope allows only spot repairs
- The claim has been delayed
- You are overwhelmed by documentation requests
- Your commercial property has lost income
- A prior payment is not enough to complete repairs
- You are unsure whether it is too late to reopen or supplement the claim
A low estimate does not necessarily mean the claim is finished. TX Public Adjusting can review the documents and explain whether additional claim work may be appropriate.
Why Choose TX Public Adjusting?
Licensed Texas Representation
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839.
We Represent Policyholders
Insurance-company adjusters work for the carrier. Public adjusters represent insured property owners during the claim process.
Texas-Focused Claim Experience
Our work is focused on Texas property losses, including hail, wind, roof, water, fire, freeze, and commercial damage claims.
Residential and Commercial Expertise
We assist homeowners, landlords, investors, business owners, hospitality operators, associations, and commercial property owners.
Detailed Claim Documentation
A claim should be supported by more than a general description of the damage. We focus on the repair scope, measurements, photographs, estimates, inventories, invoices, and supporting records needed to explain the loss.
Experience Reviewing Thousands of Claims
Our team has reviewed thousands of residential and commercial claims. That experience helps us recognize recurring estimating gaps, missing line items, incomplete inspections, depreciation concerns, and documentation problems without inventing outcomes or promising a particular settlement.
Free Claim Review
Property owners can speak with TX Public Adjusting before deciding whether to hire a public adjuster. There are no upfront fees for the initial claim review.
Fredericksburg Neighborhoods and Areas We Serve
TX Public Adjusting serves property owners throughout Fredericksburg and Gillespie County, including homes, businesses, ranches, lodging properties, and commercial facilities near:
- Downtown Fredericksburg
- The Main Street historic district
- Cross Mountain
- Northwest Fredericksburg
- Northeast Fredericksburg
- South Fredericksburg
- Areas near Lady Bird Johnson Municipal Park
- US 290 winery and vineyard properties
- Harper
- Stonewall
- Doss
- Willow City
- Luckenbach
- Crabapple
- Morris Ranch
- Tivydale
- Cain City
- Rural Gillespie County
We also assist eligible property owners in nearby Hill Country communities, including Kerrville, Comfort, Johnson City, Blanco, Mason, Llano, and Boerne.
Fredericksburg landmarks such as the National Museum of the Pacific War, Marktplatz, the Pioneer Museum, and nearby Enchanted Rock reflect the area’s history and tourism-driven economy. Enchanted Rock is a 425-foot pink granite formation and one of the region’s best-known natural attractions.
Frequently Asked Questions
What does a public adjuster in Fredericksburg do?
A public adjuster represents the policyholder during a property insurance claim. The adjuster reviews the claim, inspects damage, prepares documentation, evaluates the insurance estimate, and negotiates disputed or omitted items with the carrier. Property owners who need a broader explanation can read our guide to what a public adjuster does.
For Fredericksburg property owners, that may include hail damage to a metal roof, water intrusion in a historic home, fire damage at a lodging property, or business-interruption issues at a commercial operation.
How is a public adjuster different from the insurance company’s adjuster?
The insurance company’s adjuster works for the carrier and evaluates the claim under the insurer’s procedures. A public adjuster is hired by the policyholder and advocates for the policyholder’s interests.
Both may inspect the same property, but they represent different parties in the claim.
How much does a public adjuster cost in Fredericksburg?
Public adjusters generally work for a fee based on the claim recovery, subject to the contract and applicable Texas requirements. The exact fee structure should be explained before an agreement is signed.
TX Public Adjusting offers a free claim review and does not charge an upfront fee for that initial evaluation.
Can you help after the insurance company has already paid me?
Possibly. A prior payment does not always mean every covered item was included. Some claims can be supplemented when additional damage, missing work, or inadequate pricing is properly documented.
The available options depend on the policy, deadlines, prior communications, releases, and facts of the claim.
Can a public adjuster help with a denied claim?
A public adjuster can review the denial, policy language, inspection findings, photographs, and cause-of-loss evidence. Some denials involve exclusions or coverage issues, while others involve disputes about what caused the damage.
A review does not guarantee reversal, but it can help determine whether additional documentation or professional assistance is warranted.
Do you handle hail damage to metal roofs?
Yes. Metal roof claims can involve dents, punctures, damaged seams, loosened fasteners, coating damage, displaced panels, and questions about whether the damage is cosmetic or functional.
The policy language and roof system matter. A standing-seam metal roof cannot always be evaluated or repaired the same way as an exposed-fastener agricultural roof.
Can you help with a winery, bed-and-breakfast, or vacation-rental claim?
Yes. We assist with residential and commercial property claims, including hospitality and tourism-related properties.
These claims may involve building repairs, furnishings, equipment, inventory, lost business income, extra expenses, guest relocation, and the cost of reducing additional damage.
Does homeowners insurance cover flood damage in Fredericksburg?
Standard homeowners policies commonly treat rising surface water and river flooding differently from rain entering through storm damage or water released by plumbing. Flood losses may require a separate flood policy.
Because the source of the water matters, property owners should document where the water entered, how it moved through the building, and what other storm damage occurred. Coverage depends on the actual policy and facts.
How long does a Fredericksburg property claim take?
There is no single timeline. A straightforward claim may move faster than a major commercial loss, historic-building claim, fire loss, coverage dispute, or claim requiring engineering and extensive documentation.
Delays can also occur when inspections must be rescheduled, repair scopes differ, documents are incomplete, or severe weather creates a high volume of claims. Texas policyholders can also review general information about how long an insurance adjuster has to contact you after a claim is reported.
Is it too late to hire a public adjuster?
Not always. Policyholders sometimes hire a public adjuster after receiving a low estimate, partial payment, denial, or request for more information.
Deadlines, policy conditions, contractual limitation periods, completed repairs, and signed releases may affect what can still be done. It is better to request a review promptly rather than assume the claim cannot be revisited.
Get a Free Fredericksburg Insurance Claim Review
Property damage can disrupt your home, business, rental income, or daily operations. You should not have to rely on an incomplete estimate or guess whether the carrier included everything needed to repair the property.
TX Public Adjusting helps Fredericksburg policyholders document damage, review insurance estimates, identify scope omissions, and present supported claims to the insurance company.
Contact TX Public Adjusting for a free claim review.
- Licensed Texas Public Adjuster
- Residential and Commercial Claims
- No Upfront Fees
- Independent Policyholder Representation
- Rise Public Adjusting LLC
- Texas License #3356839