Property damage in Rio Grande City can turn into a complicated insurance dispute quickly. Severe thunderstorms can damage roofs, wind can lift flashing and exterior materials, and intense South Texas rainfall can send water into homes and commercial buildings. When the carrier’s estimate does not reflect the full extent of the loss, a public adjuster in Rio Grande City can help document the damage and present the policyholder’s claim.
TX Public Adjusting represents residential and commercial property owners—not insurance companies. Our team reviews policies, inspects damaged property, prepares detailed claim documentation, and negotiates with carriers on behalf of policyholders. We operate through Rise Public Adjusting LLC, Texas License #3356839.
Property owners in Rio Grande City may request a free claim review with no upfront fees. We can evaluate a new claim, an existing claim, or a settlement that appears too low.
Licensed Texas Public Adjuster | Residential and Commercial Claims | Free Claim Review
Insurance Claim Help for Rio Grande City Property Owners
Rio Grande City is the county seat of Starr County and sits in the western portion of the Lower Rio Grande Valley. Its location, climate, development patterns, and mix of historic and newer construction create property-claim issues that differ from those found in Dallas, Houston, or Central Texas.
The area has a hot, semi-arid climate, but periods of extreme rainfall can still produce damaging runoff and flash flooding. Tropical moisture moving inland from the Gulf can also bring heavy rain and strong winds into Deep South Texas. The National Weather Service maintains a dedicated Brownsville/Rio Grande Valley forecast office and publishes hurricane preparedness information for communities across the region.
Rio Grande City also contains historically significant properties near downtown, including Fort Ringgold and the La Borde House. Older masonry, wood-framed structures, historic roofing systems, additions, and renovated commercial buildings may require careful inspection after a storm. Damage to these properties is not always captured accurately in a brief carrier inspection.
A public insurance adjuster can help determine whether the insurance company’s scope accounts for all covered damage, including damage that may not be visible from the ground.
Get a Free Claim Review
Contact TX Public Adjusting before accepting a settlement that does not appear sufficient to complete proper repairs. We can review the carrier’s estimate, photographs, inspection findings, policy language, and other available claim documents.
Why Property Owners Hire a Public Adjuster in Rio Grande City
Insurance companies assign adjusters to investigate claims for the carrier. Those adjusters may be professional and experienced, but they do not serve as the policyholder’s personal representative.
A public adjuster works for the insured property owner. Property owners who want a more detailed explanation can review what a public adjuster does during a residential or commercial insurance claim. The public adjuster’s role is to investigate the loss, prepare the claim, identify covered damage, and communicate with the insurance company regarding the amount owed under the policy.
Rio Grande City homeowners and business owners often seek insurance claim assistance when:
- The insurance estimate appears too low.
- Roof damage was described as cosmetic or caused by wear.
- Interior water damage was omitted from the estimate.
- The carrier paid for isolated repairs instead of a complete repair scope.
- A claim was delayed, disputed, or denied.
- Depreciation was applied incorrectly or not explained clearly.
- The adjuster missed damage to fencing, HVAC equipment, windows, exterior finishes, or detached structures.
- Commercial operations were interrupted after a covered loss.
- The policyholder does not have time to manage inspections, estimates, calls, and documentation.
- Repair bids are substantially higher than the insurer’s estimate.
Hiring a public adjuster does not guarantee a particular settlement. It gives the policyholder an experienced representative whose responsibility is to prepare and pursue the claim from the policyholder’s side.
Storm and Property-Damage Risks in Rio Grande City
Rio Grande City faces a combination of severe-thunderstorm, hail, wind, rainfall, tropical-weather, and extreme-heat risks. Each can create different insurance and repair issues.
Severe Thunderstorms and Hail
Strong thunderstorms in Starr County can produce damaging wind, hail, lightning, and heavy rain. Hail can bruise or fracture roofing materials, dent metal components, damage exterior equipment, crack skylights, and leave impact marks on siding or painted surfaces.
Property owners who discover roof or exterior impacts can review our guide to hail damage insurance claims for information about inspections, carrier estimates, covered repairs, and frequently disputed scope items.
Damage may extend beyond shingles. A complete inspection should also consider:
- Roof vents and flashing
- Gutters and downspouts
- Metal roof panels
- HVAC condenser fins
- Window screens and glazing
- Exterior doors
- Fences and gates
- Stucco and exterior coatings
- Solar equipment
- Detached garages and storage buildings
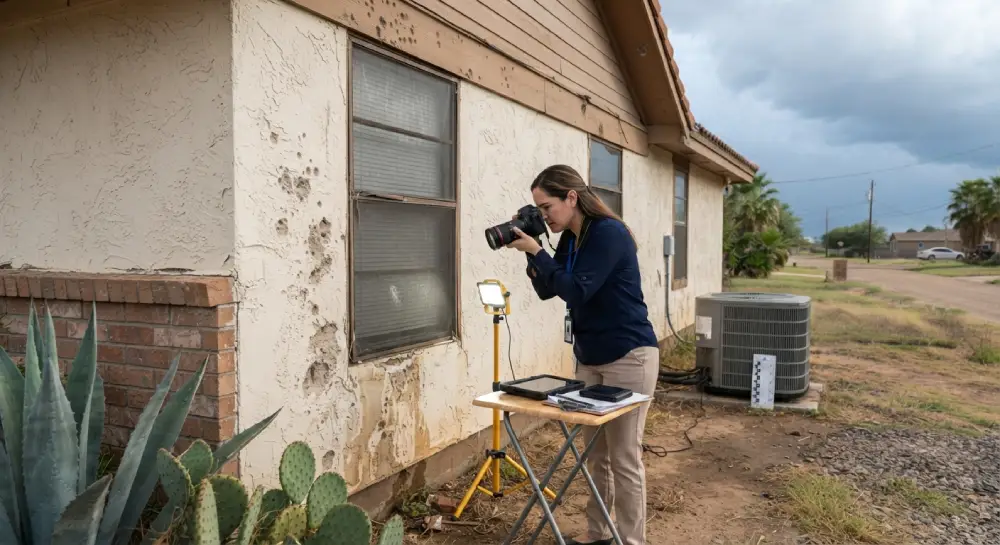
Before temporary repairs begin, take clear photographs of each affected area. Our guide explains how to document hail damage for an insurance claim without placing yourself at risk or disturbing important evidence. After a significant Starr County storm, widespread damage may affect homes, businesses, vehicles, and other property throughout the Rio Grande City area.
Strong Wind and Wind-Driven Rain
Wind damage does not always involve a roof being torn off. Wind can loosen shingles, break seals, lift roof edges, displace flashing, damage parapet walls, and create openings that allow rain to enter.
Water may then travel through insulation, ceilings, walls, electrical areas, or flooring before becoming visible. An estimate that addresses only a ceiling stain may overlook the damaged roof assembly or moisture concealed behind finished surfaces.
Commercial buildings may present additional concerns, including damage to flat roofing, membrane seams, rooftop units, signage, canopies, loading areas, and exterior cladding.
Flash Flooding and Heavy Rain
The Lower Rio Grande Valley can experience high-impact rainfall despite its generally dry climate. A major 2008 event near Roma produced more than 15 inches of rain in some areas, affected nearly 1,000 homes, and required more than 200 evacuations. More recently, severe flooding in the Rio Grande Valley has caused water rescues, power outages, road closures, and major disruption.
Insurance coverage for water depends heavily on where the water originated and what the policy covers. Surface flooding is often treated differently from water entering through a storm-created opening, plumbing failure, roof leak, appliance line, or backed-up drainage system.
Our claim review may examine:
- The reported cause of loss
- Flood-policy and property-policy distinctions
- Wind-created openings
- Roof and exterior damage
- Interior moisture pathways
- Emergency mitigation invoices
- Drying records and moisture readings
- Damaged contents
- Mold-related limitations
- Coverage endorsements and exclusions
Policyholders should avoid assuming that all water damage is excluded simply because the carrier uses the word “flood.” The source and sequence of events matter.
Tropical Systems and Remnant Rainfall
Rio Grande City is inland, but tropical systems affecting the Gulf Coast can still send moisture, thunderstorms, and strong winds into Starr County. Even a weakening tropical system can generate substantial rainfall far from where it first reaches the coast. Our guide to hurricane property damage claims explains how wind, roof openings, water intrusion, fallen debris, and interior damage can interact during a major weather event.
Claims after tropical weather may involve several causes at once: wind damage, roof openings, rain intrusion, fallen trees, power interruptions, and surface water. Separating covered and excluded damage may require detailed documentation.
Heat-Related Roof Deterioration
Extreme South Texas heat places continuous stress on roofing materials. High temperatures and intense sunlight can accelerate aging, sealant failure, membrane deterioration, and thermal movement.
Heat damage itself may not be covered, but pre-existing deterioration is frequently raised during a storm claim. A careful inspection helps distinguish long-term wear from new storm-related impacts. That distinction can become central when an insurer attributes hail or wind damage to age alone.
Common Insurance Claims in Rio Grande City
Hail Damage Claims
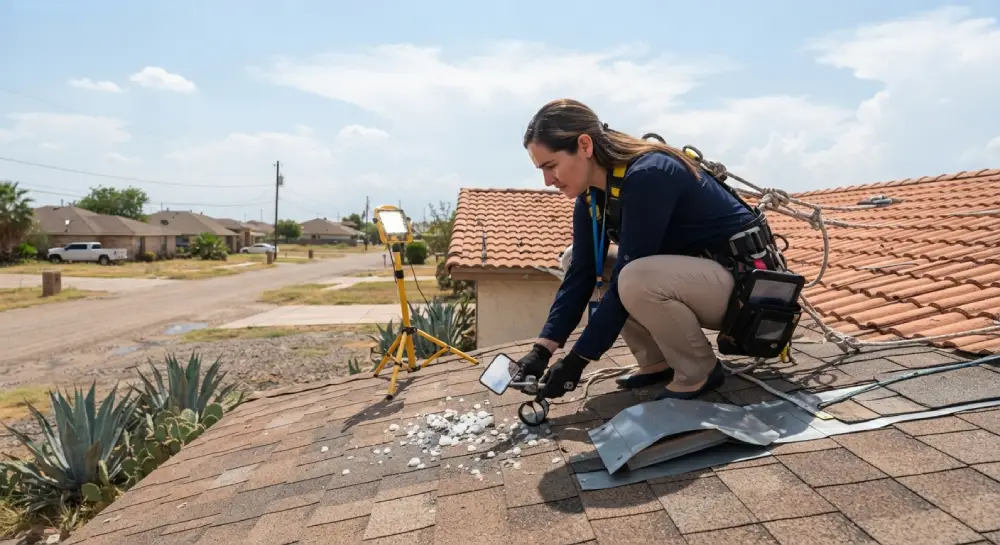
Hail claims can be difficult because damage may look minor from the ground. Impact marks can reduce the life of shingles, damage metal roofing, compromise coatings, or affect rooftop equipment.
The carrier may approve replacement of a few components while omitting adjacent materials, matching issues, code-related work, labor access, or damage across multiple slopes. TX Public Adjusting reviews the entire scope rather than focusing only on the most obvious impact areas.
Water Damage Claims
A water damage insurance claim may arise from a storm-created opening, plumbing failure, appliance leak, air-conditioning system, roof leak, or another covered event. Coverage usually depends on the source of the water, the sequence of events, the resulting damage, and the policy language.
A proper scope may need to include more than drying and paint. Depending on the loss, repairs could involve insulation, drywall, cabinetry, flooring, trim, electrical components, personal property, and microbial remediation.
Fire and Smoke Damage Claims
A fire claim can involve structural damage, smoke contamination, soot, water from firefighting efforts, debris removal, temporary housing, damaged contents, and code requirements. A fire insurance adjuster representing the policyholder can help organize these separate portions of the loss and identify items omitted from the carrier’s scope.
Smoke can travel into rooms that were not directly touched by flames. HVAC systems may distribute contamination throughout a building. Commercial losses may also involve inventory, equipment, tenant improvements, and interruption of operations.
Storm Damage Claims
A storm claim may combine hail, wind, rain, falling objects, broken windows, roof damage, and power-related losses. When several causes occur together, documentation must establish what happened and connect each damaged area to the event.
Roof Damage Claims
Roof claims are among the most frequently disputed property claims. When the carrier and property owner disagree about the necessary repair method, a public adjuster for a roof claim can compare the insurer’s scope with the roof conditions, policy provisions, measurements, contractor findings, and applicable repair requirements. Common disagreements include:
- Repair versus replacement
- Storm damage versus wear
- Number of damaged slopes
- Matching of existing materials
- Underlayment and decking
- Flashing and ventilation
- Labor and access requirements
- Code-required upgrades
- Overhead and profit
- Damage to rooftop equipment
An insurance estimate should be compared with the actual conditions, repair requirements, policy terms, and contractor findings.
Commercial Property Claims
Rio Grande City serves as an economic and governmental center for Starr County. Commercial claims may involve retail buildings, offices, medical facilities, restaurants, warehouses, apartment properties, churches, schools, and mixed-use buildings.
A commercial loss can affect more than the building. The claim may include equipment, inventory, tenant improvements, signage, cleanup, temporary relocation, extra expenses, or business-income coverage.
Our commercial public adjuster services help business owners, property managers, investors, and other decision-makers organize the claim and reduce the administrative burden placed on the insured.
Why Rio Grande City Insurance Claims Become Underpaid
A claim may be underpaid because the inspection was rushed, the scope was incomplete, or supporting information was never submitted. In other situations, the disagreement concerns coverage, pricing, depreciation, causation, or the repair method.
Missed or Hidden Damage
Some damage is visible only from the roof, attic, interior wall cavity, or equipment platform. Moisture can also travel away from the original opening.
A surface-level inspection may miss:
- Wet insulation
- Roof-deck damage
- Moisture behind drywall
- Damage beneath flooring
- Compromised flashing
- Interior contents damage
- Mechanical-system damage
- Secondary damage in adjacent rooms
Scope Omissions
An insurer may acknowledge the claim but leave necessary items out of the estimate. These omissions can create a substantial gap between the insurance payment and the actual repair cost.
Commonly omitted items include demolition, debris removal, material manipulation, detach-and-reset work, access, permits, code upgrades, matching materials, and protection of unaffected areas.
Depreciation Problems
Replacement-cost policies may allow the carrier to withhold recoverable depreciation until repairs are completed and documentation is provided. Problems arise when depreciation is excessive, incorrectly categorized, or applied to items that should not have been depreciated in the same manner.
Policyholders should understand which amounts were paid, which were withheld, and what must be submitted to recover additional benefits.
Low Estimates
Carrier estimates may use measurements, quantities, labor assumptions, or repair methods that differ from the conditions at the property. A contractor’s price being higher does not automatically prove the carrier is wrong, but a large discrepancy should be investigated.
Documentation Gaps
Claims depend on evidence. Missing photographs, incomplete inventories, unclear invoices, limited moisture records, and inconsistent descriptions are among the common property insurance claim mistakes that can weaken an otherwise valid claim.
TX Public Adjusting helps organize the file so the carrier receives a clear presentation of the damage and requested amount.
Our Public Adjusting Process
1. Claim Review
We begin by reviewing the available policy, carrier correspondence, estimates, photographs, proof-of-loss documents, repair bids, and claim history.
We identify unresolved questions and explain the next steps to the property owner.
2. Property Inspection
We inspect the reported damage and look for related conditions that may have been missed. The inspection may include roofing, exterior elevations, interiors, detached structures, contents, and commercial equipment when relevant.
3. Documentation and Scope Preparation
We document the loss using photographs, measurements, inventories, reports, estimates, and supporting records. The objective is to prepare a complete, organized claim presentation.
4. Carrier Communication and Negotiation
We communicate with the insurance company, respond to claim questions, participate in inspections when appropriate, and present support for disputed or omitted items.
5. Claim Resolution
We work to resolve the documented differences within the available policy coverage and claim process. Every claim is different, and results depend on the facts, evidence, policy terms, and carrier decisions.
Mid-Claim Help Is Available
You do not necessarily need to hire a public adjuster on the first day of a claim. However, deadlines, completed repairs, discarded materials, signed releases, and lost evidence can affect the available options. Read more about when it is too late to hire a public adjuster before delaying a review of an underpaid or disputed claim. TX Public Adjusting may be able to assist after an inspection, after the first estimate, or after a low settlement offer.
Contact us promptly if:
- Repairs cannot be completed for the amount paid.
- The carrier has stopped responding.
- Important damage was omitted.
- Your roof claim was denied as wear and tear.
- You disagree with the cause-of-loss decision.
- A commercial claim is disrupting normal operations.
A free claim review can help determine whether professional representation makes sense.
Why Choose TX Public Adjusting
Texas-Focused Claim Experience
Our work is centered on Texas property claims. We understand the effect of hail, windstorms, tropical weather, extreme rainfall, fire, plumbing failures, and commercial losses across the state.
Licensed Representation
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839.
Independent Policyholder Representation
We represent policyholders. We do not work for the insurance carrier assigned to evaluate the claim. Our guide comparing a public adjuster vs. independent adjuster explains who each adjuster represents and how their responsibilities differ.
Residential and Commercial Expertise
Our team reviews both residential and commercial losses. We understand that a homeowner’s needs differ from those of a commercial property owner managing tenants, inventory, equipment, or interrupted operations.
Thousands of Claims Reviewed
Our experience includes the review of thousands of property claims involving roofing, water, fire, storm, and commercial damage. That experience helps us recognize scope issues, documentation gaps, and claim disputes that property owners may not notice.
Organized Claim Management
Insurance claims generate estimates, reports, invoices, emails, photographs, and deadlines. We help organize the process and serve as a central point of communication for the claim.
Areas We Serve Near Rio Grande City
TX Public Adjusting assists property owners throughout Rio Grande City and surrounding Starr County communities.
Our service area includes properties in and near:
- Historic Downtown Rio Grande City
- Fort Ringgold
- Las Lomas
- El Refugio
- La Grulla
- Garciasville
- Alto Bonito
- Los Alvarez
- Escobares
- Roma
- Sullivan City
- Falcon Heights
- Fronton
- La Rosita
- Santa Cruz
- Rural Starr County
Property owners west of Rio Grande City can also learn about claim assistance from our public adjuster in Roma. We serve properties throughout Starr County based on the location, type, and circumstances of the loss. We also assist property owners across the Rio Grande Valley when the location and claim fall within our service capabilities.
The Rio Grande City area includes historic buildings, established residential neighborhoods, newer subdivisions, ranch properties, retail corridors, and commercial facilities. Each type of property requires a claim strategy suited to its construction, use, and damage.
Frequently Asked Questions
How much does a public adjuster cost in Rio Grande City?
Public adjusters commonly work on a contingency basis, meaning the fee is tied to the insurance proceeds recovered through their work. The exact fee and terms should be stated clearly in the written contract.
TX Public Adjusting offers a free initial claim review and does not require an upfront fee for that review. We explain the compensation structure before representation begins.
When should I hire a public adjuster after property damage?
Consider contacting a public adjuster when the damage is extensive, the claim involves several areas of the property, the carrier’s estimate appears too low, or the cause of damage is being disputed.
You may also seek help after receiving an initial payment. The best time depends on the claim, but waiting too long can make documentation and deadline issues more difficult.
Can a public adjuster help with a denied roof claim?
A public adjuster can review the denial, policy language, carrier inspection, roof conditions, photographs, and contractor findings. The purpose is to determine whether the claim has additional support or whether damage was incorrectly attributed to age, maintenance, or wear.
A denial cannot always be reversed. The available evidence and policy terms control what options remain.
Does homeowners insurance cover flood damage in Rio Grande City?
Standard homeowners policies commonly treat surface flooding differently from water damage caused by a covered opening or an internal plumbing event. Separate flood insurance may be required for rising surface water.
Because water claims depend on the source, sequence, and policy wording, property owners should have the facts reviewed before accepting a broad statement that all water damage is excluded.
Can you help after the insurance company has already paid?
Yes. A claim may still be reviewable after the first payment if damage was missed, the estimate is incomplete, or additional documentation supports a supplement.
The policy, deadlines, signed documents, repair status, and claim history must be reviewed before determining what can be done.
What does a public adjuster inspect after a hailstorm?
The inspection may include shingles, metal roofing, flashing, vents, gutters, windows, screens, exterior finishes, fences, HVAC equipment, detached structures, and interior areas affected by water intrusion.
The specific inspection depends on the property and reported storm conditions.
Do public adjusters work on commercial claims?
Yes. TX Public Adjusting handles residential and commercial property claims. Commercial claims may include buildings, tenant improvements, inventory, equipment, extra expenses, and business interruption when those coverages apply.
Commercial losses often produce large document files and require coordination among owners, managers, contractors, accountants, tenants, and the insurer.
Can I hire a public adjuster for water damage?
Yes. Public adjusters assist with covered water losses involving plumbing failures, roof openings, appliances, air-conditioning systems, and other causes.
The adjuster can document affected materials, evaluate the carrier’s scope, review mitigation records, and present support for omitted damage.
How long does a Rio Grande City insurance claim take?
There is no single timeline. A straightforward claim with clear coverage and complete documentation may resolve more quickly than a large commercial loss or a claim involving disputed causation.
The size of the loss, carrier response times, inspections, requested documents, repairs, supplements, and policy deadlines can all affect the duration.
Is TX Public Adjusting part of my insurance company?
No. TX Public Adjusting represents policyholders through Rise Public Adjusting LLC. We are independent of the insurance carrier and work for the property owner under a written agreement.
That distinction is central to public adjusting: the insurance company has its representatives, and the policyholder may choose to retain a licensed representative of their own.
Request a Free Rio Grande City Claim Review
A damaged property is stressful enough without trying to interpret a long policy, prepare a detailed estimate, document every loss, and negotiate disputed items alone.
TX Public Adjusting helps Rio Grande City homeowners, landlords, investors, business owners, and commercial property managers prepare and pursue property insurance claims.
Contact us when:
- Your claim was denied.
- Your payment is lower than the repair estimates.
- Storm damage was missed.
- Water entered the property.
- Your roof claim is disputed.
- Your commercial property cannot operate normally.
- You need help documenting a major loss.
Request a free claim review from TX Public Adjusting today. There are no upfront fees for the initial review, and we can evaluate a new, underpaid, delayed, or denied Rio Grande City property claim.
Rise Public Adjusting LLC
Texas License #3356839
Serving Rio Grande City, Starr County, and property owners throughout Texas