

Property damage in Oakhurst can turn into an insurance dispute quickly, especially when wind, hail, falling tree limbs, roof damage, or water intrusion affects a rural or wooded property. If the insurance company’s estimate does not reflect the damage you can see—or the damage that may be hidden beneath the surface—working with a Public Adjuster in Oakhurst, TX gives you independent representation during the claim.
TX Public Adjusting represents homeowners, business owners, landlords, and other policyholders throughout Texas. We inspect property damage, document the loss, review the insurance company’s scope and estimate, and negotiate the claim from the policyholder’s side.
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839. We do not work for the insurance company. Our responsibility is to the property owner.
Need help with an Oakhurst property damage claim? Request a Free Claim Review from TX Public Adjusting. There are no upfront fees to have us review your claim situation.
Oakhurst is a small census-designated community in northern San Jacinto County, centered near the intersection of U.S. Highway 190 and FM 946. Its wooded Piney Woods setting is an important part of the community’s identity—the Texas State Historical Association notes that the community was named for its location on a wooded hill in a grove of oaks.
Why Property Owners Hire a Public Adjuster in Oakhurst
Insurance companies send adjusters to investigate claims, but those adjusters are working within the insurer’s claim-handling process. A public adjuster serves a different role: representing the policyholder and building the property owner’s claim.
That distinction can matter in Oakhurst because storm damage is not always limited to one obvious problem.
A thunderstorm may leave visible shingle damage while also affecting ridge caps, flashing, gutters, vents, siding, fencing, detached structures, or interior finishes. A fallen branch may create a roof opening that allows rainwater into insulation and ceilings. A burst plumbing line may damage flooring, cabinetry, drywall, and contents beyond the immediately visible wet area.
Our job is to determine whether the insurance company’s scope reflects the actual covered loss.
Property owners commonly contact TX Public Adjusting when:
- The insurance payment appears too low to complete repairs.
- The carrier inspected the property but omitted damaged components.
- A roof claim was limited to small repairs rather than the broader damage observed.
- Depreciation substantially reduced the initial payment.
- Interior water damage was not fully included.
- A claim has become delayed or difficult to manage.
- The property owner disagrees with the carrier’s measurements or estimate.
- A residential or commercial claim involves multiple trades and repair categories.
- A previously closed or underpaid claim deserves another review.
For larger claims, getting the scope right early can make a significant difference in how efficiently the loss is documented and presented.
Property Damage Risks Around Oakhurst and San Jacinto County
Oakhurst does not have the same storm profile as a dense North Texas suburb or a coastal community directly on the Gulf. Its location in the wooded Piney Woods north of Houston creates its own set of property-loss concerns.
That local distinction matters.
Severe Thunderstorms, Wind, and Hail
Strong thunderstorms are a real Oakhurst claim risk rather than a generic Texas talking point.
In July 2026 alone, National Weather Service Houston/Galveston statements specifically named Oakhurst among locations affected by strong thunderstorms. A July 5 statement warned of wind gusts up to 40 mph and half-inch hail near Oakhurst and Point Blank. Another statement on July 22 included Oakhurst in an area where storms were capable of wind gusts up to 50 mph and hail.
Even when hailstones are not exceptionally large, wind-driven storms can affect:
- Asphalt shingles
- Metal roofing and soft metals
- Ridge caps
- Gutters and downspouts
- Roof vents and flashing
- Exterior siding
- Window screens
- Fences
- Detached garages and sheds
- HVAC components
After a storm, a quick look from the ground does not necessarily reveal the full condition of the roofing system. Property owners should carefully document hail damage for an insurance claim before repairs or weathering make the original conditions harder to establish.
Falling Trees and Tree Limbs
Oakhurst’s wooded character is one of the reasons people value the area, but mature trees also introduce a claim issue that is less prominent in heavily developed neighborhoods.
High winds can break branches or topple trees onto roofs, garages, fences, outbuildings, vehicles, and utility connections. Even when a limb does not penetrate the roof deck, impact can damage shingles, decking, flashing, or structural components.
A tree-impact claim may therefore involve more than tree removal. The underlying building damage needs to be documented separately and carefully.
Wind-Driven Rain and Interior Water Damage
Wind and roof damage often lead to a second problem: water intrusion.
Water can enter around damaged shingles, vents, flashing, windows, doors, or other openings and then migrate away from the original entry point. Interior staining may appear in a different room or several feet from the roof damage.
A proper claim review may include:
- Attic conditions
- Insulation
- Ceiling drywall
- Wall finishes
- Flooring
- Trim
- Cabinetry
- Electrical components when affected
- Moisture-related mitigation work
This is particularly relevant after thunderstorms that combine strong winds with heavy rainfall.
Tropical Systems and Inland Storm Effects
Oakhurst is well inland from the immediate Texas coast, but tropical systems can still bring damaging wind and prolonged rainfall into Southeast Texas.
For property owners, the important question is not simply whether a storm was officially a hurricane when it reached Oakhurst. The claim must focus on the cause of the actual property damage and the coverage provided by the policy.
Wind-created openings, roof damage, falling trees, wind-driven rain, and other storm effects can require separate documentation from rising surface water or flooding.
Water and Flooding Require Careful Cause Analysis
Oakhurst is part of the broader Lake Livingston and San Jacinto County region. Lake Livingston itself extends through San Jacinto, Polk, Trinity, and Walker counties, and nearby communities are shaped by lakes, creeks, drainage areas, and wooded terrain.
Property owners should not assume every form of “water damage” is treated the same under an insurance policy.
A plumbing leak, wind-driven rain event, roof leak caused by covered storm damage, appliance discharge, or other sudden interior water loss may involve different coverage provisions from rising floodwater. Flood losses are commonly handled under separate flood coverage rather than a standard property policy.
Determining the cause of loss is therefore one of the first things we examine.
Common Insurance Claims in Oakhurst
Hail Damage Claims
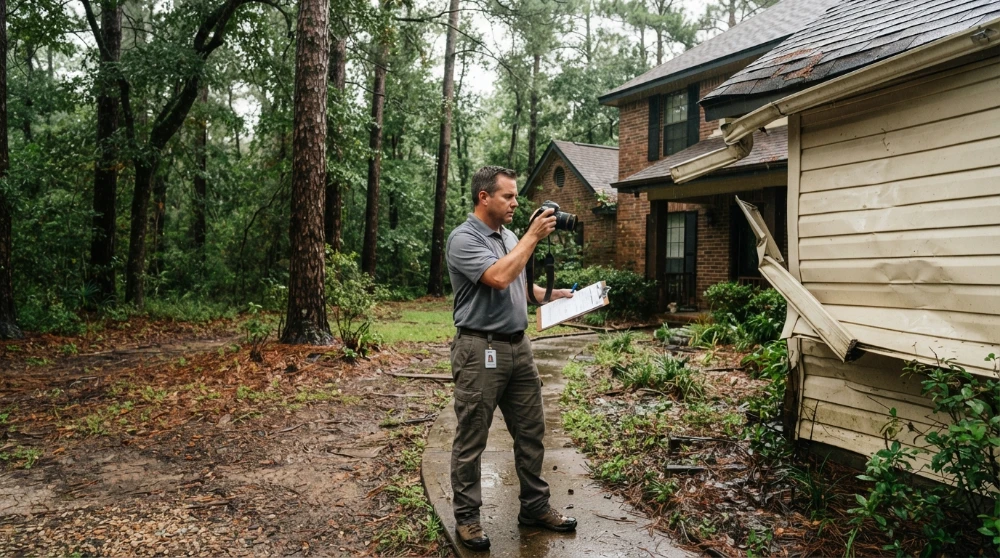
Hail damage can affect far more than shingles. Depending on the storm and building materials, we may inspect roofing, gutters, vents, flashing, metal components, siding, screens, HVAC equipment, and other exterior surfaces.
When the insurance carrier’s estimate addresses only part of the damage, the claim may need a more complete scope. Property owners dealing with a hail damage roof insurance claim should document both the roofing system and related exterior components before assuming the carrier’s first estimate includes everything. If the carrier has already rejected the loss, review what to do if your hail claim was denied before assuming the insurance company’s first decision is the end of the process.
Water Damage Claims
Water claims can become complicated because damage spreads. A water damage public adjuster can help document the affected areas when a covered leak, plumbing failure, or storm-related opening causes damage beyond the immediately visible wet area.
A small plumbing failure can affect drywall, flooring, cabinets, insulation, baseboards, personal property, and adjacent rooms. After emergency mitigation, disagreements may also arise over what needs to be removed, dried, repaired, or replaced.
We help organize the documentation so that the claim reflects the complete affected area rather than only the most visible damage.
Fire and Smoke Damage Claims
A structure fire can involve direct burn damage, smoke residue, soot, odor, water from firefighting efforts, contents, electrical systems, temporary housing expenses, and debris removal.
These claims can be documentation-heavy. For a substantial structure loss, working with a fire insurance adjuster who represents the policyholder can help organize building damage, contents, smoke, debris removal, and other parts of the loss. A careful inventory and detailed repair scope become especially important when numerous rooms or categories of personal property are involved.
Storm Damage Claims
For an Oakhurst property, storm damage may involve several causes at once: wind, hail, tree impact, roof openings, and subsequent rainwater intrusion.
Rather than treating each visible symptom in isolation, we document how the storm affected the property as a whole.
Roof Damage Claims
Roof disputes are among the most common reasons property owners seek independent claim help.
An insurer may determine that only a limited repair is necessary. The homeowner or contractor may identify additional damaged slopes, components, accessories, or related interior damage. If the carrier’s estimate does not match the damage observed at the property, a public adjuster for a roof claim can review the scope, measurements, damaged components, and related interior loss.
Our review considers the carrier estimate alongside the physical conditions observed at the property.
Commercial Property Claims
Commercial insurance losses often involve more moving parts than residential claims.
Businesses, churches, rental properties, storage facilities, offices, agricultural buildings, restaurants, and other commercial properties may have specialized roofing systems, equipment, inventory, tenant considerations, or business-use areas.
TX Public Adjusting handles both residential and commercial property claims in Oakhurst and throughout Texas.
A Local Claim Approach for Oakhurst Properties
Oakhurst is not a large urban community divided into dozens of named neighborhoods. That is precisely why a locally written claim page should not pretend otherwise.
The community is rural and wooded, with properties concentrated around U.S. 190, FM 946, and surrounding county roads. Nearby Lake Livingston communities include Waterwood and its Whispering Pines sections, while Point Blank and Forest Cove sit toward the lake. Waterwood is a large wooded residential development associated with the Lake Livingston area, and Forest Cove describes itself as a wooded lakeside subdivision in San Jacinto County.
That mix means an Oakhurst-area claim may involve:
| Property characteristic | Potential claim concern |
| Wooded acreage | Tree and limb impact after high winds |
| Asphalt or metal roofing | Wind, hail, flashing, vent, and penetration damage |
| Detached buildings | Sheds, workshops, garages, and ancillary structures omitted from scope |
| Rural properties | Fencing, outbuildings, and multiple structures requiring documentation |
| Lake-area homes nearby | Wind, moisture, storm, and drainage-related losses |
| Older construction | Repair scope may involve materials or assemblies not captured in a quick estimate |
We inspect the property that actually exists rather than relying on a generic claim template.
Why Insurance Claims Become Underpaid
A claim can be underpaid without anyone handing the property owner a document labeled “underpayment.”
Often, the problem is found inside the scope.
Missed Damage
The insurer may identify the primary area of loss but overlook associated components.
For example, a roof estimate might address shingles while omitting damaged gutters, flashing, vents, interior staining, fence sections, or detached structures.
Scope Omissions
An estimate may contain a repair item but fail to account for every step required to perform the repair.
Proper scoping can involve tear-out, access, removal, replacement, labor, associated materials, disposal, and affected adjoining finishes.
Depreciation Issues
Many policies calculate an initial payment using depreciation. The amount recoverable later can depend on policy terms and whether repairs are completed.
Property owners should understand what has been depreciated, why, and whether any depreciation may be recoverable under their particular policy.
Low or Incomplete Estimates
A carrier estimate is not automatically the final measure of a loss.
We compare the estimate against documented property conditions, measurements, repair requirements, and the applicable insurance policy.
Documentation Problems
Photos taken after cleanup, incomplete inventories, missing mitigation records, inconsistent contractor documentation, and poor timelines can make a legitimate claim harder to evaluate.
This is why documentation is a major part of our work.
If your Oakhurst insurance payment does not match the damage, TX Public Adjusting can review the carrier estimate, photos, scope, and available claim documents before you decide what to do next.
Our Public Adjusting Process
Step 1: Claim Review
We begin by understanding what happened.
We review available policy information, carrier correspondence, estimates, photographs, payments, denial letters, contractor information, and other claim documents.
If the loss is already open, we examine what has happened so far. If the claim has been paid but appears under-scoped, we identify the disputed areas.
Step 2: Property Inspection
We inspect the damaged property and evaluate the areas related to the reported loss.
Depending on the claim, this can include roofing, exterior components, interiors, detached structures, contents, or commercial building systems.
Step 3: Damage Documentation
We build documentation designed to clearly communicate the scope of the claim.
That may include:
- Photographs
- Measurements
- Damage notes
- Repair scope
- Estimates
- Contents information
- Supporting invoices
- Contractor documentation
- Claim correspondence
Step 4: Claim Presentation and Negotiation
We communicate with the insurance company from the policyholder’s side.
When the carrier disagrees with a component of the claim, we work to support the disputed scope with the appropriate documentation rather than relying on unsupported demands.
Step 5: Settlement and Claim Resolution
Our objective is to help the policyholder pursue the amount supported by the covered loss and the insurance policy.
No public adjuster can guarantee a particular settlement. What we can provide is professional claim preparation, documentation, communication, and negotiation focused on the policyholder’s interests.
Why Choose TX Public Adjusting for an Oakhurst Claim?
Licensed Texas Public Adjuster
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839.
Property owners should know who is representing them and verify that the public adjuster handling their claim is properly licensed.
We Represent Policyholders
We are not the insurance company’s adjuster.
A public adjuster is hired by the policyholder. Our role is to document and present your claim—not protect an insurance carrier’s financial interests.
Texas-Focused Property Claim Experience
Our work centers on Texas insurance losses, including hail, wind, water, roof, fire, storm, and commercial property claims.
That matters in a market where severe thunderstorms, tropical systems, freezes, hailstorms, and other weather events regularly create complicated losses.
Residential and Commercial Experience
We work with homeowners as well as owners of commercial and income-producing property.
Our team has reviewed thousands of property claims and understands how quickly a claim becomes more technical when multiple structures, trades, contents, or coverage categories are involved.
Detailed Claim Documentation
A strong claim is not built around a single photograph.
We focus on establishing the complete scope of the loss and providing organized documentation that supports the property owner’s position.
Free Claim Review
Not every loss requires a public adjuster. A free review allows us to first understand the situation and determine how we may be able to help.
Residential & Commercial Claims | Licensed Texas Public Adjuster | Free Claim Review
Areas We Serve Near Oakhurst
TX Public Adjusting assists property owners throughout San Jacinto County and the surrounding Lake Livingston region. Property owners nearby can learn more about working with a Public Adjuster in Point Blank or a Public Adjuster in Coldspring for claims elsewhere in San Jacinto County.
We also serve neighboring Polk County and Lake Livingston communities through our Public Adjuster in Livingston and Public Adjuster in Onalaska pages.
Additional communities served around Oakhurst include Waterwood, Cape Royale, Goodrich, Riverside, and surrounding rural properties across San Jacinto, Polk, Walker, and Trinity counties.
Frequently Asked Questions About Public Adjusters in Oakhurst
What does a public adjuster in Oakhurst do?
A public adjuster represents the property owner during an insurance claim. That can include inspecting the loss, documenting damage, preparing a repair scope, reviewing the insurance company’s estimate, communicating with the carrier, and negotiating disputed claim items.
TX Public Adjusting works for policyholders—not insurance companies.
When should I hire a public adjuster after property damage in Oakhurst?
Many property owners call after receiving a low estimate, partial payment, denial, or scope they disagree with. Others seek help earlier when the loss is substantial or involves several areas of the property.
The right timing depends on the claim. If you are unsure, having the claim reviewed before accepting the carrier’s assessment can help you understand your options. Property owners dealing with an older, closed, or previously paid loss can also review when it is too late to hire a public adjuster because policy terms and claim deadlines can affect the available options.
Can you review an already-paid Oakhurst insurance claim?
Yes. A prior payment does not necessarily mean every part of the claim was fully evaluated.
We can review the carrier’s estimate, payment information, photographs, contractor documentation, and remaining damage to determine whether there are legitimate scope issues that should be addressed. Policy terms and claim deadlines still apply.
Can TX Public Adjusting help with an underpaid roof claim?
Yes. Roof claims are a major part of our property-loss work.
We look beyond the headline number on the estimate and examine the roof slopes and components involved, along with gutters, vents, flashing, exterior damage, and related interior water damage when applicable.
Is hail damage a concern in Oakhurst?
Yes. Oakhurst is exposed to severe thunderstorms capable of producing both hail and damaging winds. National Weather Service statements specifically included Oakhurst during July 2026 storms producing hail and estimated wind gusts of up to 40–50 mph.
The extent of damage depends on hail size, wind speed, roofing material, roof age, impact angle, and other property-specific conditions.
What if a tree falls on my home during an Oakhurst storm?
First address immediate safety concerns and take reasonable steps to prevent additional damage when it is safe to do so.
The insurance claim may involve tree removal as well as damage to roofing, decking, framing, exterior finishes, interior ceilings, insulation, electrical components, contents, or detached structures. Documenting each category separately helps prevent the claim from being treated as simply a tree-removal expense.
Do you handle water damage claims in Oakhurst?
Yes. We review water losses involving covered plumbing events, storm-related openings, interior water intrusion, and related property damage.
Coverage depends heavily on the cause of the water. Rising floodwater is generally handled differently from water entering after covered structural damage, so we examine the facts and the policy rather than treating every water loss the same way.
Do you handle commercial claims around Oakhurst?
Yes. TX Public Adjusting handles residential and commercial claims.
Commercial losses can involve roofing systems, multiple buildings, equipment, inventory, tenant areas, business-use spaces, and larger repair scopes. Those factors often require more detailed estimating and documentation than a simple residential claim.
How much can a public adjuster increase my Oakhurst settlement?
There is no legitimate way to guarantee a specific increase before reviewing the claim.
Every policy, loss, carrier estimate, deductible, coverage provision, and property is different. Our role is to identify covered damage and claim items supported by the evidence and pursue a settlement consistent with the documented loss and policy.
How do I get started with TX Public Adjusting?
Contact TX Public Adjusting and request a Free Claim Review.
Have any available carrier estimates, photographs, payment letters, claim correspondence, contractor estimates, or denial documents ready. If documents are missing, we can still begin by discussing what happened and where the claim currently stands.
Get Insurance Claim Help in Oakhurst, TX
A storm can pass through Oakhurst in minutes. The insurance claim that follows may continue for weeks or months.
If your property has roof damage, hail damage, wind damage, water intrusion, fire damage, tree impact, or another covered loss, you do not have to rely solely on the insurance company’s assessment of what the damage should cost.
TX Public Adjusting represents you—the policyholder.
Rise Public Adjusting LLC
Texas License #3356839
Request your Free Claim Review today. There are no upfront fees, and we can review an existing claim, a low insurance estimate, or a property loss that has become difficult to resolve.
Contact TX Public Adjusting for independent insurance claim assistance in Oakhurst, Texas.