Property damage in Onalaska can become complicated quickly. Homes and businesses around Lake Livingston are exposed to severe thunderstorms, high winds, tornadoes, hail, heavy rain, falling trees, roof damage, plumbing losses, and fire. When the insurance company’s inspection or estimate does not reflect the full extent of that damage, a public adjuster in Onalaska can provide independent claim assistance for the policyholder.
TX Public Adjusting helps residential and commercial property owners document damage, review insurance estimates, identify missing claim items, and negotiate covered property losses. We are operated by Rise Public Adjusting LLC, Texas License #3356839, and our public adjusters represent policyholders—not insurance companies.
Onalaska sits in Polk County on Lake Livingston, where lakefront homes, vacation properties, RV-related businesses, restaurants, and year-round residences create a property mix that is different from many inland Texas communities. The City of Onalaska describes the community as being centered around Lake Livingston, with marinas, campgrounds, RV parks, restaurants, and a substantial weekend population.
Have an underpaid, delayed, denied, or complicated property claim in Onalaska? Request a Free Claim Review from TX Public Adjusting. There are no upfront fees for the initial claim review.
Why Property Owners Hire a Public Adjuster in Onalaska
After a major loss, the insurance company normally assigns an adjuster to inspect the property. That adjuster works within the insurer’s claim process. A public adjuster has a different role: we work for the policyholder.
That distinction matters when the disagreement is not about whether obvious damage exists, but about how much damage exists, what repairs are required, which items belong in the scope, and what those repairs should reasonably cost.
Property owners in Onalaska commonly contact a public adjuster when:
- The carrier’s estimate seems too low.
- Roof or exterior damage was omitted.
- Interior water damage was not fully included.
- A storm claim includes several damaged buildings or structures.
- Depreciation or pricing is difficult to understand.
- The insurance company says some damage is old or unrelated.
- A commercial loss requires extensive documentation.
- The policyholder does not have time to manage repeated inspections and carrier requests.
- A previously paid claim still does not provide enough money for the documented repair scope.
Our team has reviewed thousands of insurance claims involving residential and commercial losses. That experience helps us recognize where scopes, measurements, materials, contents, and related repair items may require a closer look.
Onalaska Storm Risks Are Different From Many Texas Communities
Onalaska’s Lake Livingston setting is one of the defining features of the community, but local property owners also have firsthand experience with severe weather.
Tornado and High-Wind Damage
On April 22, 2020, an EF-3 tornado crossed Lake Livingston and struck Onalaska before continuing through Polk County. The National Weather Service documented EF-3 damage in the Paradise Acres subdivision, estimated peak winds of 140 mph, and a total tornado path of approximately 32 miles.
That event is a powerful reminder that tornado and straight-line wind claims in Onalaska can involve far more than missing shingles. A serious wind event may affect:
- Roofing and decking
- Siding and exterior finishes
- Windows and doors
- Detached structures
- Fences
- HVAC equipment
- Interior ceilings and walls
- Trees and debris impacts
- Personal property
Damage can also extend from one elevation of a home to another, making a complete inspection especially important.
Severe Thunderstorms and Hail
East Texas thunderstorms can combine strong wind, lightning, hail, and intense rainfall. The same weather system associated with the 2020 Onalaska tornado also produced damaging hail in the surrounding region.
Hail damage is sometimes difficult for a property owner to recognize from ground level. Shingles may show bruising or impact marks while vents, flashing, gutters, metal roofing, screens, and exterior components show additional evidence of the storm. Property owners dealing with this type of loss can learn more about the hail damage roof insurance claim process before accepting an insurer’s roof estimate.
Heavy Rain and Water Intrusion
Lake-area property does not automatically mean every water loss is a flood claim. The cause of the water matters.
A storm may damage roofing or exterior components and allow rain into a structure. A separate loss could involve a plumbing failure, appliance leak, or burst pipe. Rising surface water and flooding may involve different coverage, including separate flood insurance, so the policy and cause of loss must be reviewed carefully.
Polk County’s current hazard-mitigation planning includes Onalaska-specific actions related to flooding, hurricane impacts, thunderstorm wind, winter weather, and other natural hazards.
Falling Trees and Debris
Onalaska’s wooded setting creates another practical claim issue. Severe wind can send limbs or mature trees onto roofs, garages, fences, sheds, vehicles, utility areas, and other structures. A claim may involve not only the visible impact point but resulting roof openings, framing damage, interior water intrusion, and emergency mitigation.
Common Insurance Claims in Onalaska
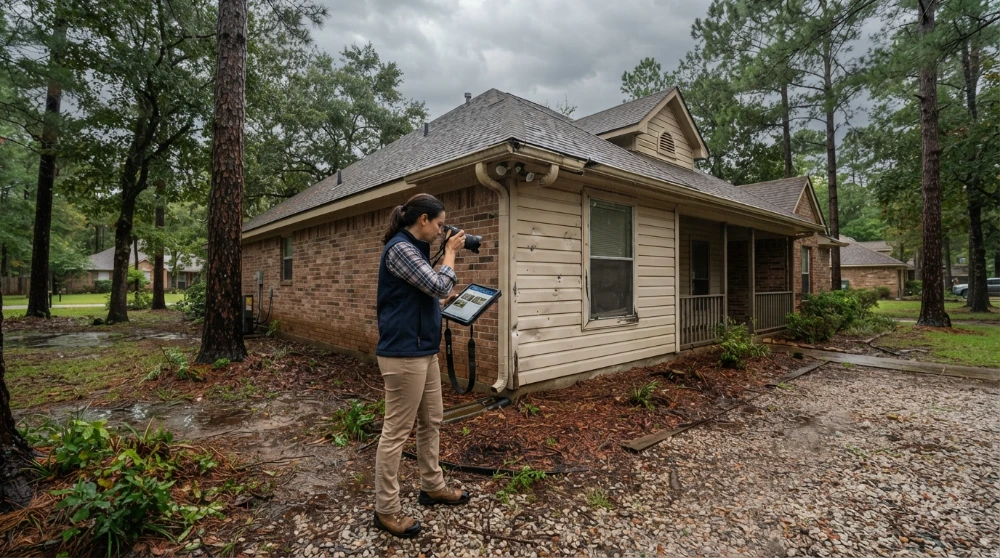
The right documentation depends heavily on the type of loss.
| Claim Type | Damage We Commonly Review |
| Hail Damage Claims | Shingles, metal roofing, vents, flashing, gutters, siding, windows and exterior equipment |
| Water Damage Claims | Plumbing leaks, burst pipes, interior water intrusion, flooring, drywall, cabinets and related finishes |
| Fire Damage Claims | Structural damage, smoke, soot, contents, demolition, debris and repair scope |
| Storm Damage Claims | Tornado, wind, tree impact, wind-related roof openings and exterior damage |
| Roof Damage Claims | Shingles, metal systems, decking, flashing, penetrations, gutters and related components |
| Commercial Property Claims | Roofing, interiors, inventory, equipment, business property and multi-building losses |
Hail Damage Claims
A hail claim should not be limited to a quick look at the center of the roof. We review the roof system along with vents, flashing, gutters, downspouts, screens, siding and other components that may help establish the extent and direction of storm impact.
Water Damage Claims
Water can travel beyond the room where it first becomes visible. In an Onalaska home, a plumbing or storm-related water loss can affect insulation, drywall, flooring, cabinetry, trim and adjoining spaces. A water damage public adjuster can review the carrier’s scope when significant portions of the loss appear to have been missed.
We document the visible damage while also reviewing the reported cause of loss and the carrier’s scope.
Fire Damage Claims
Fire claims often require more documentation than a basic repair estimate. Smoke and soot can travel throughout a structure, contents may need to be inventoried, and the repair scope can include demolition, cleaning, replacement, electrical work and rebuilding. Working with an experienced fire insurance adjuster can help a property owner evaluate whether all parts of the covered loss have been properly documented.
For a major fire loss in Onalaska, organization is critical because many categories of damage may be handled at the same time.
Storm and Tornado Damage Claims
Onalaska’s documented tornado history makes this an especially relevant claim category. Wind can create a complicated pattern of roof, wall, window, structural, interior and debris-related damage.
A property may look repairable from one side while significant damage is present elsewhere.
Roof Damage Claims
Roof claims frequently become disputed because the disagreement is about the scope rather than the existence of damage. If the insurer’s estimate does not reflect the full repair scope, a public adjuster for a roof claim can review the estimate, damage documentation, measurements and omitted components.
One estimate may include a small repair while another inspection identifies damaged accessories, flashing, vents, underlayment, code-related components, or additional roof sections that need to be addressed.
Commercial Property Claims
Onalaska’s lake-centered economy includes restaurants, shops, RV-related properties, lodging, recreational businesses, offices, and other commercial facilities. For larger business losses, a commercial public adjuster can help document building damage, contents, equipment and other covered property components. The City specifically identifies campgrounds, RV parks, marinas and restaurants as part of the local community.
RV parks and related recreational properties can present additional documentation challenges because a single storm may affect multiple buildings, roofs, utility-related components and common areas. TX Public Adjusting also assists with RV park insurance claims involving covered property damage.
Restaurants around the Lake Livingston area may face additional claim issues involving roofing, interior finishes, equipment and water or fire damage. Our team also handles restaurant property insurance claims when a covered loss affects business property.
Commercial claims can involve roofing systems, multiple buildings, equipment, inventory and substantial documentation. TX Public Adjusting handles both residential and commercial property claims.
If the carrier has already inspected your property but the estimate does not appear to match the damage, contact TX Public Adjusting for a Free Claim Review before assuming the first estimate is the final word.
Why Insurance Claims Become Underpaid
A low insurance payment does not always result from one dramatic mistake. More often, several smaller omissions add up.
Missed Damage
A short inspection can overlook secondary roof slopes, accessories, detached structures, interior rooms or less obvious storm damage.
Scope Omissions
The carrier may acknowledge the damaged area but leave necessary repair components out of the estimate.
For example, replacing a damaged roofing system involves more than the primary roof covering. Related materials and labor must also be evaluated.
Depreciation Issues
Replacement cost, actual cash value and recoverable depreciation can be confusing to property owners. We review the carrier paperwork so the policyholder understands how the payment was calculated and what requirements may apply.
Low or Incomplete Estimates
Pricing, measurements, labor assumptions, material quantities and repair methods all affect the final estimate.
A difference in a few line items may seem small. Across an entire roof or commercial property, those differences can become significant.
Documentation Problems
Photos without context, incomplete inventories, missing measurements, unclear estimates and inconsistent records can weaken a claim presentation.
Our job is to organize the claim so the damage and requested scope are supported by clear documentation.
Our Public Adjusting Process
Every claim is different, but our approach follows a disciplined process.
1. Claim Review
We begin by reviewing what happened, the current status of the claim, available insurance documents, carrier correspondence and estimates.
If the insurer has already issued a payment or denial, we review that information as well.
2. Property Inspection
We inspect the reported loss and look for damage related to the claim.
For an Onalaska storm loss, that may include the roof, elevations, exterior components, interior areas, detached structures and commercial property as applicable.
3. Documentation and Scope Development
We organize photographs, measurements, damaged components, repair requirements and other supporting information.
The goal is not to inflate a claim. The goal is to accurately document the covered damage that should be considered under the policy.
4. Estimate and Claim Negotiation
We compare the carrier’s position with the documented scope and communicate claim differences to the insurance company.
When supporting specialists are appropriate, the claim may also require information from contractors, engineers, mitigation professionals, inventory specialists or other qualified parties.
5. Settlement and Claim Resolution
We continue working through the claim documentation and negotiation process until the covered scope is resolved as far as the policy and available evidence allow.
No public adjuster can guarantee a specific settlement. What we can provide is experienced policyholder representation and a structured claim presentation.
Why Choose TX Public Adjusting for an Onalaska Claim?
When you hire TX Public Adjusting, you are hiring an independent advocate for your side of the insurance claim.
Licensed in Texas
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839.
Texas-Focused Property Claim Experience
Texas claims have their own weather patterns, construction issues and storm-loss challenges. Our work is focused on Texas property owners.
Independent Policyholder Representation
We do not represent the insurance company. Public adjusters represent the insured property owner.
Residential and Commercial Experience
We work with homeowners as well as commercial property owners dealing with roof, storm, fire, water, hail and larger property losses.
Detailed Claim Reviews
Our team has reviewed thousands of claims. We know where documentation gaps, scope omissions and estimating disagreements commonly appear.
Free Claim Review
You can speak with TX Public Adjusting about the claim before deciding how to proceed.
Local Onalaska Neighborhoods and Lake Communities We Serve
Onalaska is not simply a point on U.S. 190. Much of the community is organized around Lake Livingston subdivisions, wooded residential areas, waterfront properties and nearby rural tracts.
Polk County maps and planning documents identify numerous communities in and around the Onalaska area, including Paradise Acres, Yaupon Cove, Twin Harbors, Canyon Park, Creek Lake Cove, Oak Ridge, The Point, Nikki’s Landing, Stowaway Bay and Onalaska Wood.
The community’s local identity also centers on Lake Livingston, Onalaska City Park, and the Garland Pavilion. Onalaska City Park includes more than nine acres and a walking track, while nearby Lake Livingston State Park provides another major recreational connection to the lake.
Areas We Serve Near Onalaska
TX Public Adjusting assists property owners throughout Polk County and the Lake Livingston region. If the damaged property is outside Onalaska, we also provide insurance claim assistance through our public adjuster in Livingston and neighboring East Texas service areas.
Across Lake Livingston and the surrounding region, property owners can also find claim assistance from our public adjuster in Point Blank, public adjuster in Goodrich, and public adjuster in Coldspring pages.
Frequently Asked Questions About Public Adjusters in Onalaska
What does a public adjuster in Onalaska do?
A public adjuster represents the policyholder during a property insurance claim. We inspect damage, review insurance documents and carrier estimates, prepare supporting claim documentation, identify scope differences and negotiate with the insurer.
The insurance company’s adjuster works within the insurer’s claim process. TX Public Adjusting works for the property owner.
When should I contact a public adjuster after storm damage in Onalaska?
You can contact a public adjuster soon after the loss, but many Onalaska property owners also reach out after receiving the carrier’s first estimate.
If the payment appears low, the inspection was unusually brief, substantial damage is missing, or repairs cannot reasonably be completed for the carrier’s scope, it may be time for an independent claim review.
Can you help with tornado damage in Onalaska?
Yes, we can review covered property damage resulting from tornado and severe-wind events. Onalaska has experienced major tornado damage before, including the EF-3 tornado that struck the community in April 2020.
A tornado claim may involve roofing, structural components, windows, siding, detached buildings, fallen trees, debris impact and interior water intrusion.
Do you handle Lake Livingston waterfront property claims?
Yes. Waterfront and lake-area properties may experience many of the same covered losses as other homes, including wind, hail, fire, roof and plumbing damage.
Water near the property does not by itself determine coverage. If the damage involves rising floodwater rather than a covered homeowners or commercial property peril, separate flood coverage may apply. We review the circumstances and policy information before making recommendations.
Can a public adjuster help if my Onalaska roof claim was underpaid?
Yes. An underpaid roof claim is one of the situations we routinely review.
We compare the insurance estimate with the documented roof damage, measurements, materials and related repair items. If important components appear to be missing, we can prepare and present supporting documentation to the carrier.
What if the insurance company says my roof damage is old?
Age, deterioration and storm damage can become disputed issues in roof claims. The correct approach is to examine the actual condition of the property, available storm information, photographs, repair history and policy language rather than assume every roof problem comes from one cause.
We review the carrier’s explanation and determine what additional documentation may support the claim.
Can TX Public Adjusting help with commercial claims in Onalaska?
Yes. We assist commercial property owners with roof, storm, hail, water, fire and other covered losses.
That can be especially useful for Onalaska’s restaurants, retail properties, lodging facilities, RV-related businesses and other lake-area commercial operations where a loss may affect multiple parts of the property.
How much does a public adjuster cost in Texas?
TX Public Adjusting provides a Free Claim Review with no upfront fee for the review. If you decide to hire us, the public-adjusting agreement explains the applicable fee and engagement terms before work begins.
You should always understand the written agreement before hiring any public adjuster.
Is it too late to hire a public adjuster after my insurance company has already paid?
Not necessarily. A payment does not automatically mean every claim issue has been resolved. Property owners wondering when it is too late to hire a public adjuster should consider the date of loss, policy requirements, claim status and any applicable deadlines.
Depending on the claim’s timing, policy conditions, documentation and status, an underpaid claim may still be reviewable. The best first step is to provide the carrier estimate and claim documents so we can determine what options may still be available.
Why hire TX Public Adjusting for an Onalaska insurance claim?
TX Public Adjusting combines Texas property-claim experience with independent policyholder representation. We handle both residential and commercial losses and have reviewed thousands of property claims.
Rise Public Adjusting LLC is licensed in Texas under License #3356839, and our role is to represent the insured—not the insurance carrier.
Get a Free Insurance Claim Review in Onalaska
A storm, fire, roof leak or other property loss is difficult enough without wondering whether the insurance estimate accurately reflects the damage.
If you own a home, waterfront property, rental property, commercial building, restaurant, retail space or other insured property in Onalaska, TX Public Adjusting can review the claim and explain what we see.
We assist with:
- Underpaid insurance claims
- Hail and roof damage
- Tornado and wind claims
- Water damage
- Fire and smoke damage
- Commercial property losses
- Missing or disputed scope items
Contact TX Public Adjusting for a Free Claim Review.
Licensed Texas Public Adjuster
Rise Public Adjusting LLC
Texas License #3356839
Residential & Commercial Claims
No upfront fees for your initial claim review