

Property damage in Liverpool can turn into a complicated insurance claim quickly. Gulf Coast hurricanes, severe thunderstorms, tornadoes, wind-driven rain, hail, plumbing failures, and fire can damage more than the first inspection reveals. When the carrier’s estimate leaves out roof components, interior damage, contents, code-related work, or other covered items, the difference can become expensive for a property owner.
TX Public Adjusting provides public adjuster services in Liverpool, Texas for homeowners and commercial property owners who need professional help documenting and presenting a property insurance claim. We represent policyholders—not insurance companies. TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839, with residential and commercial claim experience across Texas.
If your claim has been delayed, denied, underpaid, or you simply want another set of experienced eyes on the carrier’s estimate, request a Free Claim Review. There are no upfront fees to get started, and we can explain what we see before you decide how to proceed.
Property Damage Risks in Liverpool and Brazoria County
Liverpool is an incorporated Brazoria County community between Alvin and Angleton. Its history is closely tied to Chocolate Bayou: the settlement developed as a trading post and was formally established in 1837 as a shipping point for the Stephen F. Austin colony. Today, Chocolate Bayou remains one of the defining features of the area.
That geography matters for property claims. Liverpool sits on the relatively flat Gulf Coastal Plain within the Chocolate Bayou watershed. TCEQ describes the bayou and its tributaries as generally slow-moving because of the area’s gentle relief, and the tidal section of Chocolate Bayou begins northwest of Liverpool.
This is not a part of Texas where storm exposure is theoretical.
Hurricane Beryl crossed Southeast Texas in July 2024 after making landfall near Matagorda as a Category 1 hurricane. Brazoria County was under a hurricane warning, and recorded gusts included 85 mph at Brazoria County Airport and substantially higher measurements elsewhere in the county. State reporting later described hurricane-force winds, heavy rainfall, localized flooding, and more than 1,500 impacted residential structures within Brazoria County.
Liverpool also experienced a much more localized reminder of severe-weather risk on December 28, 2024. A National Weather Service damage survey documented an EF2 tornado beginning about four miles west-northwest of Liverpool, with estimated peak winds of 125 mph before the tornado tracked toward Hillcrest.
Those events help explain why Liverpool property insurance claims frequently deserve a careful review of the roof, exterior, interior, and resulting water damage—not just the most visible storm damage. Property owners dealing with hurricane property damage should document both the obvious exterior damage and less visible water intrusion or interior effects.
Local Areas and Landmarks
Liverpool is a compact community rather than a city divided into large, formally named neighborhoods. Local property references are better understood around the Calhoun Street/County Road 171 core, properties near the Chocolate Bayou corridor, rural and acreage properties along surrounding county roads, and the nearby Chocolate Bayou community.
One of the area’s recognizable landmarks is Albert Finkle Memorial County Park, a three-acre Brazoria County park on Calhoun Street along Chocolate Bayou with a pavilion, walking trail, fishing access, and canoe launch. Liverpool City Hall is also located on Calhoun Street/CR 171.
For an insurance claim, these local distinctions matter. A waterfront or bayou-adjacent property may present different water-intrusion questions than a home farther inland, while rural properties can involve detached structures, fencing, equipment, outbuildings, and larger roofing systems that should not be overlooked during the claim inspection.
Why Property Owners Hire a Public Adjuster in Liverpool
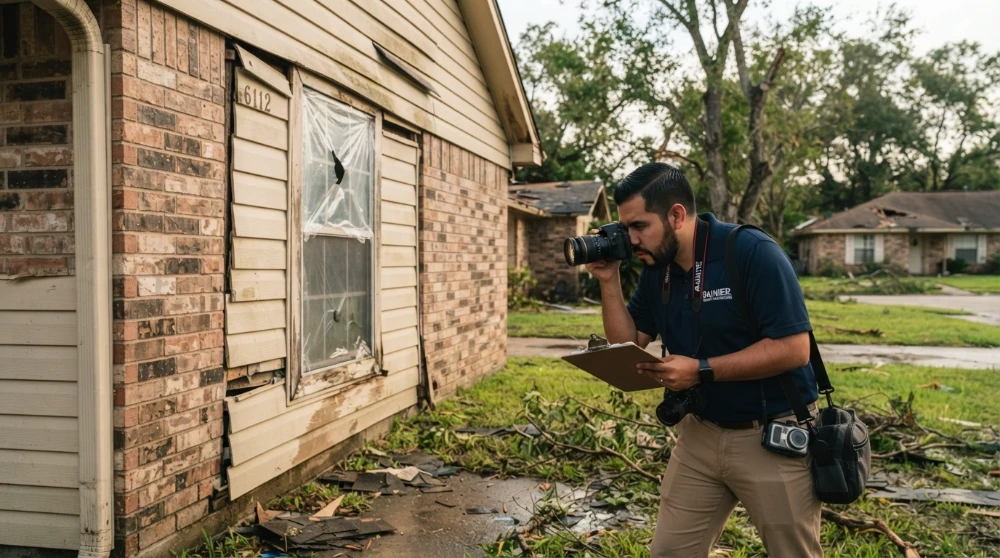
An insurance company adjuster evaluates the loss for the insurer. A public adjuster works on behalf of the policyholder. Understanding the difference between a public adjuster vs. insurance adjuster can help Liverpool property owners understand who each professional represents during a claim.
That difference becomes especially meaningful when a Liverpool property owner receives an estimate that does not appear to reflect the full damage. A roof may show storm-related impacts while the initial scope includes only limited repairs. Wind-driven rain may have damaged insulation, ceilings, walls, flooring, cabinetry, or electrical components that were not fully included. A commercial property may have several roof sections, mechanical units, exterior finishes, inventory, and business-related damage requiring coordinated documentation.
A public adjuster can review the policy and claim documents, inspect the property, identify potentially missed damage, prepare supporting documentation, compare estimates, communicate with the carrier, and negotiate the covered scope of loss.
Our experience includes the review of thousands of property claims, including both residential and commercial losses. That experience is valuable because insurance disputes frequently come down to details: measurements, photographs, repair methodology, damaged materials, estimate line items, depreciation, policy provisions, and evidence connecting the claimed damage to the reported loss.
Need insurance claim help in Liverpool? TX Public Adjusting offers a Free Claim Review for property owners dealing with storm, roof, water, hail, fire, and commercial losses.
Common Insurance Claims in Liverpool
The combination of Gulf Coast weather, severe thunderstorms, bayou geography, older and newer construction, and rural properties creates a broad claim profile.
| Claim Type | Damage We Commonly Review |
| Hail damage | Shingles, metal roofing, vents, flashing, gutters, siding, windows and exterior finishes |
| Water damage | Drywall, ceilings, insulation, flooring, cabinets, contents and moisture-related damage |
| Fire damage | Structural materials, smoke, soot, contents, odor remediation and additional living expenses when covered |
| Storm damage | Wind, tornado, fallen debris, damaged openings and wind-driven rain |
| Roof damage | Shingles, decking, flashing, underlayment, ridge components, penetrations and related interior leaks |
| Commercial claims | Roofing, building envelope, equipment, inventory, interiors and business property |
Hail Damage Claims
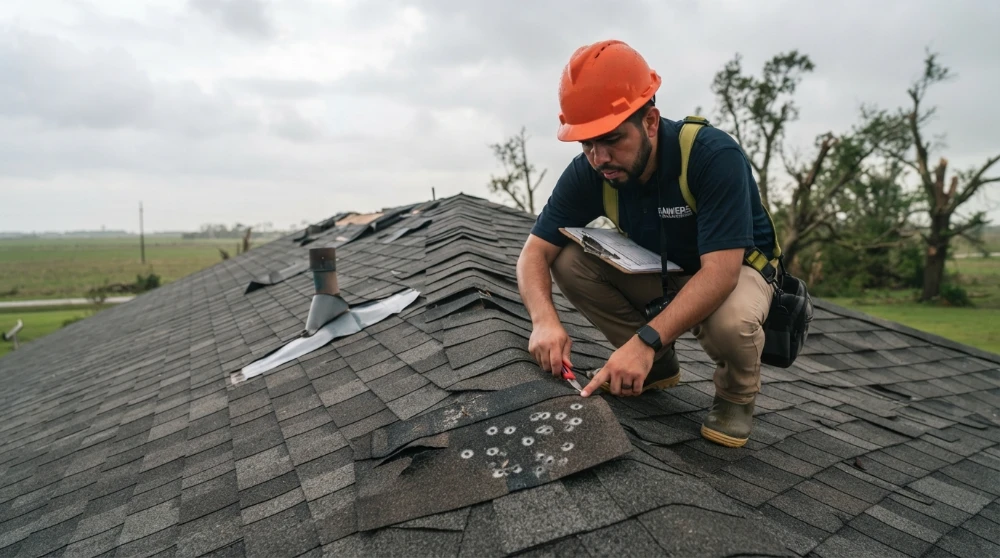
Hail can damage asphalt shingles without creating an immediate leak. Property owners dealing with a hail damage insurance claim may also need the roof inspected for impacts to metal vents, flashing, gutters, siding, and other exterior components. On metal components, impacts may affect vents, gutters, flashing, rooftop equipment, siding, or other exterior materials.
The challenge is often proving the full storm-related scope. A carrier inspection may identify certain impacts but omit adjacent components or disagree about whether damage is functional, cosmetic, repairable, or attributable to another cause. We review the physical evidence alongside the carrier’s estimate and claim position.
Water Damage Claims
Water losses in Liverpool may result from burst pipes, failed plumbing components, roof openings, wind-driven rain, appliance failures, or other sudden events. A water damage public adjuster can help document the source and extent of a covered loss when the carrier’s initial scope does not account for all affected materials.
Cause matters because policy coverage can vary substantially. Surface flooding, for example, is generally treated differently from water entering through storm-created damage or a sudden plumbing failure. We document the resulting damage and evaluate the claim based on the policy and reported cause rather than assuming every water loss is handled the same way.
Fire Damage Claims
A fire claim rarely stops where the flames stopped. Smoke and soot can travel through adjoining rooms, HVAC systems, attics, contents, insulation, and porous finishes. For larger losses, working with a fire insurance adjuster who represents the policyholder can help organize structural damage, smoke contamination, contents, cleanup costs, and other covered portions of the claim.
Liverpool fire claims may therefore require documentation of building damage, personal property, cleaning versus replacement decisions, debris removal, smoke remediation, temporary living arrangements, and other covered expenses.
Storm and Tornado Damage Claims
The EF2 tornado that began near Liverpool in December 2024 is a direct example of the type of severe convective weather this part of Brazoria County can experience.
Tornado and straight-line wind claims can involve lifted roofing, missing shingles, damaged decking, broken windows, siding loss, fencing, detached structures, trees falling onto buildings, and rain entering through newly created openings. Damage should be evaluated as a complete event rather than as isolated repairs.
Roof Damage Claims
Roof disputes are among the most common reasons property owners contact a public adjuster. When those disagreements become significant, a public adjuster for a roof claim can compare the insurance estimate against the documented repair scope and identify potentially omitted items.
A carrier may agree that damage occurred but disagree about repairability, quantities, affected slopes, matching, flashing, accessories, underlayment, labor, or interior damage caused by the roof opening. We compare the inspection findings to the carrier’s scope and identify items that deserve further documentation.
Commercial Property Claims
Commercial claims can become substantially more detailed than residential losses. Warehouses, offices, retail properties, multifamily buildings, restaurants, agricultural properties, and other businesses may have multiple roofing systems, larger HVAC equipment, specialized finishes, inventory, tenant improvements, and operational concerns.
TX Public Adjusting works with residential policyholders as well as businesses facing complex commercial property claims involving roofing, building systems, contents, inventory, tenant improvements, and other covered property.
Why Liverpool Insurance Claims Become Underpaid
An underpaid claim does not always result from one dramatic disagreement. More often, the settlement is reduced by a series of smaller omissions.
Missed roof accessories, incomplete interior quantities, overlooked water migration, missing detach-and-reset labor, incorrect material assumptions, depreciation issues, limited photographs, or an estimate prepared before all damage was visible can collectively create a meaningful gap between the carrier’s scope and the actual repair scope.
Documentation is another frequent problem. After a hurricane or major storm, property owners are understandably focused on stopping leaks, removing debris, restoring power, arranging temporary repairs, and keeping their families or businesses operating. Evidence can disappear during emergency work.
That is why detailed photographs, measurements, invoices, mitigation records, contractor information, damaged-item inventories, and correspondence with the insurance company should be organized early whenever possible.
A Second Look Can Matter
If the carrier has already issued an estimate, that does not necessarily mean the claim is finished.
We can compare the estimate against the observed damage, review what was included and excluded, identify potential scope discrepancies, and determine whether additional documentation may support further consideration.
If your Liverpool insurance claim looks low, ask TX Public Adjusting for a Free Claim Review before assuming the carrier’s first estimate is the final word.
Our Public Adjusting Process
Our approach is built around documenting the loss rather than simply arguing about the payment.
| Stage | What We Do |
| Claim Review | Review the policy situation, carrier estimate, payment, denial letter, photographs and available claim documents |
| Property Inspection | Inspect damaged areas and look for related damage that may have been omitted |
| Documentation | Prepare photographs, measurements, estimates, inventories and other supporting evidence as appropriate |
| Claim Presentation | Organize the documented scope and communicate claim issues to the insurance carrier |
| Negotiation | Advocate for the policyholder and work toward a settlement based on covered, documented damage |
We stay focused on the details because that is where many property claim disagreements are resolved. The goal is not to exaggerate a loss. It is to make sure covered damage is properly identified, documented, estimated, and presented.
Why Choose TX Public Adjusting
TX Public Adjusting is Texas-focused and works specifically for policyholders facing property insurance losses.
We bring experience with storm, roof, water, fire, hail, hurricane, tornado, and commercial property claims while maintaining independent representation from the insurance company.
| Trust Signal | TX Public Adjusting |
| Licensed Texas Public Adjuster | Yes |
| Legal Entity | Rise Public Adjusting LLC |
| Texas License | #3356839 |
| Residential Claims | Yes |
| Commercial Claims | Yes |
| Free Claim Review | Yes |
| Represents Policyholders | Yes |
A public adjuster does not work for the carrier. Our responsibility is to the policyholder we represent.
That independence can be especially valuable after a widespread Brazoria County storm, when insurance companies may be processing a high volume of losses and inspections. Hurricane Beryl alone resulted in extensive building damage across the region, illustrating how quickly claim volume can surge after a Gulf Coast event.
Areas We Serve Near Liverpool
TX Public Adjusting serves property owners throughout Brazoria County and the surrounding Gulf Coast region. Property owners looking for a public adjuster in Alvin, a public adjuster in Angleton, or a public adjuster in Danbury can visit our dedicated local service pages. We also assist property owners in Pearland, Lake Jackson, Clute, Freeport, Bailey’s Prairie, and surrounding Brazoria County communities.
Frequently Asked Questions
What does a public adjuster in Liverpool do?
A public adjuster represents the policyholder during a property insurance claim. We inspect and document damage, review the carrier’s estimate, organize supporting evidence, communicate claim issues, and negotiate concerning covered damage.
That role is different from the insurance company adjuster, whose assignment comes from the insurer.
When should I hire a public adjuster after storm damage in Liverpool?
Consider requesting a review when the damage is extensive, the estimate looks incomplete, the insurer disputes the cause or scope, the claim has been denied, or you do not have the time or experience to manage a complicated property claim.
You can also contact a public adjuster after an initial payment has been issued. If considerable time has passed, our guide explaining when it is too late to hire a public adjuster provides additional information about timing. The important question is whether the policy, claim circumstances, and applicable deadlines still allow the issues to be addressed.
Can you help with tornado damage near Liverpool?
Yes. Tornado losses can involve roofing, framing, exterior finishes, windows, detached structures, debris impact, and interior water intrusion.
The December 2024 EF2 tornado near Liverpool demonstrates why tornado damage is a genuine local concern rather than a generic Texas risk.
Do you handle hurricane claims in Brazoria County?
Yes. We review hurricane and windstorm property claims involving roofs, exteriors, interiors, commercial buildings, and resulting water intrusion.
Brazoria County experienced hurricane-force conditions during Hurricane Beryl, including high winds and localized flooding.
Can a public adjuster help if my Liverpool roof claim was underpaid?
Yes. We can review the carrier estimate against the roof damage and related repair scope. Common disagreements involve affected slopes, accessories, flashing, quantities, repairability, labor, and resulting interior damage.
An underpaid claim should be evaluated based on the actual documentation and policy rather than assumptions about what every roof claim should include.
What about water damage near Chocolate Bayou?
Water damage requires careful attention to the source. Properties around Liverpool and the Chocolate Bayou watershed may face heavy-rain and drainage concerns, but surface flooding and water entering through storm-created building damage can involve different insurance coverage.
We review the circumstances of the loss and applicable policy rather than treating every water event the same way.
Can you help with a commercial property claim in Liverpool?
Yes. TX Public Adjusting handles residential and commercial claims.
Commercial losses may involve building damage, commercial roofing systems, HVAC equipment, contents, inventory, tenant improvements, and other property-related issues requiring a more detailed scope.
Can you review a claim that has already been denied?
Yes. A denial can be reviewed to understand the carrier’s stated reasoning, the policy language involved, available evidence, and whether additional documentation may be relevant.
A review does not guarantee that a denial can be changed, but it can help the property owner understand the carrier’s position and available next steps.
How much does it cost to start working with TX Public Adjusting?
We offer a Free Claim Review, with no upfront fees to get started. If representation makes sense, the compensation arrangement and services are explained in the written agreement before moving forward.
You should always understand a public adjuster’s fee and contract terms before signing.
What should I have ready for my Free Claim Review?
Send whatever you currently have. Helpful documents can include the insurance carrier’s estimate, payment letter, denial or reservation-of-rights correspondence, photographs, contractor estimates, invoices, mitigation documents, and your policy if available.
Do not delay contacting us simply because the file is incomplete. We can identify what additional documentation may be useful after reviewing the claim.
Get Help With a Liverpool Property Insurance Claim
A hurricane, tornado, roof leak, hailstorm, fire, or major water loss can leave a Liverpool property owner dealing with repairs and an insurance claim at the same time. You should not have to guess whether important damage was omitted from the estimate.
TX Public Adjusting represents policyholders—not insurance companies.
Rise Public Adjusting LLC
Texas Public Adjuster License #3356839
Request your Free Claim Review today. There are no upfront fees to get started. Contact TX Public Adjusting and let us review the damage, carrier estimate, denial, delay, or payment so you can make an informed decision about your claim.