

Property damage in Danbury can turn into a complicated insurance claim quickly. Severe thunderstorms, Gulf Coast tropical systems, hail, straight-line winds, tornadoes, water intrusion, and roof damage all affect property owners in this part of Brazoria County. When an insurance estimate does not reflect the full extent of the loss, a public adjuster in Danbury, TX can help document the damage and represent your interests throughout the claim.
TX Public Adjusting works for homeowners, business owners, landlords, and other policyholders—not the insurance company. Our team reviews policies, inspects damaged property, prepares detailed documentation, evaluates insurance estimates, and negotiates covered property claims.
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839. We have experience reviewing thousands of residential and commercial property claims across Texas.
If your Danbury insurance claim has been underpaid, delayed, disputed, or simply feels incomplete, contact TX Public Adjusting for a Free Claim Review. There are no upfront fees.
Why Property Owners Hire a Public Adjuster in Danbury
Danbury has a different property-loss profile than a dense Houston suburb or an inland North Texas city. The community sits in Brazoria County between Angleton and the greater Alvin area, surrounded by open land, agricultural properties, drainage systems, and a mix of older homes, newer residential development, acreage properties, barns, shops, and commercial buildings.
Those characteristics matter after a storm.
Wind can travel across open terrain with relatively little obstruction. Hail can affect roofs, metal structures, HVAC equipment, fencing, gutters, and exterior finishes. Tropical weather moving inland from the Gulf can bring prolonged rainfall and wind-driven water. Drainage problems can create additional complications after heavy rain.
Danbury has experienced these hazards firsthand. During Hurricane Harvey in 2017, the National Weather Service documented an EF0 tornado beginning near Danbury that damaged a barn and trees before crossing Highway 35. NOAA also recorded another EF0 tornado just east of Danbury in March 2022. More recently, the Storm Prediction Center recorded estimated 1.5-inch hail in Danbury on December 24, 2024.
That local storm history is one reason a property claim here deserves more than a quick exterior inspection.
A carrier’s adjuster represents the insurance company. A Danbury public adjuster represents the policyholder.
We can become involved when:
- A carrier estimate appears too low.
- Roof or exterior damage was left out of the scope.
- Interior water damage developed after wind or roof damage.
- A claim includes multiple structures or areas of loss.
- Depreciation or repair pricing is creating questions.
- The insurance company disputes part of the damage.
- A commercial loss is interrupting business operations.
- You need help organizing photographs, estimates, inventories, invoices, and other claim documentation.
- You believe a closed claim may still contain unresolved damage.
Have concerns about a Danbury property damage claim? Request a Free Claim Review from TX Public Adjusting.
Storm and Property Damage Risks in Danbury, Texas
Danbury’s position in southeastern Texas means property owners need to prepare for both Gulf Coast weather and severe thunderstorms.
Hurricanes and Tropical Storms
Although Danbury is inland from the immediate coastline, Brazoria County remains exposed to tropical systems arriving from the Gulf of Mexico.
Hurricanes and tropical storms can create several types of loss at the same property:
- Wind-damaged shingles or roof membranes
- Lifted flashing
- Damaged vents and roof penetrations
- Wind-driven rain
- Ceiling and wall staining
- Wet insulation
- Damaged fencing and accessory structures
- Tree impact
- Exterior siding damage
- Business interruption
Brazoria County maintains specific Hurricane Harvey substantial-damage and floodplain resources, reflecting the significant effect that major tropical events can have throughout the county.
One challenge with hurricane claims is separating different causes of loss. A property may have wind damage, rain entering through storm-created openings, pre-existing wear, and surface-water flooding at the same time. Those causes can be treated differently under a policy.
Detailed documentation becomes especially important.
Hail Damage
Danbury is not immune to significant hail.
The December 2024 storm report documenting approximately 1.5-inch hail directly in Danbury is a useful reminder that damaging hail is not limited to Dallas-Fort Worth or Central Texas.
Hail damage may affect more than shingles. During an inspection, the full property may need to be evaluated, including:
- Asphalt and metal roofing
- Gutters and downspouts
- Roof vents and flashing
- HVAC condenser fins
- Metal awnings
- Window screens
- Exterior siding
- Fences
- Detached buildings
- Commercial roof systems
Some hail damage is easy to spot. Other damage requires a closer inspection and proper documentation. If you are dealing with a hail damage roof insurance claim, documentation should extend beyond the shingles to other affected exterior components.
Tornado and Straight-Line Wind Damage
Danbury has had multiple documented tornado events, including during Hurricane Harvey and again in March 2022.
Wind losses can be especially deceptive.
A roof does not have to be missing for significant damage to exist. High winds can loosen shingles, lift roofing components, damage flashing, open seams, move rooftop equipment, and allow rain to enter later.
In August 2026, the National Weather Service included Danbury in a severe thunderstorm warning for winds of up to 60 mph, specifically warning that the storm could damage roofs, siding, and trees.
Heavy Rain and Water Damage
Brazoria County’s flat coastal-plain terrain and intense Gulf Coast rainfall make drainage and water management important concerns. State flood-planning documents identify drainage improvements and flood-risk studies within Brazoria County.
Insurance coverage for water depends heavily on the source of the water and the terms of the policy.
For example, rain entering through storm damage to a covered roof may be treated differently from rising surface water. Plumbing failures create another set of coverage and documentation issues.
We review the circumstances surrounding the loss rather than assuming all water damage belongs in the same category.
Common Insurance Claims in Danbury
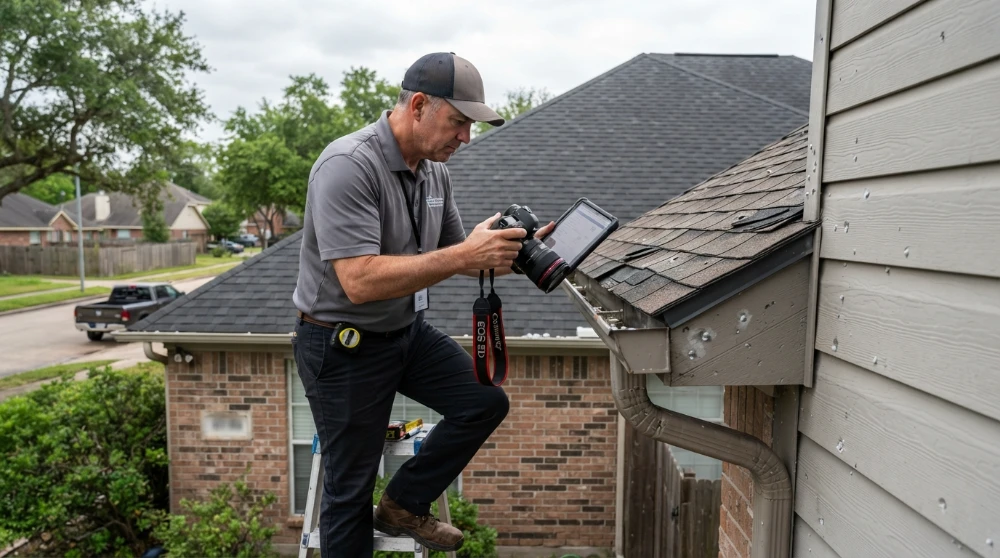
Homes and businesses around Danbury can experience losses ranging from a damaged roof after a fast-moving thunderstorm to extensive interior damage following a major Gulf Coast weather event.
Hail Damage Claims
A hailstorm can damage multiple building components in minutes.
For Danbury homeowners, that can mean bruised or fractured shingles, dented gutters, damaged vents, compromised flashing, and impacts to outdoor equipment. Owners of metal buildings, workshops, agricultural structures, and commercial properties may also find dents or functional damage across large roof and wall surfaces.
The insurance company’s first estimate does not always identify every affected item.
TX Public Adjusting can inspect the property, document storm-related conditions, compare those findings with the carrier’s estimate, and address legitimate scope differences.
Water Damage Claims
Water claims can begin with a burst pipe, appliance failure, roof leak, plumbing problem, or rain entering after storm damage.
The visible stain is often only part of the loss.
Water can affect:
- Drywall
- Insulation
- Flooring
- Cabinets
- Baseboards
- Electrical components
- Contents
- Adjacent rooms
- Structural materials
A good claim scope should account for the actual damaged areas and the reasonable work required to restore them, subject to the policy. When the carrier’s estimate appears incomplete, a water damage public adjuster can review the documented loss and scope.
Fire and Smoke Damage Claims
A structure fire can create one of the most detailed property claims a policyholder will ever handle.
Damage can extend beyond burned materials. Smoke, soot, heat, water used during firefighting, debris, odor, damaged contents, and temporary living or business expenses may all need to be documented.
For a home or business owner already dealing with the disruption of a fire, organizing a large claim can become a second full-time job. A fire insurance adjuster representing the policyholder can help organize the building, contents, smoke, soot, and related portions of the loss.
Our role is to build an organized loss presentation and communicate with the insurer on the policyholder’s behalf.
Storm Damage Claims
A single Danbury thunderstorm can produce wind, hail, rain, fallen limbs, and power-related damage at the same property.
That makes storm claims especially dependent on a thorough inspection.
We look beyond one visibly damaged section and evaluate the loss as a whole.
Roof Damage Claims
Roof claims are among the most common property insurance disputes. Property owners may hire a public adjuster for a roof claim when the carrier’s estimate appears to miss damaged components, quantities, or necessary repair work.
Carrier estimates can differ over:
- Repair versus replacement
- Number of damaged shingles
- Roofing accessories
- Flashing
- Ventilation components
- Drip edge
- Underlayment
- Metal components
- Interior resulting damage
- Labor and material pricing
Danbury properties include everything from traditional residential roofs to metal roofs, barns, workshops, acreage improvements, and commercial systems. Each requires an inspection appropriate to the construction involved.
Commercial Property Claims
Danbury may be a smaller community, but local commercial and agricultural property losses can still become substantial.
Commercial claims may involve:
- Retail buildings
- Offices
- Workshops
- Warehouses
- Agricultural buildings
- Rental properties
- Multifamily property
- Churches
- Restaurants
- Equipment
- Business contents
When operations are interrupted, the owner has two problems at once: repairing the physical property and keeping the business moving.
TX Public Adjusting handles both residential and commercial property claims throughout Texas. A commercial public adjuster can assist when a business loss involves building damage, roofing, equipment, contents, or other documented property damage.
Why Danbury Insurance Claims Become Underpaid
An underpaid claim does not always begin with an outright denial.
Often, the problem is a collection of smaller omissions.
Missed Damage
A short inspection may identify obvious roof damage while overlooking gutters, flashing, siding, fencing, interior staining, detached structures, or damaged equipment.
Those omissions can add up.
Scope Omissions
An estimate may recognize a damaged item without including everything reasonably required to complete the repair.
For example, a roof scope can become disputed over associated roofing components, access requirements, tear-off, disposal, flashing, or adjacent materials.
Depreciation Issues
Replacement cost and actual cash value provisions can affect when money is paid and what documentation is needed to recover depreciation.
Policyholders should understand what their own policy requires rather than assuming every claim works the same way.
Low or Incomplete Estimates
The insurance company’s estimate is not necessarily the final word on the cost of repairs.
If measurements, quantities, materials, labor, or damaged components are missing, the estimate may need to be challenged with evidence.
Documentation Problems
Insurance claims depend heavily on documentation.
Photos taken after cleanup, discarded damaged materials, incomplete inventories, missing receipts, unclear contractor estimates, or a poorly documented cause of loss can create problems later.
A public adjuster helps organize the claim before those issues become harder to correct.
Our Public Adjusting Process
Every Danbury claim is different, but our work generally follows five stages.
| Stage | What TX Public Adjusting Does |
| 1. Claim Review | We discuss the loss, review the status of the claim, examine available estimates and documentation, and identify areas that may deserve closer review. |
| 2. Property Inspection | We inspect visible damage and evaluate the affected building components based on the type of loss. |
| 3. Documentation | We organize photographs, measurements, estimates, inventories, invoices, supporting records, and other relevant claim evidence. |
| 4. Claim Presentation & Negotiation | We communicate documented scope differences and negotiate with the insurance company on behalf of the policyholder. |
| 5. Settlement Process | We continue working through claim issues and settlement documentation with the goal of obtaining the benefits available under the policy for covered damage. |
A public adjuster cannot create coverage that does not exist. Our job is to identify, document, and present covered property damage accurately and advocate for the policyholder throughout the process.
Property Claims Across Danbury’s Residential Areas
Danbury’s small-town character does not mean every property is the same.
Residential areas and subdivisions in the 77534 area include Danbury Heights, Shadow Bend, Bayou Oaks, Bayou Oaks Estates, Dove Ridge Estates, Prairie Rose, Quail Ridge, and Bungalo Villa.
Some properties are older homes on established streets. Others sit on larger lots or within newer subdivisions. Outside the core of town, acreage, barns, garages, workshops, and detached structures become more common.
That variety affects insurance claims.
An older house near central Danbury may have repair and material-matching issues that differ from a newer property in Bayou Oaks Estates. An acreage loss may require documentation of multiple structures. A metal workshop can respond very differently to hail than an asphalt-shingle residence.
Local claim work should account for those differences instead of treating every Danbury property like the same suburban house.
Community landmarks such as Skrabanek Park, the Danbury Community Library, the Danbury Baseball Complex, and the Danbury ISD campus also reflect how compact the community is.
That compact footprint makes localized thunderstorms especially noticeable: a single storm cell can affect homes, schools, businesses, agricultural property, and outbuildings within a relatively small area.
Why Choose TX Public Adjusting for a Danbury Claim?
TX Public Adjusting represents property owners—not insurance carriers.
Licensed Texas Public Adjuster
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839.
Texas-Focused Claim Experience
Texas insurance claims come with Texas weather.
Our work includes losses involving hail, wind, hurricanes, water, fire, roofs, and commercial property throughout the state.
Thousands of Claims Reviewed
Our experience includes thousands of claim reviews involving residential and commercial losses.
That experience matters when an estimate needs to be examined line by line or several categories of damage must be organized into one claim.
Independent Policyholder Representation
The insurance company has professionals working on its side of the claim.
A public adjuster works for the policyholder.
Our responsibility is to document your damage and advocate for your interests under the terms of the insurance policy.
Residential and Commercial Expertise
We assist with single-family homes, rental properties, multifamily buildings, businesses, commercial structures, and other insured Texas properties.
Free Claim Review
Not every claim requires a public adjuster.
A review can help determine whether there are meaningful scope, documentation, or claim-handling issues worth addressing.
There are no upfront fees to request a claim review.
Areas We Serve Near Danbury
Our work is not limited to properties inside Danbury city limits.
TX Public Adjusting assists policyholders throughout Brazoria County and surrounding Southeast Texas communities, including Angleton, Alvin, Liverpool, Iowa Colony, Manvel, Lake Jackson, Richwood, Clute, Brazoria, Pearland, Bailey’s Prairie, and nearby rural areas.
Danbury’s location along the Highway 35 corridor also puts property owners within a regional storm pattern that regularly affects communities between the Houston metropolitan area and the Texas Gulf Coast.
If your property is outside Danbury but elsewhere in Brazoria County, contact us to discuss your claim.
Frequently Asked Questions About Public Adjusters in Danbury
What does a public adjuster in Danbury do?
A public adjuster represents the policyholder during a property insurance claim. That can include reviewing the policy and carrier estimate, inspecting damage, preparing documentation, developing a repair scope, communicating with the insurer, and negotiating claim issues.
TX Public Adjusting represents homeowners and commercial property owners rather than insurance companies.
When should I call a public adjuster after storm damage in Danbury?
You can contact a public adjuster soon after discovering significant damage, but you can also seek help after the insurance company has already inspected the property.
Many Danbury property owners call after receiving an estimate that appears too low, discovering damage that was omitted, experiencing a delay, or realizing the claim is more complicated than expected. If your claim is already underway, you may also want to understand when is it too late to hire a public adjuster before assuming it is too late to seek assistance.
Can a public adjuster help with a hail-damaged roof in Danbury?
Yes. Hail and roof claims are common reasons property owners seek public adjusting help.
Danbury has experienced documented large hail, including approximately 1.5-inch hail reported in December 2024. A claim review can compare the carrier’s scope with the observable storm damage and determine whether important building components were omitted.
Can you help after hurricane or tropical storm damage?
Yes. Danbury and Brazoria County can be affected by tropical storms and hurricanes moving inland from the Gulf.
These claims can involve roof damage, wind-driven rain, fallen trees, damaged exterior components, interior water damage, and multiple buildings. We document covered damage and help separate the different components of the loss.
Does homeowners insurance cover flooding in Danbury?
Standard property insurance and flood insurance are generally separate forms of coverage, so the source of the water matters.
A roof opening created by covered wind damage may involve different policy provisions from rising surface water. If multiple sources of water are involved, careful documentation becomes particularly important. Coverage ultimately depends on the language of the individual policy.
Can you help if the insurance company already paid my Danbury claim?
Potentially.
Receiving a payment does not automatically mean every legitimate issue has been resolved. We can review the carrier estimate, photographs, scope, repair information, and other documentation to determine whether covered damage may have been missed or under-scoped.
Timing and policy requirements matter, so it is better to request a review sooner rather than much later.
Can you reopen a closed insurance claim?
Some claims may still have options after being closed, depending on the circumstances, policy, deadlines, previous payments, and applicable Texas requirements.
We first review what was submitted, what the carrier paid or denied, and what unresolved damage remains. From there, we can explain whether public adjusting assistance makes sense.
Do you handle commercial property claims in Danbury?
Yes.
TX Public Adjusting assists commercial property owners with losses involving roofs, hail, wind, water, fire, storm damage, contents, and related property issues. Commercial claims may require more extensive documentation because large roof systems, equipment, tenant spaces, inventory, and interruption issues can all be involved.
How long does a Danbury property insurance claim take?
There is no single timeline that applies to every claim. Property owners dealing with an early delay may also want to know how long does an insurance adjuster have to contact you after a Texas property claim is reported.
A straightforward roof claim may progress differently from a major fire, hurricane, commercial loss, or disputed claim. Inspection scheduling, documentation, insurer responses, repair estimates, policy questions, supplements, and disagreements over scope can all affect the timeline.
Our focus is on documenting the loss correctly rather than rushing through important claim details.
How much does it cost to have TX Public Adjusting review my claim?
The initial Claim Review is free, and there are no upfront fees to request that review.
Before representation begins, the fee arrangement and terms are explained so you understand how the engagement works. You can then decide whether hiring a public adjuster makes sense for your specific Danbury insurance claim.
Get Help With a Danbury Property Damage Claim
A storm may pass through Danbury in minutes. The insurance claim that follows can last much longer.
If your roof was damaged by hail, wind pushed rain into your home, a fire caused widespread damage, or your insurance estimate simply does not reflect what happened to the property, you do not have to evaluate the claim by yourself.
TX Public Adjusting represents the policyholder—not the insurance company.
Rise Public Adjusting LLC
Texas License #3356839
We help Texas homeowners and commercial property owners document damage, review insurance estimates, communicate with carriers, and pursue properly supported property claims.
Request your Free Claim Review today. No upfront fees. Contact TX Public Adjusting to discuss your Danbury property damage claim.