Property damage in Simonton can turn into a complicated insurance claim quickly. This small Fort Bend County community sits close to the Brazos River, with large residential lots, rural properties, open land, and homes in and around Valley Lodge. Flood exposure is a major local concern, while Gulf Coast tropical systems, wind-driven rain, thunderstorms, hail, tornado activity, roof damage, and interior water intrusion can all create costly losses.
If your insurance company has delayed, denied, or underpaid a property claim, a Public Adjuster in Simonton can represent your interests throughout the claim process. TX Public Adjusting helps homeowners and commercial property owners document damage, review insurance estimates, identify scope omissions, and negotiate covered property claims.
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839. We represent policyholders—not insurance companies—and offer a Free Claim Review with no upfront fees.
Need help with a Simonton property damage claim? Contact TX Public Adjusting for a free review before accepting a settlement that may not reflect the full scope of your damage.
Why Property Owners Hire a Public Adjuster in Simonton
Simonton has property characteristics that make careful claim documentation especially important. The community is distinctly more rural than many Houston-area suburbs. Large lots, older homes, detached structures, fencing, outbuildings, mature trees, private drainage features, and properties near the Brazos River can create losses that are more complicated than a simple roof replacement.
The City of Simonton identifies two distinct parts of the community: the historic city core and Valley Lodge, a large residential subdivision extending west toward the Brazos River. The historic center developed around the intersection of FM 1093 and FM 1489, where the old Berkman General Store building remains a local reference point. Simonton is also only a short drive from Fulshear while retaining a much more open, rural character.
When significant weather reaches western Fort Bend County, damage may involve several parts of a property at once:
- Roofing and shingles
- Gutters, vents, flashing, and soft metals
- Exterior siding and paint
- Windows and doors
- Garages, barns, sheds, and detached structures
- Interior drywall, insulation, flooring, and cabinetry
- Electrical or mechanical systems exposed to water
- Fencing, gates, and exterior improvements
- Commercial roofs and building envelopes
An insurance company adjuster investigates the loss for the carrier. A public insurance adjuster in Simonton works for the policyholder. Understanding the difference between a public adjuster vs. independent adjuster can help property owners understand who each adjuster represents during the claim.
That distinction matters when the carrier’s estimate leaves out portions of the loss, uses a narrower repair scope than contractors are finding, applies depreciation you do not understand, or disputes whether certain damage resulted from the covered event.
Simonton Property Claims Require Local Storm Awareness
Simonton faces a weather profile that is different from many inland Texas communities. Its position near the Brazos River and within the western portion of Fort Bend County makes water and flooding a particularly significant local concern.
The city’s 2024 Comprehensive Plan states that approximately 75% of Simonton lies within the 100-year floodplain, with additional land located in the Brazos River floodway. City planning documents also anticipate that updated flood mapping could place virtually all Simonton properties within the 100-year floodplain.
The city’s emergency management information similarly notes that Simonton sits in the far northwest corner of Fort Bend County and is bordered to the west and north by the Brazos River.
Brazos River Flooding and Water Damage
River flooding is one of Simonton’s defining property risks. Hurricane Harvey demonstrated how severe that risk can become. Fort Bend County reported major housing damage in Simonton and other Brazos River communities during the 2017 disaster, with properties near waterways experiencing extensive flooding and, in some cases, destruction.
Flood claims require careful coverage analysis because standard property policies and separate flood insurance policies do not necessarily cover the same causes of loss. Wind-driven rain, roof openings, plumbing losses, surface water, rising river water, and drainage problems can involve very different policy questions.
For that reason, determining how water entered the property can be just as important as documenting how much damage occurred.
Hurricanes and Tropical Storms
Simonton is inland, but it remains close enough to the Gulf Coast for tropical systems to produce damaging wind, prolonged rainfall, tornadoes, falling trees, roof openings, and water intrusion. Understanding the different types of hurricane property damage can be especially useful in Simonton because wind, wind-driven rain, roof openings, and rising water may occur during the same weather event.
A hurricane claim in Simonton may involve several causes of damage occurring during the same event. For example, wind can damage shingles or flashing before rain enters the structure. A carrier may then separate covered wind damage from excluded or separately insured flood damage.
That makes photographs, weather information, inspection findings, moisture documentation, and a clear timeline especially valuable.
Severe Thunderstorms, Hail, and Wind
Fort Bend County’s hazard planning identifies severe weather as a high-risk hazard for Simonton, with hurricane/tropical storm and tornado risks also recognized.
Strong thunderstorms can damage roofing even when no dramatic failure is visible from the ground. Hail can bruise asphalt shingles, dent vents and gutters, damage metal roofing, affect siding, and create openings that later contribute to leaks.
Wind claims can become disputed when an insurer characterizes damage as wear, deterioration, installation problems, or long-term maintenance rather than storm-related damage. A detailed inspection helps separate old conditions from damage attributable to the reported event.
Common Insurance Claims in Simonton
Hail Damage Claims
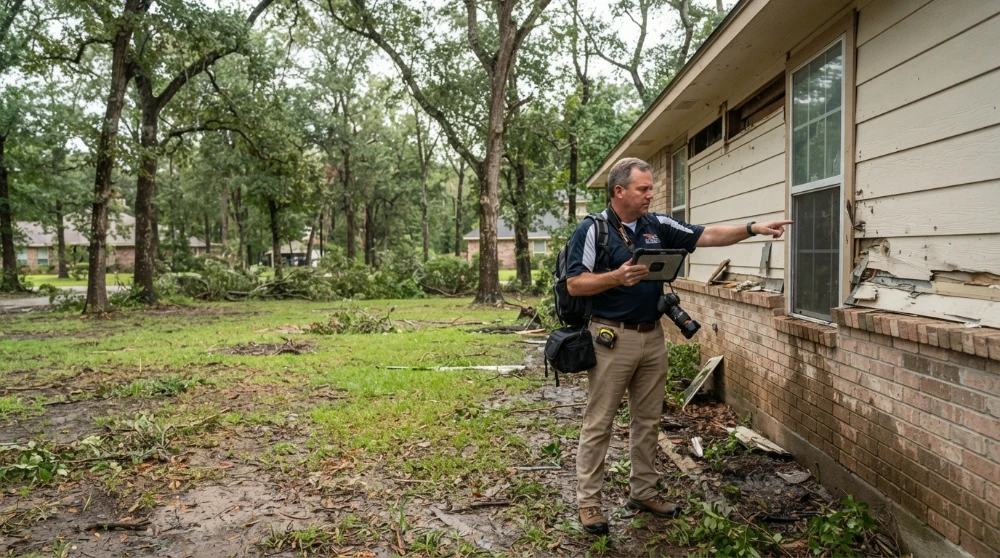
Hail can affect much more than shingles. A complete hail inspection may include the roof covering, vents, gutters, downspouts, flashing, siding, window screens, fencing, HVAC components, and detached structures.
One frequent claim problem is an estimate that addresses only the most obvious roof damage. If collateral damage is not documented, the carrier’s scope may not reflect everything affected by the storm. Property owners dealing with a hail damage roof insurance claim should also understand how roofing materials, accessories, and related exterior damage are evaluated.
TX Public Adjusting reviews hail claims from a policyholder perspective and helps organize the documentation needed to support the claimed damage.
Water Damage Claims
Water losses in Simonton may result from plumbing failures, roof leaks, wind-driven rain, appliance failures, burst pipes, or storm-created openings. A water damage public adjuster can help document the source, extent, and repair scope when the carrier’s estimate does not account for all affected areas.
The visible stain is rarely the entire story. Water can move into insulation, framing cavities, flooring systems, cabinets, electrical components, and adjacent rooms. Proper documentation can include moisture readings, mitigation records, photographs, damaged material quantities, and repair estimates.
For Simonton properties near low-lying areas or the Brazos River, identifying the source of the water is especially important because coverage can change depending on the cause.
Fire Damage Claims
Fire losses often extend far beyond the area directly burned.
A Simonton fire claim may involve:
- Structural damage
- Smoke contamination
- Soot
- Odor
- HVAC contamination
- Contents damage
- Water used during suppression
- Demolition
- Debris removal
- Temporary living expenses
- Code-related repair questions
Because smoke, soot, contents, structural damage, and suppression water can all become part of the same loss, working with a fire insurance adjuster who represents the policyholder can help ensure the claim is documented beyond the visibly burned areas. Our job is to help document the full covered loss rather than treating a fire claim as a single-room repair.
Storm Damage Claims
Severe thunderstorms, tropical systems, straight-line winds, lightning, hail, and tornado-producing storms can affect Simonton throughout the year.
Storm losses can involve roofing, trees, fences, detached structures, exterior finishes, windows, electrical equipment, and interior water damage at the same time.
The more components involved, the easier it becomes for items to disappear from an estimate.
Roof Damage Claims
Roof claims are among the most common property disputes we review.
Carrier estimates may propose a repair when contractors believe replacement is required, omit damaged accessories, underestimate quantities, or fail to account for related interior damage. Property owners facing an underpaid or disputed loss can learn more about working with a public adjuster for a roof claim before accepting the carrier’s scope.
We examine the roof damage together with the rest of the property instead of viewing the roof as an isolated component.
Commercial Property Claims
Simonton and the surrounding western Fort Bend County area include commercial buildings, agricultural-use properties, service businesses, retail operations, and properties with detached structures.
Commercial claims may involve:
- Flat or low-slope roofing
- Metal roofing systems
- Interior finishes
- Equipment
- Inventory
- Tenant improvements
- Water mitigation
- Business property
- Code requirements
- Multiple buildings on one site
Commercial losses can become highly detailed quickly, particularly when the carrier and property owner disagree over the repair scope.
Why Insurance Claims Become Underpaid
An insurance payment is based heavily on what makes it into the carrier’s documented scope. Some problems begin before the scope is even finalized. Avoiding common property insurance claim mistakes can help preserve documentation and reduce unnecessary disputes as the claim moves forward.
If important damage is missed during the original inspection, the estimate may start too low.
Missed Damage
Some damage is easy to see. Other damage requires a closer inspection.
Roof accessories, flashing, underlayment, interior moisture damage, adjacent finishes, detached structures, and exterior components may be overlooked during a brief carrier inspection.
Scope Omissions
A carrier may recognize that damage occurred but omit necessary related work.
Replacing damaged material can require removal and replacement of surrounding components. A claim scope should reflect the work reasonably required to restore covered property, subject to the policy.
Depreciation Issues
Depreciation affects many property claims, particularly roof claims.
Policyholders may receive an initial actual cash value payment and later become eligible to recover depreciation depending on policy terms and completion requirements. Confusion over recoverable versus non-recoverable depreciation can leave property owners unsure how much money is actually available.
Low Estimates
Insurance estimating depends on quantities, labor, materials, repair methodology, and pricing.
A low quantity or missing line item can affect the total significantly. Larger Simonton properties with fences, secondary structures, metal components, acreage improvements, or multiple buildings can create even more opportunities for omissions.
Documentation Problems
A valid claim can still become difficult when supporting documentation is incomplete.
Insurance companies regularly evaluate:
- Photographs
- Measurements
- Estimates
- Invoices
- Moisture records
- Damage inventories
- Repair documentation
- Proof of loss
- Policy provisions
Our role is to organize the claim so the damage and requested scope are supported clearly.
Our Public Adjusting Process
1. Claim Review
We begin by learning what happened and reviewing the current status of the insurance claim.
That may include the policy, carrier estimate, inspection reports, correspondence, photographs, contractor estimates, payments, denial letters, or supplement requests.
We also determine whether the issue is primarily missed damage, valuation, scope, causation, documentation, or a combination of several problems.
2. Property Inspection
We inspect the property and document the areas related to the reported loss.
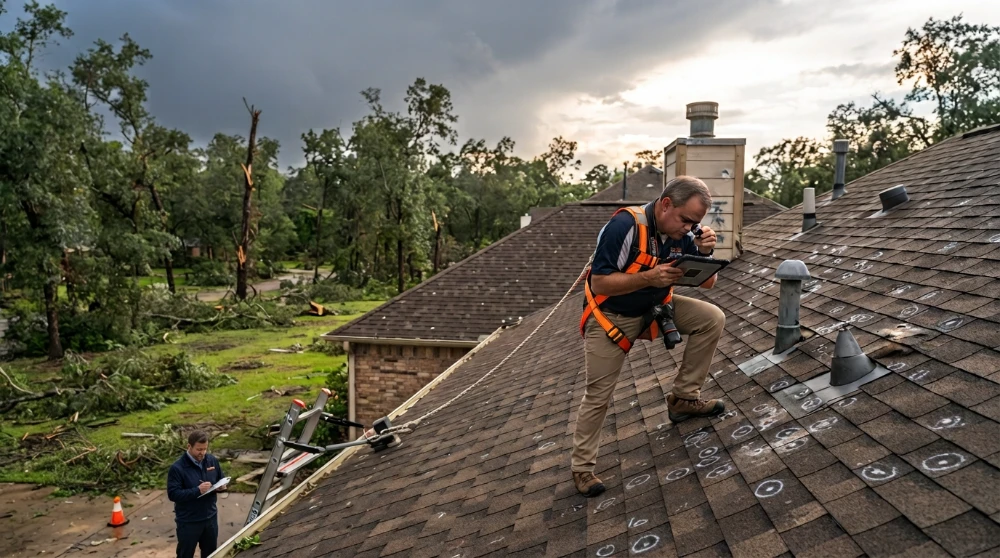
For a Simonton storm claim, that can mean looking beyond the primary roof and checking exterior elevations, gutters, metals, fencing, outbuildings, windows, interior water staining, and other affected components.
3. Documentation and Scope
We prepare a structured record of the claim.
That can include photographs, measurements, estimates, inventories, damage notes, supporting invoices, and other documentation relevant to the loss.
Thousands of claims have been reviewed across residential and commercial property situations, giving our team practical experience with the details that commonly cause disputes.
4. Insurance Company Communication and Negotiation
Once the damage is documented, we communicate with the insurance company regarding the scope and valuation of the covered claim.
When the carrier disagrees, we respond with documentation rather than guesswork.
5. Settlement and Claim Resolution
Our goal is to help the policyholder pursue the amount supported by the policy and documented damage.
Every claim is different, and no specific outcome can be guaranteed. What we can control is the quality of the inspection, documentation, presentation, and negotiation.
If your Simonton claim has already been inspected or paid, that does not necessarily mean the review is over. Request a Free Claim Review from TX Public Adjusting before assuming the carrier’s first estimate is complete.
Why Choose TX Public Adjusting
TX Public Adjusting focuses on Texas property claims and represents homeowners, commercial property owners, and other policyholders after covered property losses.
| What You Get | What It Means for Your Simonton Claim |
| Licensed Texas Public Adjuster | Rise Public Adjusting LLC, Texas License #3356839 |
| Policyholder Representation | We represent you, not the insurance carrier |
| Residential & Commercial Experience | Support for homes, businesses, multi-building properties, roofs, interiors, and contents |
| Detailed Claim Documentation | Inspections, photographs, measurements, estimating, and scope review |
| Texas Storm Experience | Familiarity with hail, wind, hurricane, roof, water, and severe-weather claims |
| Free Claim Review | Discuss your claim before deciding how to proceed |
| No Upfront Fees | No upfront fee for the initial claim review |
We understand insurance policies, estimating, scope preparation, claim documentation, and the negotiation process. That experience becomes especially important when a loss involves several causes or multiple damaged structures.
A Simonton public adjuster should do more than forward documents to the insurance company. The job is to identify what happened, document what was damaged, understand what the policy provides, and present a claim that can withstand scrutiny.
Insurance Claim Help for Valley Lodge and the Simonton Community
Simonton is small enough that generic neighborhood language does not make sense here. The city’s development pattern is centered around two genuinely distinct local areas: the historic Simonton core near FM 1093 and FM 1489, and Valley Lodge, which extends west toward the Brazos River.
Valley Lodge is particularly relevant when discussing property claims because of its proximity to the river and local floodplain considerations. The City of Simonton specifically references Valley Lodge in its building information and notes that property owners there may also have architectural review requirements through the property owners association.
We can assist qualifying residential and commercial claims throughout Simonton, including properties along the FM 1093 corridor, near the historic town center, in Valley Lodge, and in surrounding rural areas.
Areas We Serve Near Simonton
TX Public Adjusting serves policyholders throughout Fort Bend County and nearby communities.
From Simonton, the surrounding area includes Fulshear approximately five miles east, Wallis roughly seven miles southwest, Brookshire about ten miles north, and Rosenberg approximately sixteen miles southeast.
Nearby service areas include:
- Fulshear
- Wallis
- Brookshire
- Pattison
- Weston Lakes
- Richmond
- Rosenberg
- Katy
- Other Fort Bend County and western Houston-area communities
Property damage does not stop at city limits. Our team works with Texas policyholders across the region and throughout the state.
Frequently Asked Questions About Public Adjusters in Simonton
What does a public adjuster in Simonton do?
A public adjuster represents the policyholder during a property insurance claim. That can include reviewing the policy and carrier estimate, inspecting the damage, preparing documentation, estimating the loss, communicating with the insurer, and negotiating disputed portions of the claim.
TX Public Adjusting works for property owners—not insurance companies.
When should I hire a public adjuster after property damage in Simonton?
You can contact a public adjuster early in a large or complicated loss, but property owners also frequently seek help after receiving a low estimate, denial, partial payment, or confusing coverage decision.
The earlier a claim is reviewed, the easier it can be to preserve evidence and organize documentation. However, an existing payment does not automatically mean your options are exhausted. If your claim is already underway, our guide explaining when it is too late to hire a public adjuster covers several timing considerations for property owners.
Can a public adjuster help with a Simonton roof claim?
Yes. Roof claims are one of the primary property claim types we review.
We can examine storm damage, carrier measurements, repair versus replacement scope, roofing accessories, exterior components, and related interior damage to determine whether the insurer’s estimate appears to address the documented covered loss.
Do you handle hail claims in Simonton?
Yes. Hail can damage shingles, metal roofs, vents, gutters, siding, windows, screens, HVAC components, and other exterior materials.
A hail claim should be based on the damage actually documented at the property rather than assumptions based only on what can be seen from the ground.
Can you help after hurricane or tropical storm damage?
Yes. Simonton can experience wind, heavy rainfall, tornado activity, tree impacts, roof damage, and water intrusion from tropical systems moving inland.
These claims can become complicated when wind damage and flood-related damage occur during the same event. We review the available policy and property evidence to help establish the documented covered portion of the loss.
What if my Simonton property flooded?
Flooding requires special attention because coverage depends heavily on the source of the water and the insurance policy involved.
Damage from rising surface water or river flooding may fall under a separate flood policy, while water entering through a storm-created roof or building opening can present different coverage questions. We review the available facts and policy documents before determining how we may be able to assist.
Can you help if my insurance company already paid the claim?
Possibly. Many policyholders contact us because they believe the payment does not match the actual cost or scope of repairs.
We can review the carrier estimate, property damage, documentation, and policy information to determine whether potentially covered items appear to have been omitted or undervalued.
How much does a public adjuster cost in Texas?
Public adjusting fees are generally addressed in a written agreement and may depend on the type and stage of the claim.
TX Public Adjusting offers a Free Claim Review and no upfront fees so you can discuss your situation before deciding whether representation makes sense.
Do public adjusters work for the insurance company?
No. A public adjuster represents the policyholder.
Insurance companies have adjusters who investigate claims for the carrier. TX Public Adjusting independently represents Texas homeowners and commercial property owners.
Why is local flood risk so relevant to Simonton claims?
Simonton’s location beside the Brazos River creates unusual water-risk considerations compared with many other Texas communities. City planning documents estimate that roughly three-quarters of Simonton is currently within the 100-year floodplain, with future mapping expected to expand the mapped floodplain further.
That does not mean every water loss is a flood claim. It does mean determining the source and sequence of water intrusion is especially important when documenting a Simonton property loss.
Get a Free Simonton Insurance Claim Review
If your Simonton home, business, roof, or other property has been damaged, you do not have to rely solely on the insurance company’s estimate to understand the value of your claim.
TX Public Adjusting can review:
- Underpaid insurance claims
- Hail and roof claims
- Wind and storm losses
- Hurricane damage
- Water damage
- Fire and smoke claims
- Commercial property claims
- Claims involving missing or disputed damage
Rise Public Adjusting LLC
Texas Public Adjuster License #3356839
Get a Free Claim Review with no upfront fees.
Contact TX Public Adjusting to discuss your Simonton property damage claim and find out whether the carrier’s scope deserves a closer look.