Property damage in Providence Village can turn into an insurance dispute faster than many homeowners expect. A North Texas hailstorm can damage shingles, gutters, window screens, fencing, and exterior finishes in a matter of minutes. Strong winds can loosen roofing components and allow rain into attics or walls. A winter freeze can lead to burst pipes and extensive interior water damage. When the carrier’s estimate does not account for the full scope of the loss, the property owner is left trying to prove what was damaged and what it will actually cost to restore.
TX Public Adjusting provides Public Adjuster Providence Village services for residential and commercial property owners dealing with damaged, delayed, denied, or underpaid insurance claims. We represent the policyholder—not the insurance company—and help document the loss, review policy provisions, prepare estimates, communicate with the carrier, and negotiate the claim.
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839. Our team has reviewed thousands of property claims involving roofs, hail, wind, water, fire, and commercial losses throughout Texas.
Providence Village has characteristics that deserve more than a generic North Texas claims page. The town began as a master-planned community and is known for Cape Cod and Craftsman-style homes. That combination of distinctive residential construction and Denton County’s severe-weather exposure makes detailed property documentation especially valuable after a loss.
Need help with a claim now? Request a Free Claim Review from TX Public Adjusting. There are no upfront fees for the initial claim review.
Property Claims in a Distinctive Providence Village Community
Providence Village is not simply another subdivision along the rapidly developing U.S. 380 corridor. The community was developed beginning in 2000, and its architecture was intentionally built around Cape Cod and Craftsman influences. The town later incorporated in 2010.
Those details matter when evaluating property damage.
A carrier estimate should not stop at a few missing shingles after a hail or wind event. Depending on what was damaged and what the policy covers, a complete scope may need to address roofing materials, flashing, vents, gutters, siding, trim, windows, interior finishes, fencing, detached structures, and other components affected by the same event.
The physical layout of the community also gives Providence Village a recognizable local character. The Providence HOA identifies seven community lakes, including the roughly 25-acre Lake Providence, along with greenbelts, trails, parks, pools, and other neighborhood amenities. For homeowners around these established residential sections, restoring storm damage correctly often means paying close attention to exterior materials and interconnected building components rather than treating each visible mark as an isolated repair.
Our job as a public adjuster is to look at the property as a complete loss—not merely the handful of line items that happened to appear on an insurer’s first estimate.
Why Property Owners Hire a Public Adjuster in Providence Village
Insurance companies have adjusters who investigate claims on behalf of the carrier. A public adjuster has a different role. That distinction becomes particularly important after storm damage. Our guide comparing a public adjuster vs. insurance adjuster for hail claims explains who each adjuster represents and how their responsibilities differ during a Texas property claim.
A public adjuster is hired by the policyholder.
That distinction becomes especially important when the amount offered by an insurance company does not appear to match the actual damage. A homeowner may receive an estimate that allows for limited roof repair while a contractor identifies broader storm damage. An interior water claim may account for drywall but omit flooring, cabinetry, insulation, or necessary adjoining work. A fire estimate can miss smoke migration, contents, cleaning, electrical concerns, or other portions of the loss.
Property owners commonly contact TX Public Adjusting when:
- The insurance estimate appears too low.
- Damage was left out of the carrier’s scope.
- A roof claim was partially denied or limited to repairs.
- The insurer and contractor disagree about the extent of damage.
- A claim involves several rooms or multiple building components.
- Depreciation or replacement-cost calculations are confusing.
- The owner does not have time to manage repeated inspections and carrier requests.
- A previously filed claim needs another detailed review.
- A commercial loss is disrupting business operations.
- Documentation has become too complicated to manage alone.
Our role is not to manufacture damage or promise a particular settlement. It is to identify and document legitimate covered damage, present the claim clearly, and advocate for the policyholder based on the policy and facts of the loss.
North Texas Storm Risks Affecting Providence Village Properties
Denton County’s hazard planning specifically includes high winds, tornadoes, winter storms, hail, flooding, lightning, extreme heat, wildfire, and other hazards, and Providence Village is one of the participating jurisdictions in the county’s mitigation planning. For property claims, hail, wind, water intrusion, lightning, and freeze-related losses are especially relevant.
Hail and Roof Damage
Hail deserves particular attention in this part of Texas. Denton County has a documented history of severe hailstorms; the National Weather Service has recorded events involving very large hail across the county. For Providence Village homeowners, understanding how a hail damage roof insurance claim is documented can make it easier to identify what should be reviewed after a severe storm.
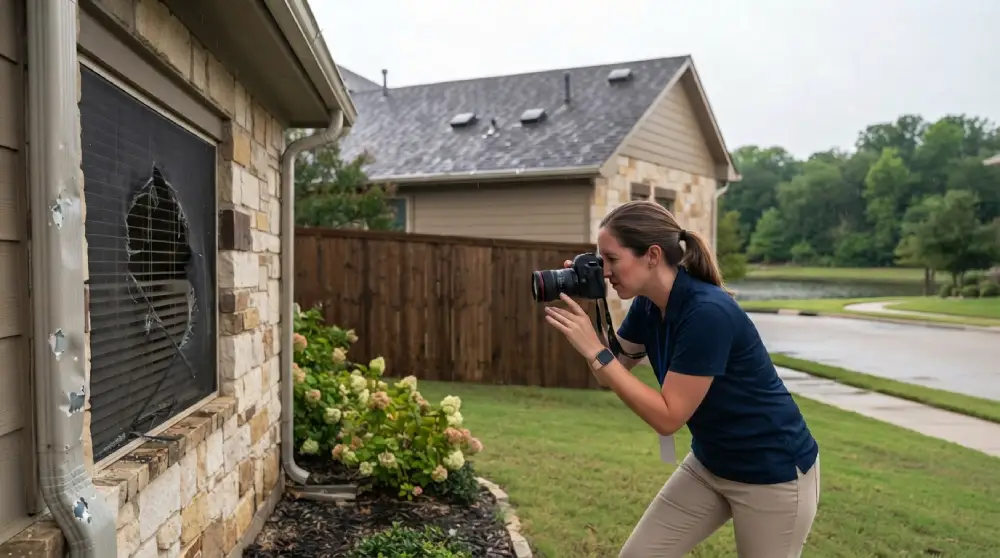
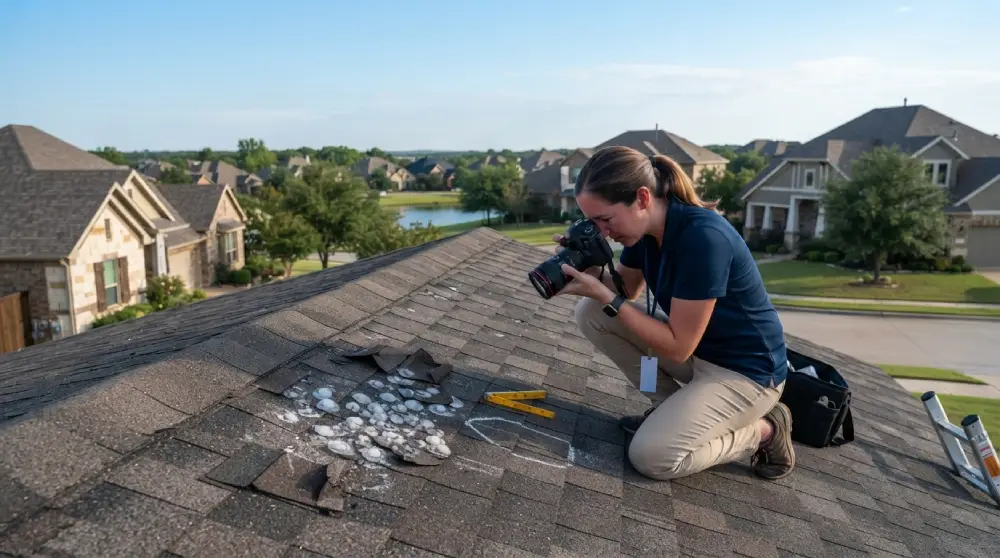
Hail damage is not always obvious from the driveway. On an asphalt-shingle roof, an inspection may reveal displaced granules, impact marks, damaged matting, or compromised shingles. Metal vents, gutters, downspouts, flashing, window screens, fencing, and exterior finishes can provide additional evidence of a storm’s effects.
The problem arises when an insurance inspection recognizes some of that evidence but not all of it.
A Providence Village hail claim may require documentation of:
- Roof slopes and affected elevations
- Shingle impact damage
- Ridge and hip components
- Flashing and roof vents
- Gutters and downspouts
- Window screens
- Exterior trim
- Garage doors and other finishes
- Fencing
- Interior staining if the storm created an opening for water
A complete claim should connect those observations to the date and cause of loss instead of treating damage as a collection of unrelated repairs.
Straight-Line Wind and Tornado-Producing Storms
Wind losses can be equally complicated. Strong thunderstorm winds may crease or lift shingles, affect flashing, damage fences, break tree limbs, and drive rain into vulnerable portions of the building envelope.
North and Central Texas saw another reminder of that exposure in April 2026, when the National Weather Service documented a six-day period of severe thunderstorms involving large hail, damaging winds, flash flooding, and tornadoes across the region. That event should not be interpreted as evidence that every property in Providence Village was damaged; it demonstrates the broader severe-weather environment in which Denton County properties sit.
After a wind event, photographs of one missing shingle may not tell the whole story. We examine the roof and exterior in context and document related damage where present.
Wind-Driven Rain and Interior Water Damage
Storm claims can become much larger once water gets inside.
Moisture may affect attic insulation, ceilings, drywall, paint, flooring, trim, cabinets, and personal property. Drying and mitigation work can introduce another layer of invoices and documentation.
One of the most important questions is why the water entered the building. Coverage depends on policy language and the cause of loss. That is why storm documentation should clearly connect interior damage with the exterior conditions and covered event being claimed.
Winter Freeze and Plumbing Losses
North Texas is also exposed to winter weather. The National Weather Service documented widespread mixed precipitation and persistent frigid temperatures across North and Central Texas during the January 2026 winter storm.
Freezing temperatures can contribute to plumbing failures that produce significant water losses. A pipe break inside a wall or ceiling may damage drywall, insulation, flooring, cabinetry, baseboards, and contents before the water is shut off.
For these claims, documenting moisture migration and all affected materials can be just as important as documenting the failed plumbing component itself.
Common Insurance Claims in Providence Village
| Claim Type | Damage We Commonly Review | Items That May Need Closer Attention |
| Hail Damage | Shingles, vents, gutters, screens, siding | Full roof scope, soft metals, elevations, associated exterior damage |
| Roof Damage | Shingles, flashing, decking, penetrations | Repairability, matching, adjoining components, interior leaks |
| Wind & Storm | Roofing, fencing, exterior finishes | Lifted materials, wind-driven rain, debris impacts |
| Water Damage | Ceilings, walls, floors, cabinets | Moisture extent, demolition, drying, adjoining finishes |
| Fire & Smoke | Structure, contents, finishes | Soot, smoke migration, cleaning, electrical and contents issues |
| Commercial Property | Roofs, interiors, equipment, tenant areas | Business-specific repair scope and coordinated documentation |
Hail Damage Claims
A hail claim should tell a consistent story—from weather event to exterior evidence to repair scope.
We help Providence Village property owners organize photographs, measurements, estimates, inspection findings, and carrier documents so legitimate storm damage is clearly presented. If the insurer has already inspected the property, we can compare its estimate against the observed damage and identify potential omissions. If the carrier has rejected some or all of the damage, review what to do if your hail claim was denied for additional steps that may be available when the initial decision does not appear to reflect the documented loss.
Water Damage Claims
Water moves beyond the place where it first becomes visible.
A ceiling stain may point to wet insulation above it. A plumbing loss under a cabinet can spread into flooring or adjacent rooms. Drying equipment may be necessary even when the surface looks dry.
Our water damage public adjuster team reviews the cause of loss, affected areas, mitigation records, repair requirements, and the insurer’s scope.
Fire Damage Claims
Fire losses involve more than burned materials. Heat, smoke, soot, firefighting water, contents, and cleaning requirements may all become part of the claim.
A significant residential fire can require coordination across structural repairs, personal-property inventories, temporary living arrangements, remediation, and numerous estimates. Detailed organization matters because a missing category can materially change the overall scope.
Storm Damage Claims
A severe storm may cause hail, wind, rain, debris, and roof damage during the same event.
Instead of documenting only the most obvious damage, TX Public Adjusting looks for the complete relationship between the event and the property. We also review what the insurer has already acknowledged and where further documentation may be warranted.
Roof Damage Claims
Roof claims are one of the most common reasons Texas property owners call a public adjuster for a roof claim, particularly when there is disagreement over hail damage, repairability, replacement scope, or omitted roofing components.
Disputes frequently involve the extent of hail damage, repair versus replacement, omitted accessories, depreciation, labor, or differences between a contractor’s estimate and the carrier’s scope.
The goal is not automatically to demand a replacement. The goal is to document what actually happened and determine whether the carrier’s scope reflects the covered damage.
Commercial Property Claims
Although Providence Village is heavily residential, TX Public Adjusting also handles commercial claims for local and nearby businesses facing the same North Texas hail, wind, water, and storm hazards.
Commercial claims may involve larger roofing systems, interior finishes, mechanical equipment, inventory, tenant spaces, signage, or interruption to normal operations. These losses require disciplined documentation because several vendors and stakeholders may be involved at once.
If your estimate looks incomplete, do not assume the first number is the final word. TX Public Adjusting offers a Free Claim Review so you can understand what the insurer included—and what may have been missed.
Why Insurance Claims Become Underpaid
An insurance estimate can be lower than expected without the property owner immediately understanding why. Often, the difference is found in the scope rather than a single dramatic mistake.
Missed Damage
The adjuster’s inspection may not identify every affected component. Roof accessories, gutters, elevations, interior moisture, trim, fencing, or secondary areas can be overlooked.
Scope Omissions
The carrier may recognize damage but omit work necessary to complete the repair properly. That can create a substantial difference between an insurance estimate and the actual restoration estimate.
Depreciation Issues
Replacement-cost and actual-cash-value calculations can be difficult to interpret. We review how depreciation has been applied and how the policy addresses recoverable amounts.
Low or Incomplete Estimates
Differences in measurements, quantities, material assumptions, labor, and line items can change an estimate significantly.
Documentation Problems
Even valid damage can be difficult to resolve if the file lacks photographs, measurements, invoices, reports, or a clear explanation tying the damage to the claimed event.
TX Public Adjusting approaches these issues systematically. We compare the property conditions, policy, carrier paperwork, and available supporting documents rather than focusing only on the settlement check.
Our Public Adjusting Process
1. Claim Review
We begin by understanding what happened and where the claim currently stands.
That can include reviewing the policy, carrier estimate, settlement letters, photographs, contractor estimates, mitigation invoices, correspondence, and other available documents. You can contact us before a major claim is fully documented or after you believe an existing Providence Village claim has been underpaid.
2. Property Inspection
We inspect the relevant portions of the loss and identify visible damage that should be documented.
For a hail claim, this may include roofing, vents, flashing, gutters, siding, screens, fencing, and interior areas where storm-related water entered. Water and fire claims require a different inspection approach based on the cause and extent of damage.
3. Documentation and Scope Development
Next, we organize the evidence.
Depending on the loss, that can involve photographs, measurements, inventories, estimates, invoices, reports, and a detailed repair scope. A strong claim file should give the insurer enough information to understand what is being requested and why.
4. Carrier Communication and Negotiation
Once retained, TX Public Adjusting communicates with the insurance company regarding the claim within the scope of our representation.
We address estimate differences, documentation requests, disputed line items, and other claim issues. The objective is a well-supported resolution based on the policy and documented loss.
5. Settlement and Claim Resolution
We review settlement developments with the policyholder and continue working through outstanding covered items as appropriate.
No public adjuster can guarantee a particular outcome. Every claim depends on its facts, policy terms, exclusions, deductibles, evidence, and carrier review. Our responsibility is to advocate professionally for the policyholder and build the strongest legitimate claim supported by the loss.
Why Choose TX Public Adjusting
Property owners should know exactly who is representing them.
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839. We focus on Texas property claims and represent policyholders rather than insurance carriers.
Our experience includes thousands of claim reviews across residential and commercial losses. That work has exposed our team to the recurring problems that make property claims difficult: incomplete scopes, conflicting estimates, documentation gaps, depreciation questions, roof disputes, water mitigation issues, contents documentation, and prolonged communication with insurers.
Clients choose us for:
- Licensed Texas representation — Rise Public Adjusting LLC, License #3356839.
- Policyholder-focused advocacy — our role is to represent you, not the insurance company.
- Residential and commercial experience — from single-family roof losses to larger business-property claims.
- Detailed documentation — we focus on building a clear claim file, not simply arguing over a number.
- Texas storm experience — hail, wind, water, freeze, fire, and other property losses are central to our work.
- Free Claim Review — discuss your existing claim and documents before deciding how to proceed.
- No upfront fees for the initial review — representation terms and fees are explained before you retain us.
Providence Village Neighborhoods and Local Areas We Serve
Local familiarity matters because the town is made up of identifiable residential sections rather than one uniform block of homes. Recognized Providence Village neighborhood names include Creek Village, Eagle Village, Harbor Village, Island Village, Liberty at Providence, and The Landing at Providence.
The town’s original master-planned areas are also tied together by recognizable community features such as Lake Providence, neighborhood greenbelts, trails, the Oakcrest-area clubhouse facilities, and other HOA amenities.
Fishtrap Road is another useful local reference point: the town itself notes that Providence Village is served by both Aubrey ISD and Denton ISD, with the dividing area described around Fishtrap Road.
Our service area also extends beyond the town limits to nearby Denton County communities including Aubrey, Cross Roads, Little Elm, Oak Point, Savannah, and Paloma Creek South. These communities share much of the same North Texas hail, wind, and winter-weather exposure. Frequently Asked Questions About Public Adjusters in Providence Village
What does a public adjuster in Providence Village do?
A public adjuster represents the property owner during an insurance claim. We review the loss and insurance documents, inspect and document damage, prepare or evaluate the scope, communicate with the insurance carrier, and negotiate disputed claim issues.
Unlike an insurance-company adjuster, a public adjuster is retained by the policyholder. TX Public Adjusting works for homeowners and business owners—not their insurance companies.
When should I hire a public adjuster after a Providence Village hailstorm?
You can contact a public adjuster early in a large or complicated hail claim, but homeowners also call us after receiving an insurer estimate that appears incomplete.
If the carrier has already inspected the roof and you are concerned about missing slopes, omitted gutters, damaged vents, exterior components, or a repair scope that does not match the actual condition, a second claim review can help clarify the differences.
Can you help if my roof claim has already been underpaid?
Potentially. An existing payment does not necessarily answer whether every covered part of a loss was properly documented, although the options available depend on the policy and status of the claim.
We can review the insurer’s estimate, photographs, contractor documents, correspondence, and available evidence to identify discrepancies. From there, we can explain whether public-adjuster involvement makes sense for the situation.
What types of storm claims are common around Providence Village?
Denton County identifies hail, high winds, tornadoes, winter storms, flooding, and lightning among its recognized hazards. In our work, the property claims most closely associated with those conditions include hail-damaged roofs, wind damage, storm-created water intrusion, and freeze-related plumbing losses.
The exact coverage always depends on the policy and cause of loss. For example, surface flood damage can involve different insurance coverage than wind-driven rain or a burst plumbing line.
How do I know if my insurance estimate is too low?
Start by comparing the insurer’s scope with the actual damaged property and credible repair estimates. Look for missing rooms, elevations, roof accessories, quantities, labor operations, exterior components, or other damage connected to the loss.
The total dollar figure alone does not tell you where the problem is. TX Public Adjusting reviews the underlying scope line by line so the discussion is based on specific omissions and differences.
Can a public adjuster help with water damage from a frozen pipe?
Yes, when the loss is covered and public adjusting is appropriate for the claim. A major plumbing failure can affect more than the location of the broken pipe.
Water may travel through insulation, ceilings, walls, flooring, cabinets, trim, and adjoining spaces. Documentation should account for the actual extent of affected materials, mitigation work, and necessary repairs.
Does TX Public Adjusting handle fire claims in Providence Village?
Yes. We handle residential and commercial fire and smoke claims in Texas. Fire losses can involve structural repairs, smoke and soot, contents, cleaning, electrical issues, water used during firefighting, and temporary living expenses where applicable under the policy.
Because there can be many separate categories of loss, fire claims benefit from organized documentation and careful tracking. A fire insurance adjuster can help organize the structural, contents, smoke, soot, and other documented portions of the claim.
How much does it cost to hire a public adjuster?
Public-adjuster fees depend on the engagement and applicable Texas requirements. The specific fee and terms should be disclosed in your written agreement before representation begins.
TX Public Adjusting offers a Free Claim Review with no upfront fee so you can discuss your situation and understand the next step before making a hiring decision.
Is it too late to hire a public adjuster after the insurer has paid my claim?
Not automatically. The answer depends on the status of the claim, the policy, the time that has passed, the documents available, and whether unresolved covered damage remains. Our detailed guide explains when it is too late to hire a public adjuster and the factors property owners should consider before reopening or disputing an older claim.
If you have already received payment but believe the estimate omitted significant property damage, bring us the carrier estimate, payment information, photographs, and relevant repair estimates. We can review the situation and explain the available next steps.
Why use a local Texas public adjuster for a Providence Village property claim?
Texas property claims come with recurring regional issues, particularly hail, wind, roof damage, freeze losses, and severe thunderstorms. A Texas-focused public adjuster is accustomed to evaluating these losses and reviewing the kinds of scope disagreements that follow them.
TX Public Adjusting also understands that a master-planned community such as Providence Village has its own building styles, neighborhood sections, and exterior features. We approach the property as a real local home or business—not as a city name inserted into a generic claim template.
Get a Free Claim Review in Providence Village
If your home or commercial property has been damaged by hail, wind, water, fire, a plumbing failure, or another covered event, you do not have to determine the value of the claim from the carrier’s estimate alone.
TX Public Adjusting can review what happened, what the insurance company documented, and where additional claim work may be appropriate.
TX Public Adjusting
Rise Public Adjusting LLC
Texas License #3356839
Free Claim Review | No Upfront Fee for the Initial Review | Residential & Commercial Claims
Contact TX Public Adjusting to discuss your Providence Village property damage claim and find out what the next step should be.