

Property damage in Oyster Creek can become complicated quickly. This small Brazoria County community sits only a few miles from the Gulf Coast, where homes and businesses can face hurricane winds, tropical rainfall, wind-driven water, roof damage, and flooding-related losses. When an insurance carrier’s estimate does not reflect the full extent of covered damage, a Public Adjuster in Oyster Creek, TX can represent the policyholder and build a more complete claim.
TX Public Adjusting helps residential and commercial property owners document, prepare, and negotiate insurance claims throughout Oyster Creek and the surrounding Brazosport area. We work for you, the policyholder—not the insurance company.
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839. Our team has experience reviewing thousands of property claims involving storms, hail, water, fire, roofing systems, and commercial losses.
Need help with an Oyster Creek insurance claim? Request a Free Claim Review. There are no upfront fees.
Oyster Creek is an incorporated community in southern Brazoria County, approximately six miles from Surfside Beach and about ten miles east of Lake Jackson. The city developed as a fishing community before becoming part of the larger Brazosport industrial and port area. Its waterfront setting and proximity to the Texas coast create a property-loss profile very different from inland Texas communities.
Why Property Owners Hire a Public Adjuster in Oyster Creek
Filing an insurance claim is not simply a matter of reporting damage and waiting for a check.
The insurance company investigates the loss, interprets the policy, determines what damage it believes is covered, develops an estimate, applies deductibles and depreciation, and decides what it believes should be paid.
A public adjuster approaches the claim from the policyholder’s side.
For Oyster Creek property owners, that can be especially valuable after a major Gulf Coast storm when damage may involve several parts of the building at once. A single wind event can affect roofing, flashing, gutters, siding, windows, fencing, exterior equipment, ceilings, insulation, drywall, flooring, and electrical components.
Our role may include:
- Reviewing the insurance policy and existing claim documents
- Inspecting residential or commercial property damage
- Identifying damage missing from an insurer’s scope
- Photographing and documenting affected areas
- Reviewing carrier estimates and measurements
- Preparing a detailed property-loss estimate
- Organizing supporting claim documentation
- Communicating with the insurance carrier
- Addressing scope and valuation disagreements
- Negotiating the covered property claim on the policyholder’s behalf
That representation can be useful when an Oyster Creek insurance claim has been underpaid, delayed, partially denied, or simply becomes too complex for the property owner to handle alone.
Oyster Creek Property Damage Has a Gulf Coast Risk Profile
Oyster Creek is not an inland Texas suburb. Geography matters here.
The community sits on the coastal plain of southern Brazoria County near Surfside Beach, Freeport, waterways, industrial facilities, and the Gulf of Mexico. Oyster Creek itself runs along the community, while the greater Brazosport region includes extensive waterways and low-lying coastal terrain.
Brazoria County has also administered disaster-recovery programs tied to significant flooding and Hurricane Harvey, illustrating the area’s continuing exposure to major weather events.
Hurricanes and Tropical Storms
Hurricanes can create several separate insurance issues within the same Oyster Creek property.
High winds may loosen shingles or roofing membranes. Flashing can lift. Wind-driven rain may enter openings that are difficult to identify immediately. Exterior components may be damaged by debris. Commercial buildings may experience rooftop equipment damage in addition to roofing losses.
The claim must distinguish between what happened, where water entered, which components were damaged, and how the policy applies to each part of the loss.
That is one reason detailed documentation after a tropical storm matters. Property owners dealing with wind, rain, roof, or interior damage can also review our guide to hurricane damage claims in Texas for a closer look at the claims process after a major storm.
Heavy Rain and Water Intrusion
Coastal storms can produce intense rainfall long before or after the strongest winds arrive.
Property owners may discover:
- Ceiling stains
- Wet insulation
- Damaged drywall
- Swollen flooring
- Interior paint damage
- Moisture around windows and doors
- Water behind wall assemblies
- Damaged contents
Coverage can depend heavily on the cause of the water. Rain entering through storm-created roof damage can present different policy questions than surface flooding.
A public adjuster documents the physical damage and helps present the covered portion of the loss according to the policy.
Coastal Flooding and Flood-Related Issues
Oyster Creek’s elevation and proximity to waterways make flood awareness particularly relevant. The city includes waterfront and canal-oriented properties, and Brazoria County has a substantial history of flood recovery and mitigation work.
Flood losses deserve careful coverage review because a standard property policy and a separate flood policy may respond differently.
TX Public Adjusting can review the circumstances of the loss and available policies to determine what portions of the damage should be presented under applicable coverage.
Wind and Roof Damage
Even without a named hurricane, strong Gulf Coast thunderstorms can damage Oyster Creek roofs.
Wind may:
- Crease or remove shingles
- Lift roof edges
- Damage ridge caps
- Separate flashing
- Damage vents
- Affect gutters and downspouts
- Damage low-slope commercial roofing
- Create openings that allow interior water intrusion
The visible roof problem may be only part of the claim.
Hail Damage
Hail is usually discussed more frequently in North Texas, but severe thunderstorms occur throughout the state, including the Gulf Coast.
When hail affects Oyster Creek, we inspect not only roof coverings but also collateral surfaces that may help establish the extent of the event, including vents, gutters, metal components, siding, screens, HVAC equipment, and other exterior finishes.
Common Insurance Claims in Oyster Creek
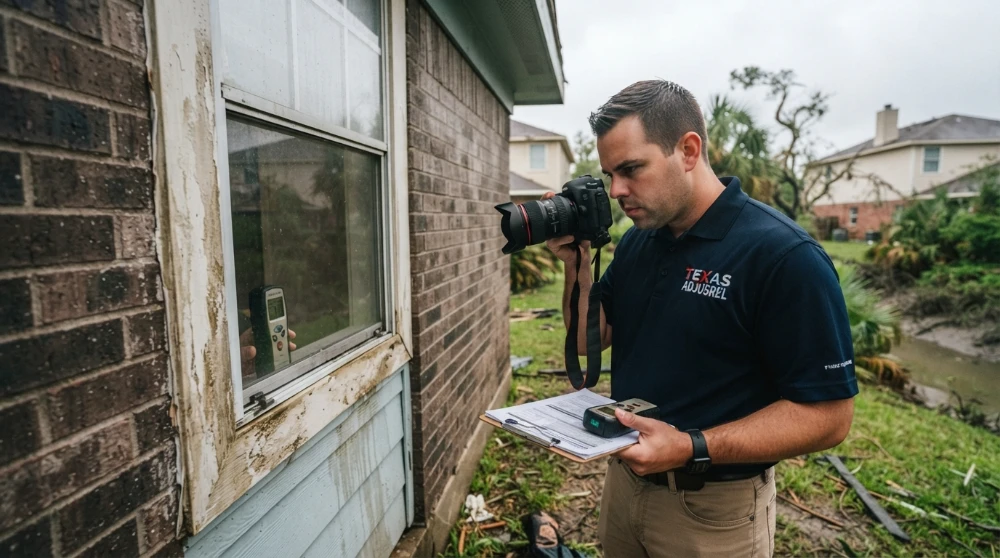
Hail Damage Claims
Hail damage is not always obvious from the ground.
Asphalt shingles may show impact marks or displaced granules. Metal roofing can develop dents. HVAC fins, gutters, vents, and soft metals may show clearer evidence than the roof covering itself.
For an Oyster Creek hail damage roof insurance claim, TX Public Adjusting can inspect the loss, compare our findings with the carrier’s estimate, and identify areas that may require additional documentation.
Water Damage Claims
Water claims often become disputes over cause, extent, and repair scope.
A carrier may acknowledge visible drywall damage while overlooking wet insulation, affected flooring, cabinets, baseboards, painting requirements, demolition needs, or related repairs.
Our job is to document the full covered loss rather than stopping at the first visible symptom. A water damage public adjuster can also review the carrier’s scope for missing interior components, mitigation-related issues, and resulting damage.
Fire Damage Claims
A fire claim may involve much more than burned building materials.
Smoke can migrate through a structure. Contents may need detailed inventory work. HVAC systems can become contaminated. Electrical components may require evaluation. Water used during firefighting can create additional damage.
TX Public Adjusting helps organize these moving parts into one documented claim. A fire insurance adjuster can evaluate structural damage, smoke-related damage, contents, and other covered components as part of the claim.
Storm Damage Claims
Storm claims in Oyster Creek may combine wind, rain, falling debris, damaged roofing, exterior building damage, and interior water intrusion.
Properties near the creek, FM 523 corridor, and the broader Brazosport industrial area can have very different construction types and exposures. A small residential roof claim should not be scoped the same way as a commercial building or industrial-support property.
Roof Damage Claims
Roof claims are among the property losses most likely to generate disagreements about scope.
Common disputes include:
- Repair versus replacement
- Number of damaged slopes
- Roofing accessory replacement
- Flashing
- Underlayment
- Drip edge
- Ventilation components
- Low-slope roofing details
- Matching issues
- Interior resulting damage
TX Public Adjusting reviews both the physical roof and the carrier’s estimate so the claim reflects covered damage that can be supported. If the insurer’s inspection or estimate does not account for the complete loss, working with a public adjuster for a roof claim can provide an independent review of the documented damage.
Commercial Property Claims
Oyster Creek is part of the wider Brazosport industrial and port economy. The city itself describes its community as both residential and industrial, while nearby Freeport and the Port Freeport area support substantial commercial activity.
Commercial losses can involve warehouses, offices, retail properties, service businesses, multifamily buildings, industrial-support facilities, and other income-producing properties.
Commercial claims may require documentation of:
- Roofing systems
- Building envelope damage
- Interior finishes
- Machinery or equipment
- Business personal property
- Tenant improvements
- Cleanup and mitigation
- Code-related repairs
- Business interruption when applicable under the policy
For owners responsible for a commercial Oyster Creek insurance claim, working with a commercial public adjuster can help organize building damage, equipment losses, documentation, carrier estimates, and other parts of a complicated commercial property claim.
Why Oyster Creek Insurance Claims Become Underpaid
An underpaid claim does not always result from one major disagreement.
Sometimes the problem is twenty small omissions.
Missed Damage
A carrier inspection can happen quickly, particularly after a widespread storm when adjusters are managing large claim volumes.
Damage behind finishes, on secondary roof elevations, around flashing, or inside wall and ceiling assemblies may not appear in the initial estimate.
Scope Omissions
An estimate may recognize damage while leaving out necessary work associated with completing the repair.
Examples include detach-and-reset operations, roofing accessories, painting adjacent surfaces, insulation, trim, disposal, access costs, or related labor.
Depreciation Issues
Insurance estimates may include depreciation based on age, condition, or policy provisions.
Property owners frequently receive an estimate without fully understanding what has been withheld or whether recoverable depreciation may become available after repairs.
Low Estimates
Two estimators can inspect the same Oyster Creek property and produce very different scopes.
The issue may involve quantities, labor assumptions, repair methodology, materials, or simply items one estimator noticed and another did not.
Documentation Problems
Insurance claims are evidence-driven.
Poor photographs, incomplete inventories, missing invoices, unclear timelines, and undocumented repairs can make a legitimate claim harder to evaluate.
A strong file makes it easier to explain exactly what happened and what covered repairs are being requested.
Our Public Adjusting Process
TX Public Adjusting uses a structured process designed to turn a complicated property loss into an organized insurance claim.
1. Claim Review
We begin by reviewing the loss, policy information, carrier correspondence, estimates, payments, and any existing documentation.
If the insurance company has already issued an estimate or settlement, we examine what has and has not been included.
2. Property Inspection
We inspect the damaged property and document relevant conditions.
For an Oyster Creek storm claim, that may include the roof, exterior, interior water intrusion, windows, doors, fencing, detached structures, equipment, or commercial building components.
3. Documentation and Scope
We develop the documentation needed to support the claim.
Depending on the loss, that may include photographs, measurements, inventories, estimates, invoices, contractor information, repair requirements, and other supporting evidence.
4. Carrier Communication and Negotiation
TX Public Adjusting communicates with the insurance company regarding documented differences in the claim.
We address questions involving scope, quantities, pricing, missing items, and other claim issues within the role of a licensed Texas public adjuster.
5. Settlement and Claim Resolution
We continue working through the adjustment process until the claim reaches an appropriate resolution based on the documented covered loss and applicable policy.
Already received a settlement that appears too low? A claim does not necessarily become final simply because the carrier issued its first estimate. If your claim is already underway, learn when it is too late to hire a public adjuster or contact TX Public Adjusting for a Free Claim Review.
Oyster Creek Homes Require Local Claim Knowledge
Oyster Creek is small enough that describing it using a list of invented subdivisions would miss the character of the community.
Property patterns are better understood around Oyster Creek itself, FM 523, the Municipal Park area, waterfront and canal properties, and routes connecting the city toward Freeport and Surfside Beach.
The city’s Municipal Park bordering the creek is one of its most recognizable local features, with fishing, picnic areas, and a splash pad. Surfside Beach is only about six miles away, while Lake Jackson lies roughly ten miles west.
Those locations also help explain the area’s insurance exposures.
A waterfront residence near Oyster Creek may have different wind and water vulnerabilities than a commercial building closer to FM 523. Properties toward Surfside Beach face increasingly direct coastal weather exposure, while properties connected to the Brazosport industrial corridor can involve more complicated commercial roofing, equipment, and building-envelope claims.
Local context matters when documenting a loss.
Why Choose TX Public Adjusting
Property owners do not have to rely solely on the insurance company’s adjustment of their claim.
A licensed public adjuster provides independent representation for the policyholder.
Licensed Texas Public Adjuster
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839.
Licensing matters because public adjusting involves policy review, insurance claim preparation, documentation, and negotiation on behalf of policyholders.
Texas-Focused Experience
Texas property losses have their own weather patterns, construction issues, insurance policies, deductibles, and claim challenges.
Our work includes residential and commercial losses involving hail, hurricanes, wind, roofing, water, fire, and other insured property damage.
Residential and Commercial Expertise
A homeowners claim and a commercial building claim require different approaches.
Our experience reviewing thousands of claims gives our team familiarity with losses ranging from residential roof damage to larger commercial property files involving multiple building components.
Independent Policyholder Representation
The insurance company’s adjuster represents the carrier’s interests.
A public adjuster represents the policyholder.
That distinction is fundamental.
Our responsibility is to document and present the insured’s covered property loss—not to reduce the insurer’s claim exposure.
No Upfront Fees
TX Public Adjusting offers a Free Claim Review with no upfront fees.
We can evaluate where your claim stands and discuss whether public adjusting assistance makes sense for your situation.
Areas We Serve Near Oyster Creek
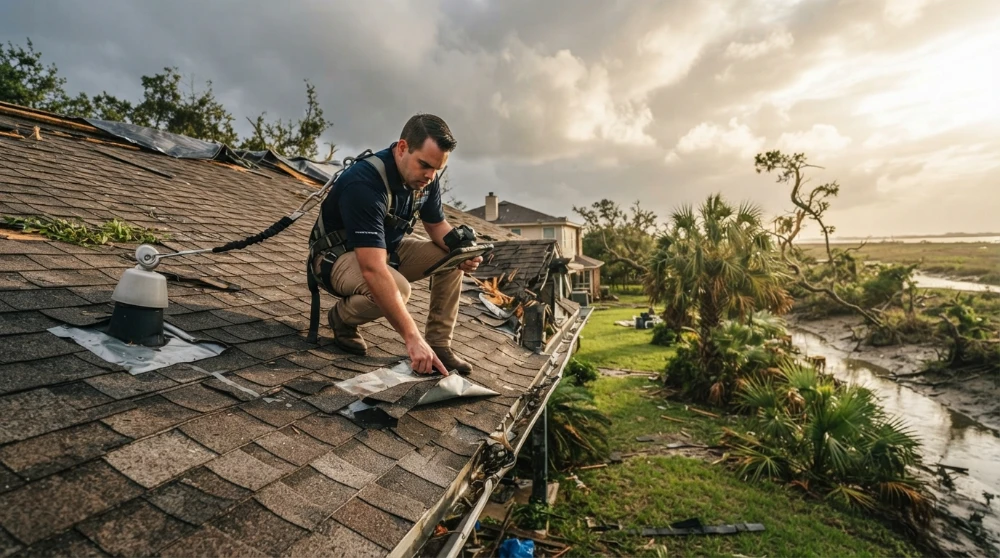
Our Oyster Creek public adjusting services extend throughout southern Brazoria County and the surrounding Brazosport communities, including:
- Freeport
- Lake Jackson
- Clute
- Surfside Beach
- Quintana
- Richwood
- Jones Creek
- Brazoria
- Angleton
- Other communities throughout Brazoria County
Lake Jackson planning documents identify Oyster Creek as part of the broader Brazosport area together with communities including Freeport, Clute, Jones Creek, Quintana, Richwood, Surfside Beach, and Brazoria.
Frequently Asked Questions About Public Adjusters in Oyster Creek
What does a public adjuster in Oyster Creek do?
If you’re unfamiliar with what a public adjuster does, the basic distinction is straightforward: a public adjuster represents the property owner during an insurance claim rather than representing the insurance company. That may include inspecting damage, reviewing the policy and carrier estimate, developing a detailed scope, organizing documentation, and negotiating property-damage issues with the insurance company.
For Oyster Creek homeowners and businesses, this can be particularly useful after hurricanes, tropical storms, wind events, water losses, fires, and complicated roof claims.
When should I hire a public adjuster after an Oyster Creek storm?
You can contact a public adjuster shortly after discovering the damage, but many Oyster Creek property owners also seek help after the carrier has inspected the property.
Common reasons include receiving a low estimate, discovering additional damage, experiencing delays, disagreeing with the scope, or simply facing a claim that has become difficult to manage.
Can a public adjuster help if my Oyster Creek claim is already underpaid?
Possibly. An initial payment does not automatically mean every covered item has been properly documented.
TX Public Adjusting can review the carrier’s scope, your property damage, and available claim documentation to identify legitimate differences that may warrant further presentation to the insurer.
Are hurricane claims common concerns in Oyster Creek?
Hurricanes and tropical systems are an important property risk because Oyster Creek is only a few miles from the Gulf Coast.
Potential losses include roof and exterior wind damage, wind-driven rain, interior water intrusion, damaged equipment, broken openings, and other storm-related impacts. Flooding may involve separate coverage considerations depending on the policy and cause of loss.
Can you help with flood damage in Oyster Creek?
We can review available policies and the circumstances surrounding the damage to determine how the claim should be approached.
Flood coverage can differ from standard homeowners or commercial property coverage, so identifying the source of water and applicable policy is especially important in a coastal Brazoria County community.
What if my insurance company says my roof only needs repairs?
Repair-versus-replacement disputes depend on the actual damage, roofing material, repairability, policy provisions, applicable conditions, and the complete scope of loss.
We inspect the roof and supporting exterior evidence, then compare our findings with the insurer’s estimate. If documented covered items are missing, they can be presented to the carrier.
Do you handle commercial claims around Oyster Creek and Freeport?
Yes. TX Public Adjusting handles residential and commercial property claims.
The Oyster Creek and Freeport area includes properties connected to the Brazosport industrial economy, so commercial losses may involve roofing systems, equipment, building envelopes, interiors, business personal property, and other specialized components.
How much does a public adjuster cost in Oyster Creek?
Public adjuster fees are typically contingency-based and are explained in the representation agreement.
TX Public Adjusting does not charge an upfront fee for the initial claim review. We explain the applicable fee structure before representation begins so the property owner can make an informed decision.
How long does an Oyster Creek property insurance claim take?
There is no single timeline. Property owners who have recently reported a loss may also want to understand how long an insurance adjuster has to contact you after a claim is filed. A relatively straightforward residential loss may move differently from a hurricane claim affecting multiple buildings or a commercial loss requiring extensive documentation.
Factors include the size of the loss, inspections, documentation needs, carrier response time, disagreements regarding scope, and whether supplemental information is required.
Why hire TX Public Adjusting instead of relying only on the insurance adjuster?
The two adjusters represent different parties. Our guide comparing a public adjuster vs. insurance adjuster for hail claims explains that distinction in more detail for storm-related property losses.
The insurance company’s adjuster works for the carrier. TX Public Adjusting works for the policyholder. Our role is to inspect, document, prepare, and negotiate the property claim from the insured’s perspective.
Get a Free Oyster Creek Insurance Claim Review
If your Oyster Creek home or business has suffered hurricane, wind, hail, water, fire, roof, or other covered property damage, you do not have to evaluate the insurance company’s estimate by yourself.
TX Public Adjusting can review the loss, identify potential claim issues, inspect the property, organize documentation, and represent you during the adjustment process.
TX Public Adjusting
Rise Public Adjusting LLC
Texas License #3356839
Licensed Texas Public Adjuster
Residential & Commercial Claims
Free Claim Review
No Upfront Fees
Contact TX Public Adjusting to discuss your Oyster Creek property damage claim and find out what options may be available.