

Property damage in Kenefick can turn into a difficult insurance claim quickly. This small Liberty County community sits in Southeast Texas, where severe thunderstorms, high winds, hail, tropical weather, heavy rainfall, and flooding can all affect homes, metal buildings, barns, roofs, and commercial property. Kenefick lies around the FM 1008 and FM 2797 corridors, roughly 41 miles northeast of Houston, and its location exposes property owners to both inland thunderstorm damage and Gulf-influenced weather systems.
If you need a public adjuster in Kenefick, TX Public Adjusting represents you—the policyholder—not the insurance company. We review property damage, inspect the loss, document the scope, analyze carrier estimates, and negotiate covered property claims on behalf of residential and commercial clients.
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839. Our team has experience reviewing thousands of property claims involving roofs, hail, wind, water, fire, storms, and commercial losses throughout Texas.
Free Claim Review | Licensed Texas Public Adjuster | Residential & Commercial Claims
If your Kenefick insurance claim was underpaid, denied, delayed, or simply does not appear to account for all of the damage, contact TX Public Adjusting for a free claim review with no upfront fees to get started.
Why Property Owners Hire a Public Adjuster in Kenefick
Kenefick is not a dense urban market filled with high-rise buildings and master-planned subdivisions. Property here is more spread out, and that changes the way losses can appear.
Homes and other structures along the FM 1008 and FM 2797 corridors may include conventional residential roofing, metal roofs, detached garages, workshops, storage structures, fencing, outbuildings, and other improvements that can all be affected by the same storm. The community developed historically around the railroad, agriculture, cattle, and the East Texas lumber industry, and the town remains distinctly more rural than nearby Houston-area suburbs.
For an insurance claim, that means an inspection should not automatically stop at the obvious roof damage.
A Kenefick public adjuster may review damage involving:
- Roofing shingles, metal roofing, flashing, vents, and penetrations
- Gutters, downspouts, fascia, and soffits
- Windows, screens, doors, and exterior finishes
- Detached garages, shops, and insured outbuildings
- Interior ceilings, drywall, insulation, and flooring
- Water intrusion after wind or roof damage
- HVAC components and exterior equipment
- Commercial roofing and building envelopes
- Covered contents and business property
- Debris removal and other policy-covered expenses
Insurance carriers investigate claims for their own companies. A public insurance adjuster in Kenefick works for the policyholder.
That difference becomes especially valuable when the insurance estimate appears smaller than the damage you can see—or when there may be hidden damage that requires a more detailed inspection and supporting documentation.
Kenefick Storm and Property Damage Risks
Kenefick’s location in central Liberty County creates a combination of weather risks that deserves more than generic Texas storm language.
Severe Thunderstorms, Wind, and Hail
Strong thunderstorms regularly develop across Southeast Texas. Kenefick has been specifically named in recent National Weather Service severe thunderstorm warnings for Liberty County.
On June 19, 2026, the National Weather Service warned of storms affecting Kenefick with potential 60 mph wind gusts and quarter-size hail, with expected damage to roofs, siding, trees, and vehicles. Another warning affecting Kenefick on July 22, 2026 identified the threat of 60 mph winds along with hail and damaging lightning.
For a property owner, these storms can produce:
- Hail impacts to shingles and metal surfaces
- Lifted or creased shingles from wind
- Damaged ridge caps
- Bent flashing and soft-metal components
- Damaged vents and roof accessories
- Siding and window damage
- Fallen limbs and debris impacts
- Water entering after wind creates an opening
A carrier inspection may identify one part of the loss without documenting the complete system affected by the storm.
Heavy Rain and Flood Exposure
Flooding also deserves particular attention in Kenefick. Liberty County’s 2025 Hazard Mitigation Plan includes a dedicated Kenefick floodplain map using FEMA flood-hazard data, showing that flood exposure is a meaningful local planning concern.
Insurance coverage for water is highly dependent on how the water entered the property. Flooding from rising surface water is generally handled differently from a covered plumbing loss or rain that enters through storm-created roof or exterior damage.
That distinction can become critical after a large storm.
For example, a property could potentially experience wind damage to a roof and subsequent interior water intrusion during the same event in which surrounding areas experience flooding. The cause of each portion of damage needs to be accurately investigated and documented rather than treated as one undifferentiated water loss.
Tropical Storm and Hurricane Effects
Kenefick is inland, but it is still within the broader Southeast Texas region that can experience tropical-system effects. Hurricanes and tropical storms moving inland from the Gulf can bring heavy rainfall, sustained winds, wind-driven rain, falling trees, power disruption, and water intrusion well beyond the immediate coastline.
That is why hurricane-related property inspections in Kenefick should consider much more than missing shingles. Moisture paths, attic conditions, ceilings, exterior components, windows, detached structures, and consequential damage can all matter to the claim.
For additional guidance, see the site’s Texas hurricane property damage guide, which is included in the TX Public Adjusting sitemap.
Common Insurance Claims in Kenefick
Hail Damage Claims
Hail does not need to break through a roof to cause insurable damage.
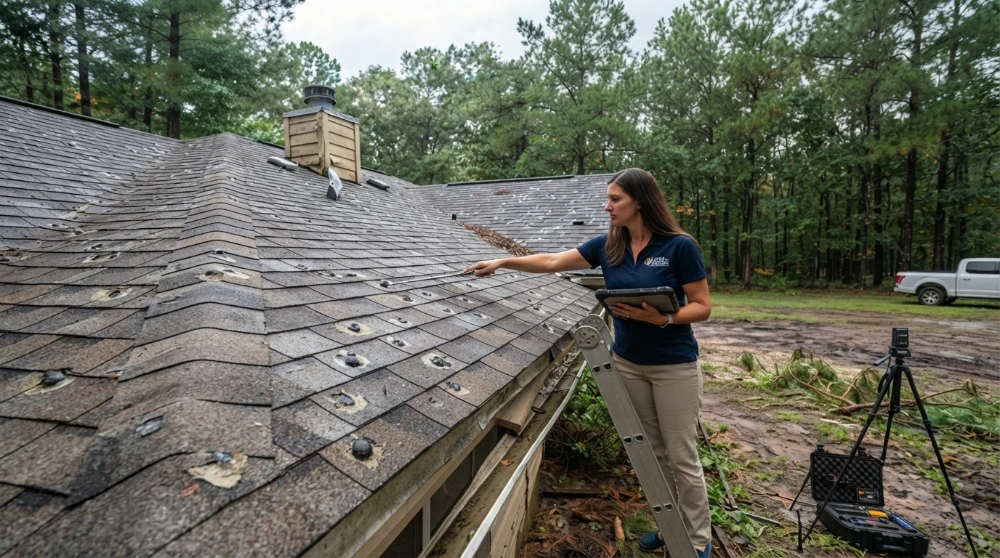
On asphalt roofing, an inspection may reveal fractured matting, displaced granules, bruising, or damage to roof accessories. Metal roofs and metal structures may show dents or functional damage depending on the storm and construction.
Hail can also affect:
- Gutters
- Roof vents
- Flashing
- HVAC fins
- Siding
- Window screens
- Fencing and exterior property
- Commercial roof systems
TX Public Adjusting reviews the complete property rather than assuming the carrier’s first estimate captured every affected component.
Property owners can also review our hail damage roof insurance claim guide and guide to documenting hail damage. Both are part of the site’s existing hail-claim content cluster.
Water Damage Claims
Kenefick water claims can involve plumbing failures, appliance leaks, roof leaks after storms, wind-driven rain, or water entering after damage to another building component.
The scope may extend beyond whatever is visibly wet.
Water can travel through:
- Attic insulation
- Wall cavities
- Ceiling assemblies
- Flooring systems
- Cabinetry
- Baseboards
- Electrical areas
- Adjacent rooms
The cause matters because different types of water damage can be treated differently under an insurance policy.
Our role is to document what happened, identify the affected areas, review policy considerations, and compare the insurer’s estimate to the actual scope of damage.
See our water damage public adjuster guide for additional claim information. The site’s strategy specifically identifies water damage claims as a core property-claim topic for TX Public Adjusting.
Fire and Smoke Damage Claims
A fire claim often extends well beyond the area visibly burned.
Depending on the loss, a Kenefick fire claim may involve:
- Structural damage
- Smoke contamination
- Soot
- Electrical components
- HVAC systems
- Personal property
- Contents cleaning or replacement
- Debris removal
- Temporary repairs
- Additional living expenses when covered
Smoke can move through rooms and mechanical systems that never came into direct contact with flames.
A detailed inventory and documentation process becomes especially important when many items are affected. TX Public Adjusting assists policyholders with the scope and presentation of these losses.
Learn more in our fire insurance adjuster guide.
Storm and Wind Damage Claims
High winds can create damage that is easy to overlook from ground level.
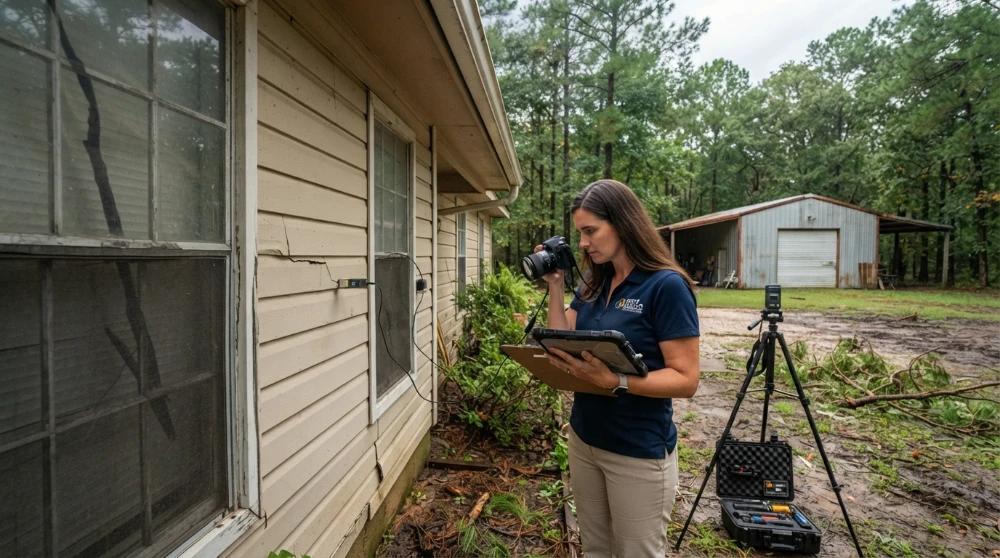
A storm inspection may identify lifted shingles, creases, missing materials, damaged ridge components, displaced flashing, impact from falling limbs, or openings that allow rain to enter.
For Kenefick properties with several buildings or structures on the same parcel, it is particularly important to determine which structures and improvements are insured and which were affected by the event.
Roof Damage Claims
Roof claims are among the most common property disputes because the difference between a localized repair and a larger covered scope can materially affect the value of a claim.
A carrier estimate may address a handful of shingles. The actual loss could involve additional roofing components, code-related considerations when applicable, gutters, vents, flashing, or interior water damage.
TX Public Adjusting compares the damage, measurements, estimate, repair scope, and available policy information before negotiating with the insurance carrier.
For more information, read our public adjuster for roof claims guide. The site’s own content strategy identifies roof claims as one of its highest-value claim categories.
Commercial Property Claims
Kenefick and the surrounding Liberty County area include more than residential property. Local businesses, agricultural-related operations, shops, warehouses, storage buildings, offices, and other commercial structures can experience significant storm and property losses.
Commercial claims can be particularly detailed because one event may affect:
- Large roof surfaces
- Inventory
- Business equipment
- Interior finishes
- Mechanical systems
- Exterior building components
- Multiple structures
- Business operations
TX Public Adjusting handles both residential and commercial property claims, giving owners a single team to coordinate inspection, documentation, estimate review, and insurance negotiations.
Why Kenefick Insurance Claims Become Underpaid
An insurance payment is based heavily on the scope used to calculate it. When items are missing from the scope, the payment may also be missing dollars needed for covered repairs.
Missed Damage
Damage may exist on portions of the roof or property that were not thoroughly inspected. Detached structures, exterior components, elevations, interior rooms, and concealed moisture can also be overlooked.
Scope Omissions
An estimate might acknowledge that a roof was damaged but omit associated components needed to perform the covered repair.
Depending on the property and loss, omitted items can include flashing, vents, gutters, interior finishes, insulation, siding, or other damaged materials.
Depreciation Issues
Property claim estimates often include depreciation. How depreciation is calculated and whether some portion may later be recoverable depends on the policy and the claim.
Policyholders should understand what was depreciated, why it was depreciated, and what steps may be required under their policy.
Low Repair Estimates
Carrier pricing, quantities, measurements, or repair assumptions may differ from the actual scope required to restore covered damage.
A public adjuster can review the insurer’s estimate line by line and identify areas that warrant additional documentation or discussion.
Documentation Problems
Photos taken after debris has been removed or temporary repairs are completed may not tell the complete story. Missing invoices, incomplete inventories, limited measurements, or poorly organized documentation can also make the claim harder to prove.
This is one reason early involvement can help on significant Kenefick property damage claims.
Already received an estimate or payment? You can still request a review. TX Public Adjusting can compare the carrier’s scope against the property damage and help determine whether important covered items may have been omitted.
Our Public Adjusting Process
1. Claim Review
We start by understanding what happened, what property was affected, what the insurance company has already done, and where the claim currently stands.
If available, we review the policy, carrier estimate, correspondence, photographs, previous inspections, and payment information.
2. Property Inspection
We inspect the damaged property and document relevant conditions.
For a Kenefick storm claim, that may include roof surfaces, exterior elevations, windows, gutters, interior rooms, detached insured structures, and other affected property.
3. Documentation and Scope Preparation
We organize photographs, measurements, damage information, estimates, inventories, reports, and other supporting material needed to present the claim.
Our objective is to build a clear record of the covered loss rather than rely only on a short carrier inspection.
4. Insurance Company Negotiation
TX Public Adjusting communicates and negotiates with the insurance company regarding the documented claim.
We address differences in scope, quantities, damage identification, and other claim issues that need to be supported and resolved.
5. Settlement and Claim Resolution
We work toward a settlement supported by the policy and documented covered damage.
Every claim is different, and no public adjuster can guarantee a particular settlement. Our role is to make sure the policyholder has professional representation throughout the property claim process.
Why Choose TX Public Adjusting for a Kenefick Claim?
Licensed Texas Representation
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839.
We Represent Policyholders
We do not work for your insurance carrier.
Our responsibility is to the residential or commercial policyholder who hires us.
Texas Property Claim Experience
Our experience includes thousands of claim reviews involving Texas homes and commercial properties.
That includes losses involving:
- Hail
- Wind
- Roof damage
- Water
- Fire and smoke
- Storms
- Hurricane-related damage
- Commercial buildings
Residential and Commercial Expertise
A storm can hit a house, shop, metal building, office, warehouse, or several insured structures at the same location.
Our claim approach is built around the actual property involved rather than a one-size-fits-all checklist.
Detailed Documentation
Property claims are won or lost on facts, coverage, and documentation.
We focus on identifying the full scope of covered damage and presenting it in a format that can be evaluated and negotiated with the insurance company.
Free Claim Review
If you are unsure whether the carrier’s estimate is reasonable, start with a free claim review. There are no upfront fees to get the review process started; any engagement terms and fees are explained in the public-adjuster agreement before representation begins.
Kenefick Is Different From a Typical Houston-Area City
Kenefick is an incorporated Liberty County town with a population of only about 615 at the 2020 census. Historically, the community grew after the Beaumont, Sour Lake and Western Railway was built through the area in the early 1900s, and lumber, cattle, and agriculture played major roles in its development.
That rural character matters for property claims.
Rather than referring to large named subdivisions that do not actually define Kenefick, local service is better described around the community’s real geographic corridors and surroundings:
- Properties around the FM 1008 corridor
- Homes and structures near FM 2797
- The central Kenefick area around the junction of those farm roads
- Rural properties extending toward Dayton
- Properties toward Dayton Lakes
- Areas in the direction of Liberty and Hardin
Kenefick’s proximity to the Trinity River corridor and mapped flood-hazard areas also makes water-source documentation particularly important after major rainfall events.
This gives a Kenefick property claim a very different local profile from a claim in Downtown Houston or a dense suburban subdivision.
Areas We Serve Near Kenefick
TX Public Adjusting assists property owners in Kenefick and throughout the surrounding Liberty County area, including communities such as:
- Dayton
- Dayton Lakes
- Liberty
- Hardin
- Tarkington Prairie
- Ames
- Plum Grove
- Moss Hill
- Other communities throughout Liberty County and Southeast Texas
Frequently Asked Questions About Public Adjusters in Kenefick
What does a public adjuster in Kenefick do?
A public adjuster represents the property owner during an insurance claim. That can include inspecting the loss, documenting damage, reviewing insurance estimates, preparing a detailed scope, communicating with the carrier, and negotiating covered claim issues.
TX Public Adjusting works for policyholders rather than insurance companies.
When should I hire a public adjuster after property damage in Kenefick?
Many property owners contact a public adjuster when the loss is substantial, the claim involves several parts of the property, they receive an unexpectedly low estimate, or the carrier denies some or all of the claim.
You can also seek help while a claim is already underway. See our guide explaining when it may be too late to hire a public adjuster.
Can a public adjuster help with an underpaid Kenefick roof claim?
Yes. An underpaid roof claim can be reviewed by comparing the insurance estimate with the documented damage, measurements, roofing components, photographs, and applicable policy provisions.
If important covered items were omitted, additional documentation may be submitted and the claim can potentially be negotiated further.
Can you help after a hail claim was denied?
A denied hail claim may still deserve review. We look at the stated reason for denial, date of loss, documented storm conditions, property condition, inspection findings, and available policy information.
TX Public Adjusting also maintains a dedicated guide on what to do if a hail claim was denied.
Does homeowners insurance cover flooding in Kenefick?
Standard property policies commonly distinguish rising floodwater from other causes of water damage. Coverage depends on the policy and the actual cause of loss.
Because Liberty County’s hazard planning specifically maps flood exposure around Kenefick, documenting whether water came from rising surface water, a damaged roof, plumbing, or another source can be particularly important.
Can you handle damage to barns, workshops, or detached buildings?
Potentially, yes, when the structure is insured and the damage involves a covered cause of loss.
Kenefick includes many more rural-style properties than a typical urban market, so a thorough claim review may need to account for insured detached garages, shops, storage structures, or other buildings in addition to the primary residence.
What if the insurance company has already paid my claim?
Receiving an initial payment does not automatically mean every issue in the claim has been resolved.
We can review the carrier estimate and compare it with the documented loss. If there are legitimate covered omissions or scope differences and the policy and claim status permit further action, additional documentation may be appropriate.
How much does a public adjuster cost in Kenefick?
Public adjuster compensation is generally established in the written representation agreement and is subject to applicable Texas requirements.
TX Public Adjusting offers a free initial claim review, so you can first discuss your loss and understand whether professional claim assistance makes sense before deciding how to proceed.
How long does a Kenefick property insurance claim take?
There is no single timeline. A straightforward claim with clear documentation can move differently from a large fire loss, commercial claim, disputed roof claim, or loss involving several structures.
Claim duration can depend on inspections, documentation, carrier response times, disagreements over scope, required reports, and the complexity of the policy and damage.
Why should I hire TX Public Adjusting instead of relying only on the insurance company’s adjuster?
The insurance company’s adjuster investigates the claim for the carrier. A public adjuster is retained by the policyholder.
TX Public Adjusting, operated by Rise Public Adjusting LLC under Texas License #3356839, provides independent policyholder representation with experience in residential and commercial Texas property claims. Our job is to document and present your covered loss—not protect the insurance company’s financial interests.
Get a Free Kenefick Insurance Claim Review
If your Kenefick home, business, roof, shop, or other insured property has been damaged, you do not have to evaluate the insurance company’s estimate by yourself.
TX Public Adjusting can review claims involving hail, wind, roofs, water, fire, severe thunderstorms, hurricane-related damage, and commercial property losses throughout Kenefick and Liberty County.
If the carrier missed damage, wrote an incomplete scope, issued a low estimate, denied the claim, or you simply want another professional review before accepting the outcome, contact us.
TX Public Adjusting
Rise Public Adjusting LLC
Texas License #3356839
Free Claim Review
No upfront fees to begin your review
Residential & Commercial Property Claims
Contact TX Public Adjusting today to discuss your Kenefick property damage claim.