

Property damage in Frydek can turn into a complicated insurance claim quickly, especially when a severe thunderstorm damages a roof, wind drives rain into a building, or rising water affects property near the Brazos River. A Public Adjuster in Frydek, TX can help property owners document the full extent of a covered loss, review the insurance company’s estimate, identify missing damage, and present a detailed claim on the policyholder’s behalf.
TX Public Adjusting provides residential and commercial insurance claim assistance throughout Frydek and Austin County. We are Rise Public Adjusting LLC, Texas License #3356839, and we represent policyholders—not insurance companies.
Frydek is a small, unincorporated community in southeastern Austin County along FM 1458 and the west side of the Brazos River, only a few miles from Sealy and San Felipe. Its rural properties, agricultural buildings, homes, churches, and small businesses face a different mix of exposures than properties in central Houston or Dallas.
Need help with an existing, denied, delayed, or underpaid property claim in Frydek? Contact TX Public Adjusting for a Free Claim Review. There are no upfront fees.
Why Property Owners Hire a Public Adjuster in Frydek
An insurance company’s adjuster investigates a loss for the carrier. A public adjuster has a different role: representing the policyholder’s interests during the property insurance claim. Understanding the difference between the two roles matters, especially on storm losses. Our guide comparing a public adjuster vs. insurance adjuster for hail claims explains who each adjuster represents and how their responsibilities differ.
That distinction can matter after significant damage.
Many Frydek properties sit in a rural environment where a loss may involve more than a single roof surface. A storm can affect shingles or metal roofing, detached structures, fencing, exterior finishes, gutters, windows, mechanical equipment, interior ceilings, and contents. Farm and ranch properties may present additional questions involving barns, workshops, storage structures, equipment, and other insured improvements.
A public insurance adjuster in Frydek can help when:
- The carrier’s estimate appears too low.
- Damage was left out of the original scope.
- The insurer approved a repair when the actual damage may require broader work.
- Hail or wind damage is disputed.
- Water intrusion has affected multiple rooms or building components.
- The claim involves a large residential or commercial loss.
- You have received a partial denial or coverage limitation you do not understand.
- Contractors have identified damage that does not appear on the insurance estimate.
- The documentation needed to support the claim has become overwhelming.
TX Public Adjusting reviews the damage, available policy information, carrier correspondence, estimates, photographs, and other claim documentation to determine where additional investigation may be warranted.
Property Damage Risks Specific to Frydek and Austin County
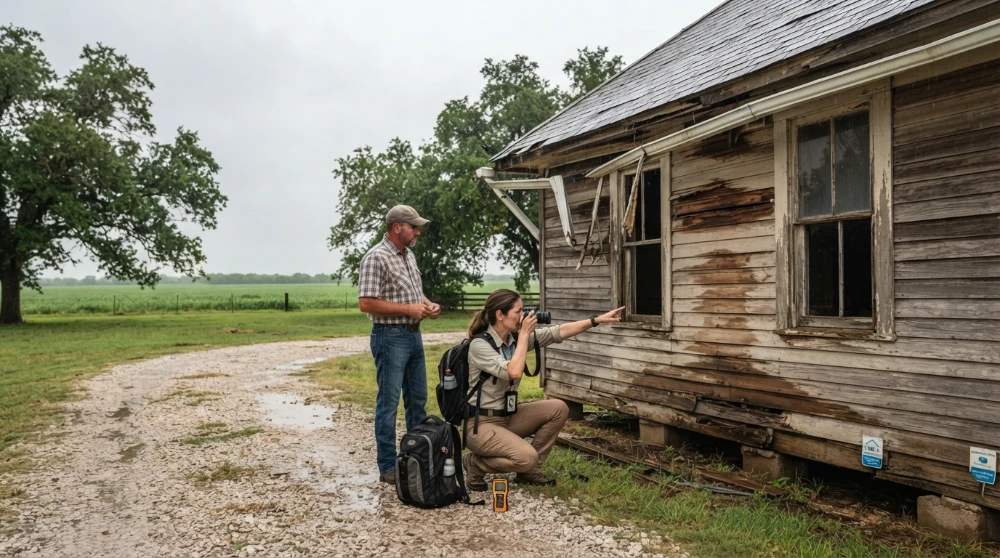
Frydek’s location is one of the most important differences between this page and a generic Texas property-claim page. The community sits on the west bank of the Brazos River in southeastern Austin County. The surrounding landscape includes relatively level agricultural land, rural roads, creeks, and properties extending toward Sealy, San Felipe, and Wallis.
Severe Thunderstorms, Wind, and Hail
Southeast Texas thunderstorms can produce damaging wind, lightning, hail, and heavy rainfall. National Weather Service products for the Houston/Galveston forecast area regularly include Austin County in strong-thunderstorm conditions; one July 2026 statement, for example, identified Austin County among areas affected by a storm capable of producing wind gusts around 40 mph.
For Frydek property owners, storm damage can appear as:
- Lifted, creased, or missing shingles
- Hail impacts to asphalt roofing
- Dents to metal roofs and soft-metal components
- Damaged gutters, vents, flashing, and roof accessories
- Wind-driven rain entering through compromised roofing
- Broken limbs or fallen trees damaging structures
- Window, siding, and exterior damage
- Damage to barns, garages, sheds, and other structures
Storm claims sometimes become underpaid because the most obvious roof damage receives attention while collateral exterior or interior damage is omitted.
Brazos River and Heavy-Rain Concerns
Frydek’s proximity to the Brazos makes water-related risk locally significant. FEMA flood-hazard information for Austin County is part of the Lower Brazos Watershed mapping and study framework, including nearby Sealy and San Felipe.
Not every type of water damage is covered by the same policy. Rising surface water and flooding are generally treated differently from sudden interior water losses, wind-driven rain, or water entering through storm-created openings. Coverage depends on the policy and the cause of loss.
That makes the source and sequence of water intrusion particularly important. A public adjuster can document the property damage and review the applicable insurance policy, but should not simply assume that every water loss falls under the same coverage.
Tropical Systems and Inland Wind Damage
Frydek is inland from the Texas Gulf Coast, but Gulf tropical systems can carry significant rain and wind well beyond coastal counties. A storm does not need to make landfall in Frydek to create an insurance loss there.
For Austin County properties, tropical weather can contribute to roof damage, fallen trees, wind-driven rain, prolonged power interruptions, and moisture intrusion. When several causes are involved, careful documentation becomes even more important.
Freeze and Plumbing Losses
Winter freezes can also create expensive claims. Frozen or ruptured plumbing may damage drywall, flooring, cabinetry, insulation, personal property, and electrical components. Rural homes or structures that are vacant for portions of the year can present additional claim questions surrounding timing, mitigation, and the cause of the loss.
A Frydek Claim Is Not the Same as a Big-City Claim
Frydek does not have conventional named urban neighborhoods in the way Houston, Dallas, or Austin do. Local geography is better understood through FM 1458, Grotto Road, the Brazos River side of the community, rural acreage, and the nearby communities of Sealy, San Felipe, and Wallis.
That rural character matters when documenting losses.
Properties may include detached workshops, barns, agricultural-use structures, long fencing runs, metal roofing, older construction, acreage improvements, and multiple buildings under one ownership. Austin County itself has a substantial agricultural history and economy, with farming and ranching forming an important part of the county’s land use.
Frydek also has a distinct Czech heritage. The community was established around 1895 by Czech settlers, and local landmarks such as St. Mary’s Catholic Church, its grotto, and the historic Frydek Catholic Cemetery remain visible reminders of that history. The cemetery dates to the nineteenth century and is recognized by the Texas Historical Commission.
Nearby, San Felipe de Austin State Historic Site and Stephen F. Austin State Park connect the area to some of the earliest Anglo-American settlement history in Texas.
Common Insurance Claims in Frydek
Hail Damage Claims
Hail damage is often harder to evaluate than homeowners expect. A roof may still be watertight immediately after a storm while shingles, flashing, vents, gutters, or metal surfaces show functional or impact damage. Property owners dealing with a hail damage roof insurance claim should document both the roof and collateral damage before repairs begin.
TX Public Adjusting can evaluate the insurance estimate against documented property conditions and determine whether relevant storm damage may have been omitted.
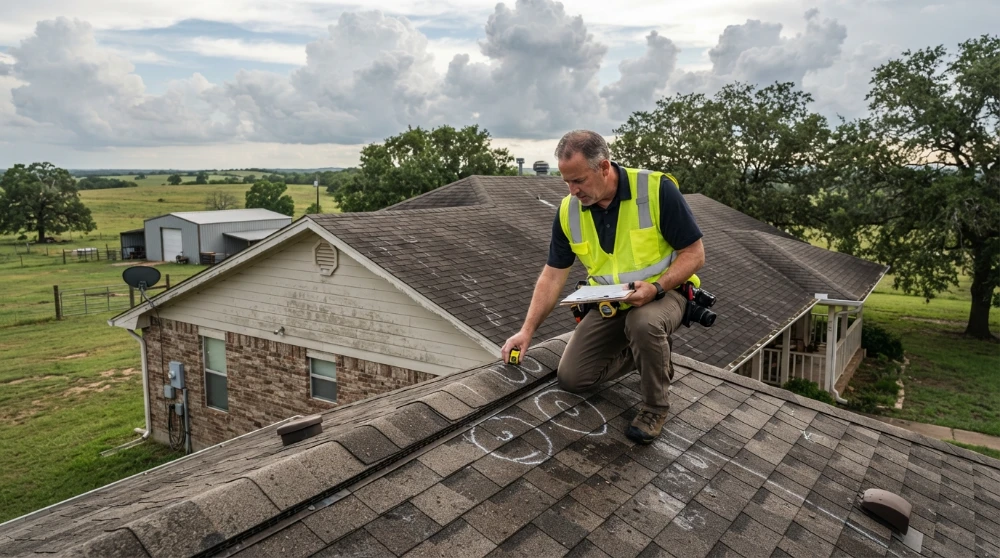
For hail claims, documentation may include roof slopes, test areas, photographs, measurements, collateral damage, soft-metal impacts, interior staining, and storm-related damage to detached structures. Our guide explains how to document hail damage for an insurance claim before important evidence disappears.
Water Damage Claims
Water claims can involve much more than replacing wet drywall. A water damage public adjuster can review whether the carrier’s scope accounts for the full extent of covered damage documented throughout the property.
A covered plumbing or storm-related water loss may affect insulation, flooring, baseboards, cabinetry, electrical components, contents, and concealed building materials. Mitigation invoices can create another layer of disagreement if the carrier disputes drying equipment, demolition, labor, or the amount of material affected.
We review the scope and supporting documentation to help present the complete covered loss.
Fire and Smoke Damage Claims
A fire claim can extend far beyond visibly burned material. Smoke and soot may affect rooms that were not directly touched by flames. Contents, HVAC systems, insulation, finishes, electrical systems, odor remediation, demolition, debris removal, and temporary living expenses may all need to be evaluated depending on the policy and loss.
TX Public Adjusting has experience reviewing both residential and commercial fire claims and organizing documentation across the different parts of the loss. Property owners facing a major fire loss can also learn more about how a fire insurance adjuster can assist with documenting and presenting the claim.
Storm and Wind Damage Claims
Strong winds can damage roofing without removing the entire roof. Shingles can lift or crease, flashing can separate, tree limbs can strike structures, and wind-driven rain may enter through damaged areas.
On rural Frydek properties, the inspection may also need to extend beyond the primary residence to insured garages, workshops, barns, sheds, or other structures.
Roof Damage Claims
Roof claims frequently become disputed over questions such as repair versus replacement, the quantity of damaged material, matching, labor, flashing, ventilation, decking, code-related work, or whether interior water staining resulted from the same event. A public adjuster for a roof claim can compare the carrier’s scope against documented property conditions and identify items that may require additional review.
A public adjuster does not determine coverage by assumption. We review the policy and documented facts of the loss, then build the claim around what can be supported.
Commercial Property Claims
Commercial claims often require a broader scope than residential losses. TX Public Adjusting provides commercial public adjuster services for property owners dealing with significant insured losses involving buildings, interiors, equipment, roofing systems, and multiple structures.
TX Public Adjusting assists business and property owners with buildings such as offices, retail properties, warehouses, churches, multifamily properties, restaurants, and eligible farm or ranch structures. The site’s existing commercial claim hub and specialized commercial pages can support these claims.
Commercial losses may involve:
- Roofing systems
- Interior finishes
- Equipment
- Business contents
- Mechanical systems
- Tenant areas
- Exterior structures
- Mitigation expenses
- Code-related repair considerations
- Multiple buildings or roof sections
Why Insurance Claims Become Underpaid
An insurance settlement can fall short without the property owner immediately realizing why.
Missed Damage
Initial inspections can be brief. Damage to secondary roof slopes, flashing, gutters, elevations, detached structures, or interior areas may not appear in the first estimate.
Scope Omissions
A carrier may recognize that damage exists but omit some of the work required to restore the property. Those omissions can involve labor, removal, access, disposal, preparation, finishing, or related components.
Depreciation Issues
Depreciation can significantly affect the initial payment on replacement-cost claims. Policyholders may also need to understand what depreciation is recoverable, what documentation is required, and what deadlines apply.
Low Estimates
Two estimates can differ because the parties are using different measurements, quantities, repair methods, labor assumptions, or scopes—not simply because one person selected a different price.
We look at what work is actually necessary and how the documented loss compares with the carrier’s estimate.
Documentation Problems
A valid claim still needs evidence.
Photographs taken too late, discarded damaged materials, incomplete mitigation records, poor inventories, missing contractor estimates, or unclear documentation of the cause of loss can create unnecessary disputes.
This is one reason engaging a Frydek public adjuster earlier in a significant claim can be valuable.
Our Public Adjusting Process
1. Claim Review
We begin by reviewing the loss and current status of the claim. That can include the insurance policy, carrier estimate, payment documents, denial or reservation letters, contractor estimates, photographs, mitigation records, and prior correspondence.
2. Property Inspection
We inspect the reported damage and look for related conditions that may not have been included in the initial carrier scope.
For a Frydek storm claim, that can mean examining more than the main building—particularly when the insured property includes detached structures or multiple roof types.
3. Documentation and Scope Development
We organize photographs, measurements, estimates, inventories, and supporting information so the claim accurately communicates the extent of the loss.
Our experience includes the review of thousands of residential and commercial property claims and the documentation issues that commonly create disagreements.
4. Insurance Company Communication and Negotiation
TX Public Adjusting communicates with the carrier regarding the documented claim and addresses disputed or omitted items through the claims process.
The goal is not to inflate a claim. It is to support the full amount owed under the policy based on documented covered damage.
5. Settlement and Claim Resolution
We continue working through the claim toward an appropriate resolution based on the policy, loss documentation, inspections, estimates, and carrier response.
Already received an estimate or payment that looks too low? Request a Free Claim Review from TX Public Adjusting before assuming the carrier’s first scope is the final word.
Why Choose TX Public Adjusting for a Frydek Property Claim?
Licensed Texas Public Adjuster
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839.
We Represent Policyholders
We work for the property owner—not the insurance company.
That means our focus is on documenting and presenting the policyholder’s claim rather than adjusting the loss for the carrier.
Texas-Focused Claim Experience
Texas property claims require familiarity with hail, wind, tropical storms, freeze losses, water damage, fire losses, and commercial-property damage.
Our work includes both residential and commercial claims throughout Texas.
Residential and Commercial Expertise
A homeowner dealing with a roof leak needs a different claim strategy than an owner managing damage across a commercial building, church, warehouse, or rural property.
We tailor the documentation to the property and loss rather than forcing every claim into the same template.
Detailed Scope Review
We compare carrier estimates against observed property damage and available documentation. Missing quantities, overlooked building components, incomplete repair sequences, or excluded areas can materially affect the claim.
Free Claim Review and No Upfront Fees
You can have TX Public Adjusting review your situation before deciding how to proceed. There are no upfront fees for the claim review.
Areas We Serve Near Frydek
Our Frydek service area extends throughout southeastern Austin County and surrounding communities. Property owners west of Frydek can learn more about our Public Adjuster Sealy services, while properties north toward the Brazos River corridor are also covered through our Public Adjuster San Felipe service area. Southeast of Frydek, we also provide insurance claim assistance through our Public Adjuster Wallis page.
We also assist residential, agricultural, and commercial property owners throughout Austin County and surrounding communities.
Frequently Asked Questions About Public Adjusters in Frydek
What does a public adjuster in Frydek do?
A public adjuster represents the policyholder during a property insurance claim. We inspect and document damage, review estimates and policy information, identify potential scope omissions, prepare supporting claim documentation, and communicate with the insurance carrier.
TX Public Adjusting represents homeowners and commercial property owners. We do not work for the insurance company.
When should I hire a public adjuster after property damage in Frydek?
Consider contacting a public adjuster when the damage is significant, the claim involves several parts of the property, the carrier’s estimate appears incomplete, or the claim has already become delayed, disputed, denied, or underpaid.
You do not necessarily have to wait for a disagreement. Getting help early can improve documentation before repairs or cleanup make the original damage harder to establish.
Can you help if my insurance company already paid my Frydek claim?
Potentially. Receiving a payment does not automatically mean every covered item was included in the carrier’s scope.
We can review the estimate, payment information, documentation, and current condition of the property to determine whether there are apparent omissions or issues worth pursuing. Timing and policy provisions can matter, so an older claim should be reviewed promptly.
Can a Frydek public adjuster help with hail and roof claims?
Yes. Roof and hail claims are a major part of Texas property adjusting. We can review damage to shingles, metal roofing, flashing, gutters, vents, exterior surfaces, and related interior areas.
The key question is not simply whether hail fell nearby. The claim needs property-specific evidence connecting documented damage to the reported event.
Does homeowners insurance cover Brazos River flooding in Frydek?
Standard property policies generally treat external flooding differently from many other types of water damage, and flood coverage commonly requires separate insurance. Because Frydek lies beside the Brazos River, property owners should be especially careful not to assume that every form of water intrusion is covered under the same policy. FEMA specifically includes Austin County in Lower Brazos watershed flood-hazard mapping.
If water entered because wind damaged a covered portion of the building, a pipe ruptured, or another event occurred, the coverage analysis may be different. The actual policy and cause of loss need to be reviewed.
Do you handle rural, farm, and ranch property claims around Frydek?
Yes, when the damaged property and structures are insured under applicable coverage. Rural losses can involve residences, barns, workshops, storage buildings, metal roofing, fencing, equipment-related structures, and multiple buildings.
These claims benefit from an inspection that accounts for the entire insured property rather than focusing only on the main residence.
Why is my insurance company’s roof estimate lower than my contractor’s?
The difference may come from measurements, quantities, labor assumptions, missing components, repair methodology, or the overall scope. Comparing only the total dollar amounts rarely reveals the real dispute.
We review the line items and property conditions to determine where the estimates differ and what documentation can support the work claimed.
Can you help with an underpaid commercial property claim in Frydek?
Yes. TX Public Adjusting handles residential and commercial claims. Commercial claims may involve roofing, interiors, equipment, tenant spaces, building systems, mitigation, and multiple structures.
They can also generate more extensive documentation than a typical residential claim, so establishing an organized scope early can make a substantial difference in how the claim is presented.
How much does a public adjuster in Frydek charge?
Public-adjusting compensation depends on the engagement and applicable Texas requirements. Before you hire TX Public Adjusting, the fee arrangement should be clearly explained in the written agreement so you understand how compensation works.
We offer a Free Claim Review with no upfront fees, allowing you to discuss the situation before making a decision.
Is it too late to hire a public adjuster after my claim has been open for months?
Not necessarily. Public adjusters are frequently hired after a policyholder receives an estimate, payment, partial denial, or disputed scope.
However, insurance policies contain duties, conditions, and deadlines, and the passage of time can make documentation more difficult. If you believe a Frydek property claim was underpaid or mishandled, it is better to have it reviewed sooner rather than later. Read our guide explaining when it may be too late to hire a public adjuster for additional information about timing.
Get Insurance Claim Help in Frydek, TX
Property owners in Frydek should not have to guess whether an insurance estimate includes everything needed to address a covered loss.
If your home, rural property, commercial building, church, rental property, or other insured structure has suffered hail, wind, roof, water, fire, or storm damage, TX Public Adjusting can review the claim and help you understand the next step.
TX Public Adjusting
Rise Public Adjusting LLC
Texas License #3356839
Free Claim Review. No upfront fees. Residential and commercial property claims.
Contact TX Public Adjusting today to request a Free Claim Review and have your Frydek insurance claim evaluated by a licensed Texas public adjuster.