Property damage in Bastrop can become complicated fast. A severe thunderstorm can damage shingles and siding across one part of the city while heavy rain causes interior water damage closer to the Colorado River. In the wooded communities surrounding the Lost Pines, fire and smoke can create a completely different type of insurance claim. When the carrier’s estimate does not reflect the full extent of the loss, a public adjuster in Bastrop can help document the damage and represent the policyholder throughout the claim.
As a licensed Texas public adjuster, TX Public Adjusting provides residential and commercial insurance claim assistance throughout Bastrop and Bastrop County. We review policies, inspect damaged property, prepare detailed claim documentation, identify missing items, and negotiate with the insurance company on behalf of the property owner.
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839. We work for policyholders—not insurance companies.
Request a Free Claim Review. There are no upfront fees.
Why Property Owners Hire a Public Adjuster in Bastrop
An insurance claim is more than a repair estimate. The final outcome may depend on how the damage is documented, how the policy is interpreted, which materials are included in the repair scope, and whether related damage is properly connected to the covered event.
A carrier may send an adjuster to inspect the property, but that adjuster represents the insurance company. A Bastrop public adjuster represents the homeowner, landlord, business owner, commercial property owner, or other policyholder.
Property owners often contact us when:
- The insurance estimate appears too low.
- The adjuster overlooked sections of the roof or exterior.
- Interior water damage was excluded from the scope.
- The carrier applied depreciation the owner does not understand.
- A contractor’s estimate is significantly higher than the carrier’s estimate.
- The claim has stalled with repeated requests for more information.
- The insurance company has denied part or all of the claim.
- A supplemental claim requires stronger documentation.
- A large residential or commercial loss is becoming difficult to manage.
Bastrop is not simply another Austin-area suburb. The community includes historic downtown buildings, established subdivisions, newer master-planned developments, wooded acreage, river-adjacent property, and commercial growth along State Highway 71. Each property type creates different inspection, valuation, access, code, and repair-scope issues.
Property Damage Risks in Bastrop and Bastrop County
Bastrop is the county seat of Bastrop County and sits along the Colorado River in the Lost Pines region of Central Texas. The area’s combination of wooded terrain, severe thunderstorms, extreme heat, river drainage, and continued development creates a varied property-risk profile.
Bastrop County’s hazard planning materials identify risks that include hail, drought, extreme heat, winter storms, flooding, severe thunderstorms, tornadoes, and wildfire.
Hail and Severe Thunderstorm Damage
Central Texas thunderstorms may bring hail, strong straight-line winds, lightning, and wind-driven rain. Bastrop County defines severe thunderstorms as storms capable of producing significant hail, winds of at least 58 miles per hour, or tornadoes. Property owners who are preparing a hail damage roof insurance claim should document the roof, exterior elevations, soft metals, and any resulting interior leaks before permanent repairs begin.
Hail damage is not always obvious from ground level. A roof may continue to shed water for a period of time even when shingles, metal components, vents, gutters, flashing, and soft metals have sustained functional damage.
A Bastrop hail claim may involve:
- Bruised or fractured asphalt shingles
- Dented metal roofing
- Damaged ridge caps and roof vents
- Dented gutters and downspouts
- Cracked skylights
- Damaged siding, fencing, screens, and exterior finishes
- Interior leaks following roof or flashing damage
- Damage to rooftop commercial equipment
Before damaged materials are removed, learn how to document hail damage for an insurance claim with photographs, dates, repair records, and supporting property details. A complete claim should consider more than the most visible roof impacts. We inspect related exterior components and evaluate whether the carrier’s scope provides a practical path to restoring the damaged property.
Wind and Roof Damage
Strong winds can lift shingles, loosen flashing, damage ridge materials, break tree limbs, and create openings that allow rain into the structure.
Wind claims become disputed when the carrier attributes the damage to age, installation defects, wear and tear, or prior deterioration. Clear photographs, storm information, repair history, and a detailed inspection can help separate storm-created damage from unrelated maintenance conditions.
For properties surrounded by mature pines and oaks, wind can also cause tree-impact damage to:
- Roof decking
- Rafters and trusses
- Gutters
- Fences
- Detached garages
- Sheds
- Electrical service equipment
- Exterior HVAC components
Flooding and Water Intrusion
The Colorado River is central to Bastrop’s geography and identity. Downtown Bastrop sits near the river, while parks and trails provide public access along its banks.
Property owners should understand that flood damage and water damage are not always treated the same under an insurance policy. Rising surface water may be excluded from a standard property policy unless separate flood coverage applies. Rain entering through a storm-created roof opening, a burst pipe, an appliance leak, or a failed plumbing line may be evaluated under different policy provisions. The documentation and communication process can also affect the outcome. Property owners who are dealing with an insurance adjuster after water damage should preserve photographs, mitigation records, invoices, and evidence of the original water source.
Water claims in Bastrop may involve:
- Roof leaks after wind or hail
- Wind-driven rain
- Burst or leaking plumbing
- Water-heater failures
- Appliance supply-line leaks
- Overflow damage
- Ceiling and drywall damage
- Flooring and cabinet damage
- Hidden moisture in walls
- Mold-related concerns
- Commercial inventory or equipment damage
The source and sequence of the water are critical. A public adjuster documents how the loss occurred, which building materials were affected, and what work may be required to return the property to its pre-loss condition.
Wildfire, Fire, and Smoke Damage
Wildfire is a defining property risk in the Lost Pines region. Bastrop County’s wooded landscape includes loblolly pine forests that are unusual for Central Texas, and the area has a well-documented history of destructive wildfire. Local hazard planning materials recognize that wildfire can cause severe property damage and alter entire communities.
Homes near Bastrop State Park, Tahitian Village, Pine Forest, Circle D-KC Estates, and other wooded areas may face concerns involving vegetation, access, falling trees, ember exposure, smoke, and heat. A fire damage insurance claim may include structural repairs, smoke remediation, damaged contents, debris removal, temporary housing, and water damage caused during firefighting.
A fire insurance claim can include far more than burned structural materials. The scope may also need to address:
- Smoke and soot contamination
- Odor removal
- Personal-property inventory
- Debris removal
- Electrical damage
- HVAC contamination
- Water damage from firefighting
- Temporary repairs
- Additional living expenses
- Business interruption
- Demolition and reconstruction
- Code-related repair requirements
Smoke can travel through wall cavities, ductwork, insulation, attics, and enclosed contents. Cleaning only the visible surfaces may not fully address the damage.
Winter Freeze and Plumbing Claims
Although Bastrop is known for hot summers, Central Texas properties can still experience freeze losses. Extended cold weather may rupture pipes in attics, exterior walls, garages, vacant buildings, or commercial spaces.
Freeze claims can involve extensive water migration before the leak is discovered. The visible ceiling stain may represent only a small portion of the affected area.
Extreme Heat and Secondary Property Issues
Extreme heat and drought can contribute to stressed roofing materials, foundation movement, dry vegetation, HVAC strain, and increased fire conditions. Not every heat-related condition is covered, but these factors can complicate a claim when a sudden storm event affects an already stressed building.
The distinction between covered storm damage and long-term deterioration must be supported by careful documentation rather than assumption.
Common Insurance Claims We Handle in Bastrop
Hail Damage Claims
We document hail impacts to roofing systems, vents, flashing, gutters, siding, windows, fencing, and related components. We also review whether the carrier’s estimate accounts for the full repair area and matching concerns.
Water Damage Claims
Water can move through insulation, wall cavities, subfloors, cabinets, and adjacent rooms. We document the source, affected materials, moisture-related demolition, and necessary restoration work.
Fire and Smoke Damage Claims
Fire claims may require a building estimate, contents inventory, smoke-remediation scope, debris-removal analysis, and tracking of additional living or business expenses. A public fire insurance adjuster can coordinate these separate parts of the loss and present them as one documented property claim.
Storm and Wind Damage Claims
We inspect roofing, exterior elevations, detached structures, tree impacts, openings, and interior damage caused by wind-driven rain.
Roof Damage Claims
A public adjuster for a roof claim can review whether the carrier included all damaged slopes, underlayment, flashing, ventilation, access, labor, and resulting interior damage.
Commercial Property Claims
A commercial public adjuster can help document losses involving operations, tenants, equipment, inventory, common areas, roofing systems, and business income. We assist with claims involving retail buildings, offices, restaurants, warehouses, churches, multifamily properties, hospitality properties, and other insured commercial locations.
Local Claim Concerns Across Bastrop Neighborhoods
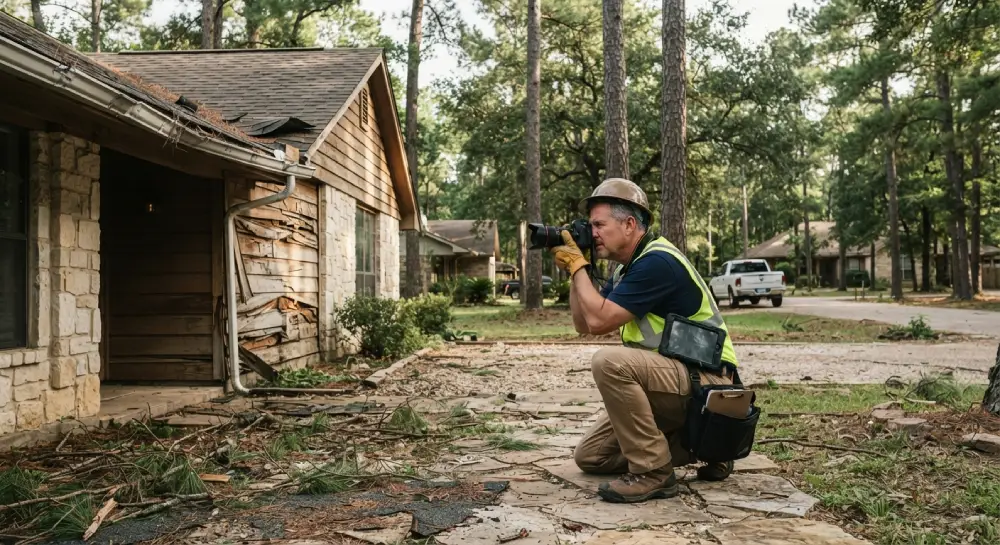
Bastrop’s neighborhoods differ significantly in age, density, vegetation, terrain, and construction.
Historic Downtown Bastrop
Historic Downtown Bastrop contains older commercial buildings and residences close to the Colorado River. The area is known for its historic streetscape, restaurants, shops, and cultural properties. The Bastrop County Museum and Visitor Center is located on Main Street along the historic El Camino Real de los Tejas corridor.
Claims involving older buildings may require added attention to:
- Original or uncommon materials
- Plaster and historic finishes
- Roof access
- Shared walls
- Electrical and mechanical systems
- Code-related upgrades
- Business-income disruption
- Water migration between spaces
Tahitian Village and Pine Forest
Tahitian Village is a recognizable river-adjacent community, while Pine Forest sits nearby among Bastrop County’s loblolly pines. Pine Forest is adjacent to Tahitian Village and the Colorado River environment.
Properties in these wooded areas may experience tree impacts, wind damage, wildfire exposure, smoke damage, drainage concerns, and difficult roof access on sloped lots.
Hunters Crossing
Hunters Crossing is an established Bastrop subdivision with a city-recognized public improvement district and neighborhood park.
Common claims in established subdivisions may involve hail-damaged composition roofs, fencing, gutters, garage doors, interior leaks, and disputes over whether a repair or broader replacement is required.
The Colony
The Colony is one of the larger master-planned communities in the Bastrop area. Newer construction does not eliminate claim problems. Storm damage may still affect roofs, exterior finishes, fencing, windows, and drainage systems.
New-construction claims can also become complicated when an insurance company suggests that observed damage is related to workmanship rather than a covered weather event.
Circle D-KC Estates
Circle D-KC Estates is located northeast of Bastrop near State Highway 21 and includes wooded, acreage-style residential property.
Larger lots and tree coverage can create claims involving detached structures, long fences, outbuildings, private access roads, fallen trees, smoke exposure, and extensive exterior debris.
ColoVista, Riverside, and Pecan Park
Areas near the Colorado River or lower-lying drainage corridors require careful analysis of how water entered the property. The cause may determine whether the damage falls under a property policy, flood policy, or another form of coverage.
Owners should avoid assuming that every water loss is excluded as flooding—or that every water loss is automatically covered. The specific facts and policy wording matter.
Why Bastrop Insurance Claims Become Underpaid
Missed or Unseen Damage
A fast inspection may overlook rear roof slopes, flashing, soft-metal impacts, interior moisture, detached structures, or damage hidden beneath finishes.
Scope Omissions
The carrier may acknowledge damage but leave out labor, access, removal, disposal, underlayment, flashing, painting, matching, temporary protection, or related interior work.
Low Repair Pricing
Pricing can vary based on labor conditions, material availability, roof height, steepness, access, and the complexity of the building. A generic estimate may not reflect the actual requirements of the Bastrop property.
Depreciation Issues
Property owners may not understand what was depreciated, whether depreciation can be recovered, or which documents must be submitted after repairs.
Cause-of-Loss Disputes
The carrier may argue that the damage came from age, wear, maintenance, construction defects, prior damage, or an excluded source. When the carrier says the roof damage resulted from age, wear, or maintenance rather than the storm, review what to do if your hail claim was denied before assuming the decision cannot be challenged.
Weak Documentation
A few photographs and a contractor invoice may not explain the entire loss. Strong claims may require measurements, labeled photographs, a room-by-room scope, material identification, contents records, invoices, weather information, and a clear timeline. Discarding materials too early, failing to photograph hidden damage, and relying only on the carrier’s estimate are among the common property insurance claim mistakes that can make a loss harder to prove.
Partial Denials
A claim may be partially approved while significant components remain excluded. Policyholders sometimes accept the first payment without realizing that omitted damage may be eligible for further review.
Our Public Adjusting Process
1. Claim Review
We begin by reviewing the reported loss, current claim status, carrier correspondence, estimates, photographs, and applicable policy information.
2. Property Inspection
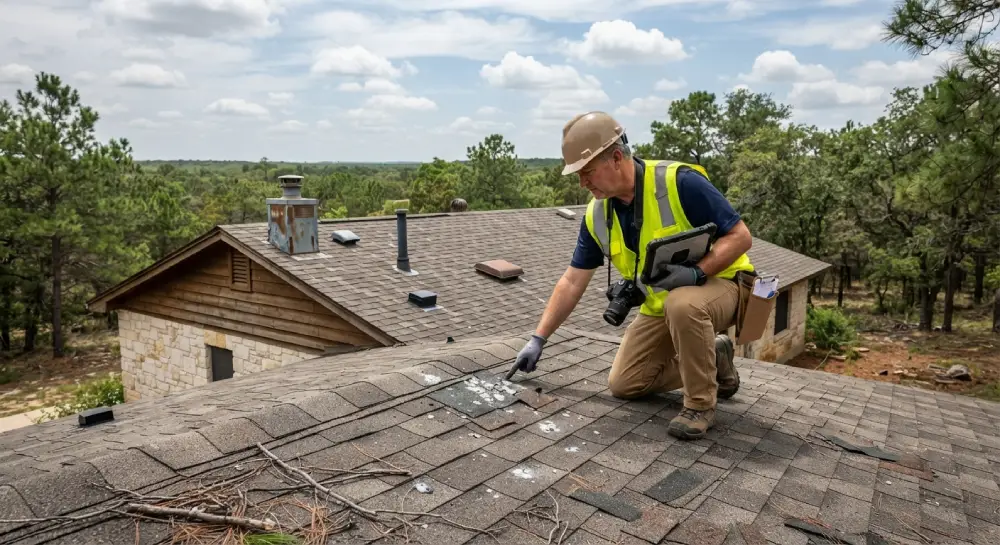
We inspect the property and document visible damage to the roof, exterior, interior, contents, or commercial operations, depending on the type of claim.
3. Scope and Documentation
We prepare a detailed account of damaged materials and necessary work. This may include measurements, photographs, estimates, inventories, invoices, and other supporting records.
4. Claim Presentation
We organize the claim information and communicate with the insurance company on the policyholder’s behalf.
5. Negotiation and Follow-Up
We address questions, estimate differences, omitted items, and supplemental documentation as the carrier evaluates the claim.
6. Settlement Review
We review settlement information with the policyholder and explain how the claim payment relates to the documented loss, policy provisions, depreciation, deductibles, and remaining repair requirements.
Concerned that your Bastrop claim is underpaid? Request a free claim review before accepting the carrier’s estimate as final.
Why Choose TX Public Adjusting
Licensed Texas Representation
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839.
We Represent Policyholders
We do not work for the insurance company. Our responsibility is to document and present the policyholder’s claim.
Residential and Commercial Experience
Our experience includes residential losses, commercial losses, roof claims, hail claims, water losses, fire claims, and complex property-damage documentation.
Texas-Focused Claim Knowledge
Texas claims involve severe hail, wind, wildfire, freeze events, hurricanes, water damage, and wide variations in construction. Our work is focused on Texas property owners.
Detailed Scope Review
A claim may be underpaid because of several small omissions rather than one obvious error. We compare the documented damage with the carrier’s estimate line by line.
Thousands of Claims Reviewed
Our team has reviewed thousands of property claims involving residential and commercial damage. That experience helps us recognize common omissions, documentation gaps, and scope disputes without inventing or promising a particular financial result.
No Upfront Fees
Property owners can request an initial claim review without paying an upfront fee. Any compensation terms are explained before representation begins and are subject to the signed agreement and applicable Texas requirements.
Areas We Serve Near Bastrop
TX Public Adjusting assists property owners throughout Bastrop and surrounding Bastrop County communities, including:
- Smithville
- Elgin
- Cedar Creek
- McDade
- Paige
- Red Rock
- Rosanky
- Wyldwood
- Camp Swift
- Circle D-KC Estates
- Tahitian Village
- Pine Forest
- The Colony
- Hunters Crossing
We also serve property owners across Central Texas, including communities toward Austin, Pflugerville, Manor, Lockhart, and surrounding areas.
Frequently Asked Questions
What does a public adjuster in Bastrop do?
Understanding what a public adjuster does begins with one central distinction: a public adjuster represents the policyholder during a property insurance claim. The work may include reviewing the policy, inspecting the damage, preparing an estimate, documenting contents, communicating with the carrier, and negotiating disputed or omitted items.
Unlike the carrier’s adjuster, a public adjuster does not represent the insurance company.
When should I hire a Bastrop public adjuster?
Property owners often hire a public adjuster after receiving a low estimate, partial denial, delayed response, or claim payment that does not appear sufficient for repairs. A public adjuster may also be hired early in a large or complicated loss.
It is usually better to request a review before signing releases, completing major repairs, discarding damaged materials, or allowing important claim deadlines to pass.
Can you help with a hail-damaged roof in Bastrop?
Yes. We inspect roof surfaces and related components such as ridge caps, vents, flashing, gutters, downspouts, screens, siding, and interior areas affected by leaks.
We also compare the carrier’s scope with the documented damage and identify items that may have been omitted.
Can a public adjuster help after a wildfire or house fire?
Yes. Fire claims may involve structural damage, smoke and soot, contents, debris removal, temporary housing, code requirements, and water used during firefighting.
Because Bastrop includes heavily wooded communities, smoke and wildfire-related claims may require detailed attention even when the structure was not completely destroyed.
What happens when water enters through my roof during a storm?
The claim should be evaluated based on how the opening occurred, when the water entered, what materials were affected, and what the policy covers.
Photograph the affected areas, take reasonable steps to prevent further damage, save receipts, and avoid making permanent repairs before the damage is fully documented when it is safe to do so.
Can you reopen or supplement an underpaid Bastrop claim?
Potentially. The options depend on the policy, cause of loss, claim history, deadlines, prior payments, and available documentation.
A free claim review can help determine whether additional inspection, documentation, or a supplemental claim may be appropriate.
How much does a public adjuster cost in Texas?
Public adjusters generally work under a written fee agreement that explains how compensation is calculated. The exact fee can depend on the type and status of the claim and must comply with applicable Texas requirements.
TX Public Adjusting explains the agreement before representation begins. There are no upfront fees for the initial claim review.
Will hiring a public adjuster guarantee a larger settlement?
No ethical public adjuster should guarantee a specific outcome. The result depends on the policy, facts of the loss, available evidence, covered damage, prior claim handling, and the carrier’s evaluation.
Our role is to prepare and present a detailed claim and advocate for the policyholder based on the documented loss.
Do you handle commercial property claims in Bastrop?
Yes. We assist with commercial claims involving storm damage, roof damage, water, fire, smoke, equipment, inventory, tenant areas, and business interruption when applicable.
Commercial claims often require coordination among owners, tenants, contractors, accountants, mitigation firms, and the insurance company.
What should I do immediately after property damage?
Protect people first. Contact emergency services when needed and take reasonable steps to prevent additional damage without putting yourself at risk.
Photograph the property, retain damaged materials when practical, save receipts, keep a claim communication log, and avoid assuming the carrier’s first estimate is complete. Then request a professional claim review.
Get a Free Bastrop Insurance Claim Review
A storm, fire, plumbing failure, or roof leak can affect far more of a property than the first inspection reveals. Before accepting an underpaid estimate or trying to manage a complicated claim alone, speak with a licensed Texas public adjuster.
TX Public Adjusting helps Bastrop homeowners, business owners, landlords, and commercial property owners document property damage and present insurance claims with clarity.
Rise Public Adjusting LLC
Texas License #3356839
Free Claim Review
No Upfront Fees
Residential and Commercial Claims
Request a free Bastrop claim review to discuss the damage, the carrier’s estimate, and the current status of your insurance claim.