Property damage in Point Blank can become complicated quickly. Homes near Lake Livingston face a different mix of risks than properties in a major Texas metro: strong thunderstorms crossing the lake, wind-driven rain, falling trees, roof damage, hail, plumbing losses, and inland tropical weather can all create insurance claims that involve more than one part of the property. If you need a Public Adjuster in Point Blank, TX Public Adjusting represents you—not the insurance company—and works to document the full extent of your covered loss.
TX Public Adjusting, operated by Rise Public Adjusting LLC, provides residential and commercial insurance claim assistance throughout Texas. We are a Licensed Texas Public Adjuster, License #3356839, and our team has reviewed thousands of property claims involving roofs, interiors, water damage, storms, fires, commercial buildings, and other covered losses.
If your Point Blank property claim has been delayed, underpaid, denied, or simply feels incomplete, you do not have to rely only on the carrier’s estimate. Request a Free Claim Review from TX Public Adjusting. There are no upfront fees.
Why Property Owners Hire a Public Adjuster in Point Blank
Point Blank is a small San Jacinto County community closely tied to Lake Livingston. Properties range from wooded residential lots and lake houses to second homes, RV-oriented properties, commercial buildings, and waterfront residences in communities such as Governor’s Point, Forest Cove, and Holiday Villages of Livingston.
That local property mix creates some distinctive claim problems.
A windstorm can damage a roof while also sending branches into siding, gutters, fencing, docks, or exterior structures. Wind-driven rain may enter through damaged roofing and affect insulation, ceilings, drywall, flooring, cabinetry, or personal property. A plumbing leak in a weekend or second home may go unnoticed longer than it would in an occupied primary residence.
A public adjuster helps organize those pieces into one documented claim.
The insurance company’s adjuster represents the insurer’s interests. A public insurance adjuster in Point Blank represents the policyholder. Our job is to inspect the property, review the policy and carrier estimate, document covered damage, prepare a detailed scope, and negotiate the claim based on the actual loss.
Property owners frequently contact TX Public Adjusting when:
- An insurance estimate does not appear sufficient to complete repairs.
- Roof damage was classified as repairable when broader damage may exist.
- Interior water damage was included but related materials were omitted.
- The carrier missed gutters, flashing, siding, fencing, detached structures, or other affected components.
- Depreciation was applied in a way the owner does not understand.
- A claim has stalled because documentation or estimates are incomplete.
- A commercial claim involves multiple building components or operational concerns.
- The owner simply wants an independent professional review before accepting a settlement.
Free Point Blank Claim Review
Not every claim requires a public adjuster. But when the damage is substantial, the scope is disputed, or the carrier’s numbers do not match the actual repair needs, getting another professional review can be valuable.
TX Public Adjusting offers a Free Claim Review with no upfront fees.
Property Damage Risks in Point Blank and the Lake Livingston Area
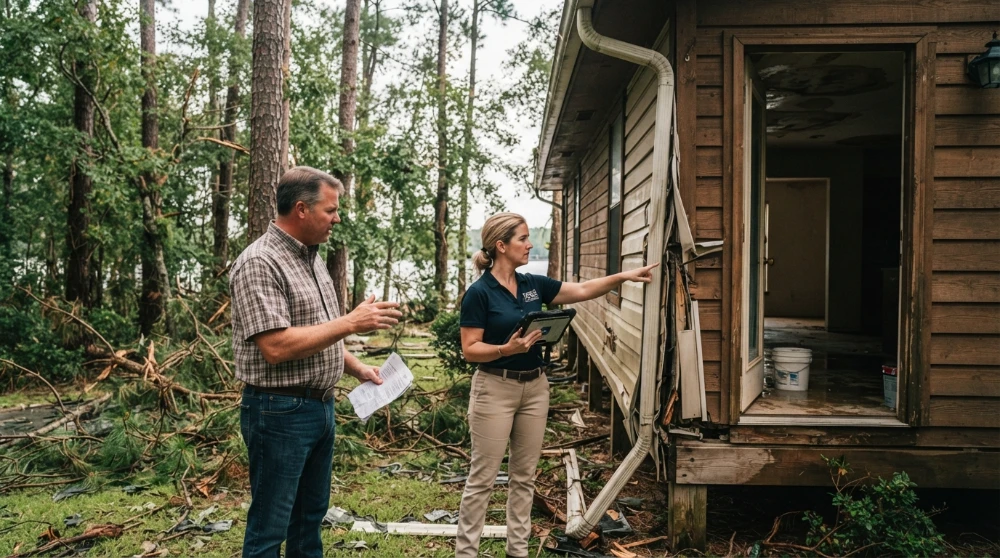
Point Blank’s location near Lake Livingston is one of the reasons people choose to live here, but the lake and surrounding wooded landscape also affect how storms can impact property.
National Weather Service warnings for San Jacinto County have documented strong thunderstorms with damaging wind, hail, heavy rainfall, and lightning, including storms affecting Point Blank and the Lake Livingston area. Tropical systems moving inland have also historically produced significant wind damage in San Jacinto County.
Wind and Thunderstorm Damage
Strong thunderstorms can develop rapidly across East Texas. Around Point Blank, high winds can lift shingles, damage ridge caps and flashing, break tree limbs, and send debris into roofs or exterior walls.
Wooded properties can be particularly vulnerable when mature trees or branches fall during storms. Even when a tree does not strike the main structure, it may damage fencing, detached buildings, electrical components, or other insured property.
Hail Damage
Hail does not have to create an obvious roof leak on the day of the storm to cause a legitimate property loss.
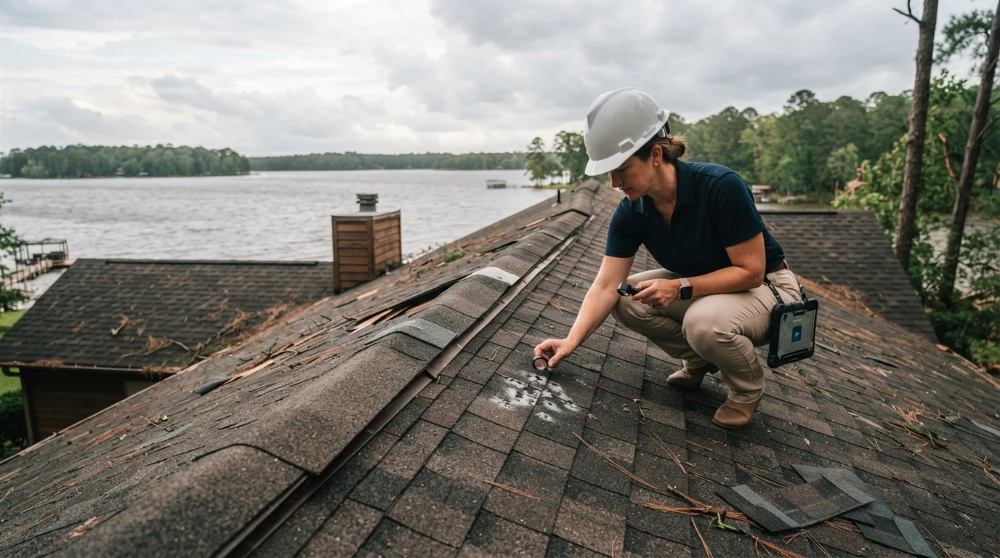
Asphalt shingles can experience impact damage that is difficult to identify from the ground. Metal components such as vents, gutters, flashing, HVAC equipment, and soft metals may also provide evidence of hail impact.
For a deeper look at these losses, see our Texas Hail Damage Roof Insurance Claim Guide.
Heavy Rain and Water Intrusion
San Jacinto County can experience heavy rainfall and localized flooding in low-lying or poor-drainage areas.
For an insurance claim, the cause of water intrusion matters. Water entering through storm-created roof or exterior damage can involve different coverage questions than rising surface water or long-term seepage. A careful inspection helps establish what happened, where water traveled, and which materials were affected.
Learn more about water damage public adjuster services.
Tropical Storm and Hurricane Remnants
Point Blank is inland, but inland does not mean immune from tropical systems.
Historic tropical cyclones affecting Southeast Texas have produced severe wind impacts in San Jacinto County, including extensive tree damage and property losses near Lake Livingston.
For property owners, this means hurricane-related claims may involve roof damage, fallen trees, wind-driven rain, exterior damage, electrical issues, and interior water intrusion even many miles from the Gulf Coast.
Common Insurance Claims in Point Blank
Hail Damage Claims
After a hailstorm, we look beyond a few visible marks on the shingles.
A complete hail inspection may involve roofing materials, ridge caps, vents, flashing, gutters, downspouts, window components, exterior finishes, fencing, HVAC equipment, and other impacted surfaces.
A carrier estimate may include the obvious damage while overlooking related items necessary to restore the property.
Water Damage Claims
Water losses can spread well beyond the place where the leak first becomes visible.
A ceiling stain may indicate wet insulation, damaged drywall, affected paint, flooring issues, cabinetry damage, or moisture behind walls. Plumbing leaks can also create mitigation and drying costs.
Our role is to document the extent of covered water damage and compare the full repair scope with what the carrier included.
Fire and Smoke Damage Claims
A fire claim can involve much more than rebuilding the visibly burned area.
Smoke can travel through adjoining rooms, HVAC systems, attic spaces, contents, insulation, and porous materials. The claim may include structural repairs, cleaning, contents, odor treatment, electrical components, temporary housing, and other policy benefits.
Our Fire Insurance Adjuster guide explains how these claims are evaluated.
Storm Damage Claims
Point Blank storm claims may involve several types of damage at the same time.
A single severe thunderstorm could affect:
- Roofing and flashing
- Trees and limbs
- Gutters and exterior finishes
- Windows and doors
- Fences
- Detached structures
- Interior ceilings and walls
- Electrical systems
- Personal property
Treating each item separately without understanding the entire loss can result in an incomplete claim.
Roof Damage Claims
Roof claims are among the most disputed property claims because the difference between a repair and a broader replacement scope can be significant.
Our inspection looks at the roof system as a whole, including slopes, shingles or other roofing materials, flashing, penetrations, ridge components, vents, accessories, and storm-related collateral damage.
Read more in our Public Adjuster for Roof Claim guide.
Commercial Property Claims
Businesses and commercial property owners in and around Point Blank may have additional considerations after a loss.
Commercial policies can involve roofing systems, equipment, inventory, tenant improvements, code requirements, business-related expenses, and larger repair scopes.
TX Public Adjusting handles both residential and commercial property claims. Visit our Commercial Claims page for additional information.
Why Point Blank Insurance Claims Become Underpaid
An underpaid claim does not always result from one large mistake. More often, several smaller omissions add up.
Missed Damage
Some damage is easy to see. Other damage requires a closer inspection.
Roof accessories, flashing, gutters, interior finishes, insulation, fencing, detached structures, and other items can be missed during a brief inspection.
Scope Omissions
A scope may acknowledge damage but fail to include all the work necessary to restore the property.
For example, replacing damaged drywall may also require insulation work, texture, primer, paint, trim work, removal and replacement of adjoining materials, or labor necessary to access the damaged area.
The difference between acknowledging damage and fully pricing the repair can be substantial.
Depreciation Issues
Property estimates may include depreciation based on age, condition, material, or policy provisions.
We review how depreciation was applied and whether the carrier’s calculation aligns with the policy and documented condition of the property.
Low Repair Estimates
The carrier’s estimate is not necessarily the final word on what the claim should include.
Insurance estimates can differ from contractor estimates because of quantities, labor assumptions, material pricing, omitted operations, or disagreements about the repair method.
Our job is to identify and document those differences.
Documentation Problems
Photographs alone do not always tell the whole story.
Strong property damage claims may require measurements, detailed estimates, inventories, invoices, moisture documentation, reports, policy analysis, repair specifications, and organized communication with the insurance carrier.
Incomplete documentation can make otherwise legitimate damage harder to establish.
Our Public Adjusting Process
1. Claim Review
We start by reviewing what has happened with your claim.
That may include your policy, carrier correspondence, estimate, payment information, photographs, contractor documents, and any denial or coverage letters.
2. Property Inspection
We inspect the damaged property to identify visible and related areas of loss.
For a Point Blank storm claim, that could mean evaluating roofing, exterior elevations, gutters, trees or impact areas, interior water damage, detached structures, and other affected components.
3. Claim Documentation
We build documentation to support the claim.
Depending on the loss, that may include photographs, measurements, estimates, inventories, reports, invoices, damage descriptions, and supporting records.
4. Scope Review and Negotiation
We compare our findings with the carrier’s estimate and identify differences in quantities, pricing, materials, repair methods, or omitted damage.
We then communicate and negotiate with the insurer on behalf of the policyholder.
5. Settlement and Claim Resolution
Our goal is to help move the claim toward a properly documented resolution based on the policy and covered loss.
Every claim is different, and no public adjuster can promise a specific settlement amount. What we can do is make sure your claim is presented professionally, thoroughly, and from the policyholder’s side of the table.
Why Choose TX Public Adjusting in Point Blank?
Licensed Texas Public Adjuster
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839.
Licensing matters. Property owners should know who is representing them and verify that the person handling the claim is properly licensed to perform public adjusting services in Texas.
We Represent Policyholders
Insurance company adjusters and independent adjusters hired by carriers work within the insurer’s claim process.
A public adjuster has a different role.
We work for you, the policyholder.
Texas-Focused Claim Experience
Texas property claims come with familiar patterns: hail, high winds, hurricanes, burst pipes, freezes, water losses, fires, roof disputes, and large commercial losses.
Our experience reviewing thousands of claims gives us perspective on the details that are frequently disputed or omitted.
Residential and Commercial Experience
We work with homeowners as well as commercial property owners.
That can include houses, second homes, lake properties, retail buildings, offices, churches, apartments, warehouses, restaurants, and other insured properties.
Detailed Claim Documentation
Insurance claims are won or lost on facts, coverage, documentation, and the ability to show what the property actually requires.
We focus on building a clear claim file rather than simply arguing that the carrier’s number is too low.
No Upfront Fees
TX Public Adjusting offers a Free Claim Review and no upfront fees.
If you are unsure whether your claim needs professional representation, start with a review.
Local Property Claims Around Lake Livingston
Point Blank’s identity is closely connected to Lake Livingston. The area includes waterfront properties, wooded subdivisions, weekend homes, retirement properties, and homes with docks or other exterior improvements.
Governor’s Point is a Lake Livingston subdivision with its own fishing pier and community amenities, while Forest Cove identifies itself as a wooded subdivision on the lake. Holiday Villages of Livingston also maintains an established Point Blank community.
Those property characteristics matter after a storm.
A wooded lot increases exposure to falling limbs and debris. Waterfront exposure can mean stronger unobstructed wind across the lake. Second homes may sit unattended between visits, allowing leaks to cause additional interior damage before they are discovered.
That is why we do not treat a Point Blank insurance claim like a generic Texas claim. The property’s construction, location, use, and damage pattern all need to be considered.
Areas We Serve Near Point Blank
TX Public Adjusting serves property owners throughout the Lake Livingston region and surrounding East Texas communities.
Nearby service areas include:
- Coldspring Public Adjuster
- Livingston Public Adjuster
- Onalaska Public Adjuster
- Goodrich Public Adjuster
- Oakhurst Public Adjuster
- New Waverly
- Shepherd
- Waterwood
- Other communities throughout San Jacinto County and the Lake Livingston area
If your property is outside Point Blank, contact us. TX Public Adjusting serves policyholders across Texas.
Frequently Asked Questions About Public Adjusters in Point Blank
What does a public adjuster in Point Blank do?
A public adjuster represents the property owner during an insurance claim. We review the policy and carrier documents, inspect damage, prepare supporting documentation, identify missed or under-scoped items, and negotiate with the insurance company.
For Point Blank property owners, that can be especially useful after wind, hail, tree, roof, water, or tropical-weather damage around the Lake Livingston area.
When should I hire a public adjuster after property damage?
You can contact a public adjuster shortly after the loss or later if problems develop.
Property owners commonly call us when the carrier’s estimate looks too low, important damage was left out, communication has stalled, or the insurer has denied part of the claim.
If you are already several weeks or months into the process, read When Is It Too Late to Hire a Public Adjuster?.
Can you help if my Point Blank roof claim was underpaid?
Yes. Roof claims are a major part of our work.
We can inspect the roof and related property components, compare the findings with the insurer’s estimate, and identify potential omissions involving materials, quantities, accessories, flashing, gutters, related interior damage, or other covered items.
Can a public adjuster help with water damage near Lake Livingston?
Yes, when the water loss involves covered property damage.
Water claims require careful attention to the cause of loss. A burst pipe, sudden plumbing failure, or water entering through storm-created damage can raise different coverage issues than flooding or long-term seepage.
We review the policy and facts before advising you about how we may be able to help.
What if a tree falls on my home during a Point Blank storm?
A fallen tree may cause roof, structural, electrical, siding, window, interior, or contents damage.
The visible impact point is only part of the inspection. We look at the broader damage pattern and document affected areas so the claim reflects the actual scope of the covered loss.
Do you handle second homes and lake houses in Point Blank?
Yes.
Lake Livingston includes many properties used as second homes, vacation homes, retirement properties, and weekend residences. These losses can become complicated when damage is not discovered immediately.
We review the circumstances, policy, timing, and documentation to determine how we can assist.
Do you handle commercial property claims in Point Blank?
Yes. TX Public Adjusting works on residential and commercial claims.
Commercial claims can involve larger roof systems, equipment, inventory, tenant areas, code-related repairs, operational disruption, and more complex documentation. We help organize and present those losses from the property owner’s perspective.
How much does a public adjuster cost in Texas?
Public adjusters generally work under a written agreement that explains how compensation is calculated. Texas law regulates public adjusting contracts and fees.
TX Public Adjusting provides a Free Claim Review with no upfront fees, so you can discuss the claim first and understand the agreement before deciding whether to hire us.
Can you help if the insurance company already paid my claim?
Possibly.
Receiving an initial payment does not automatically mean every covered item has been addressed. Depending on the policy, circumstances, deadlines, and claim status, additional documentation or a supplemental claim may still be possible.
We can review your existing estimate and payment information and explain what options may remain.
Why hire TX Public Adjusting instead of relying only on the carrier’s adjuster?
Because the roles are different.
The insurance company’s adjuster handles the claim for the insurer. TX Public Adjusting represents you. We independently evaluate the damage, review the carrier’s scope, prepare supporting documentation, and advocate for the policyholder throughout the claim process.
For a property owner facing a substantial loss, that independent representation can make the claim easier to understand and more thoroughly documented.
Get Insurance Claim Help in Point Blank
If your home, lake property, rental, second home, or commercial building has been damaged, you do not have to determine the value of the claim by yourself.
TX Public Adjusting can review your policy, inspect the damage, compare your loss with the insurance company’s estimate, and explain what may be missing.
TX Public Adjusting
Rise Public Adjusting LLC
Texas Public Adjuster License #3356839
Free Claim Review. No upfront fees. Residential and commercial claims.
Contact TX Public Adjusting today to request an independent review of your Point Blank property damage claim.