

Property damage in Brookside Village can turn into a complicated insurance claim quickly. This small Brazoria County community sits just northwest of Pearland, close enough to the Gulf Coast to face tropical storms, hurricane-driven wind and rain, severe thunderstorms, hail, and drainage-related water problems. For homeowners with acreage, detached structures, mature trees, older roofs, or multiple improvements on the same property, documenting the complete loss can require far more than a quick insurance inspection.
TX Public Adjusting provides public adjuster services in Brookside Village, TX for residential and commercial property owners who need help preparing, reviewing, or negotiating an insurance claim. We represent the policyholder—not the insurance company. TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839.
If your Brookside Village insurance claim has been delayed, denied, underpaid, or simply does not appear to include all the damage, request a Free Claim Review. There are no upfront fees, and our team can evaluate the carrier’s estimate, the documented damage, and the current status of your claim before you decide how to proceed.
Brookside Village is located in Brazoria County immediately beside Pearland and retains a noticeably more rural, acreage-oriented character than many surrounding Houston-area communities. The City of Brookside Village also continues to address local drainage infrastructure, including drainage construction announced for Max, Gerda, and Lesiker Streets in 2026.
Why Property Owners Hire a Public Adjuster in Brookside Village
An insurance company sends an adjuster to investigate a loss on behalf of the carrier. A public adjuster in Brookside Village has a different role: representing you, the policyholder.
That distinction becomes especially meaningful when a property has several different types of damage after the same storm. A roof may have wind or hail damage while gutters, fencing, siding, windows, a detached garage, or interior finishes also need evaluation. Water entering through a storm-created opening can produce another layer of damage that may not be obvious during a short inspection.
Brookside Village properties can also differ considerably from the dense suburban development found nearby. The community is known for larger residential lots and a mix of traditional and ranch-style homes, making complete property documentation particularly important when a loss involves more than the primary structure.
A Brookside Village public insurance adjuster can help with:
- Reviewing your insurance policy and claim documents
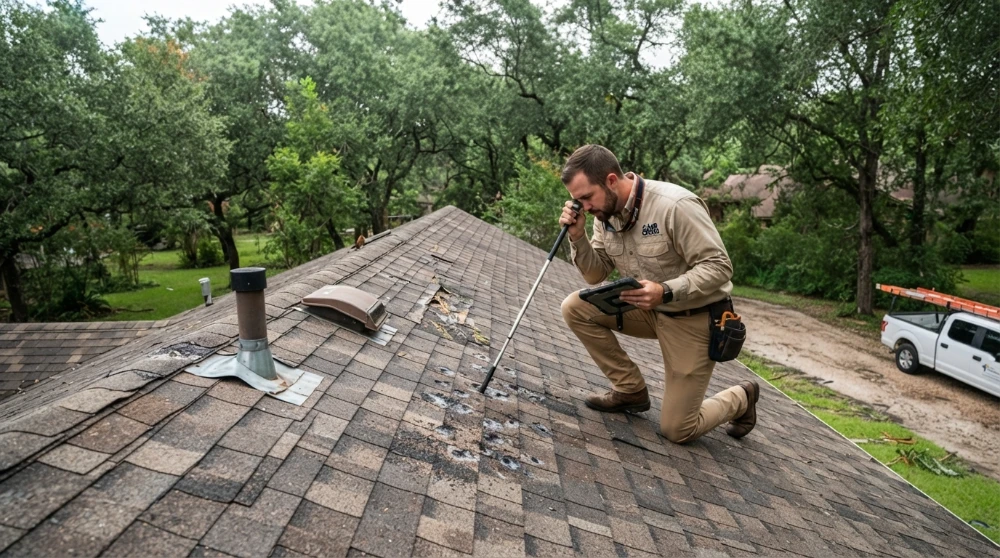
- Conducting a detailed inspection of the reported damage
- Comparing the carrier’s estimate against conditions at the property
- Photographing and documenting covered damage
- Identifying omitted areas or repair components
- Organizing estimates and supporting claim information
- Communicating with the insurance carrier about the scope of loss
- Negotiating disputed or underpaid property damage claims
Our team has reviewed thousands of residential and commercial claims. That experience matters because insurance losses are rarely resolved by simply identifying a damaged roof. The claim must connect the physical damage, policy provisions, repair scope, quantities, pricing, and supporting documentation.
Free Brookside Village Claim Review
Already received an estimate from your carrier?
TX Public Adjusting can review it with you and discuss whether the scope appears consistent with the damage being claimed. Contact TX Public Adjusting for a Free Claim Review. No upfront fees.
Storm and Weather Risks in Brookside Village
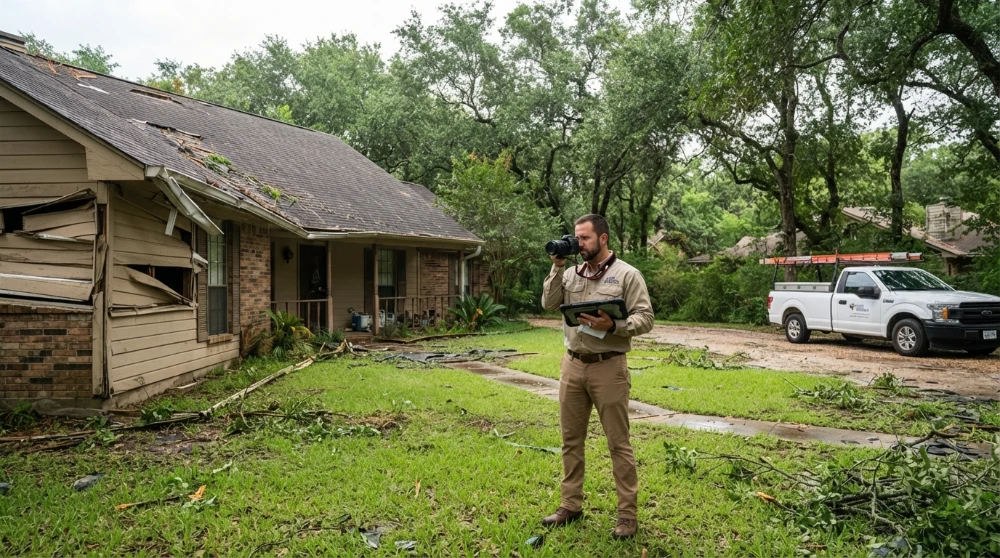
Brookside Village’s location in northern Brazoria County creates a different property-risk profile from cities farther inland. The community lies only a few miles from Pearland and within the greater Houston/Gulf Coast weather region. Pearland is approximately three miles away, while Friendswood and Manvel are also nearby.
Hurricanes and Tropical Storms
Tropical systems approaching the upper Texas Gulf Coast can bring damaging wind well inland from the immediate coastline. Property owners dealing with Texas hurricane property damage may face roof damage, wind-driven rain, fallen trees, damaged exterior components, and interior water intrusion from the same storm. For Brookside Village property owners, hurricane claims can involve more than missing shingles.
A significant tropical-weather claim may include:
- Wind-damaged roofing
- Lifted or creased shingles
- Damaged flashing and vents
- Fallen-tree impact
- Broken fencing
- Window and door damage
- Detached-building damage
- Wind-driven rain entering through storm-created openings
- Wet insulation, drywall, flooring, or ceilings
- Business interruption or damaged commercial property
One of the hardest parts of some storm claims is distinguishing between different causes of water damage. Standard property policies may treat wind-created openings, roof leaks, surface flooding, and rising water differently. Coverage depends on the specific policy and facts of the loss, which is why documenting the pathway of water intrusion can be critical.
Heavy Rain and Drainage Problems
Brookside Village is a low-elevation Gulf Coast-area community where heavy rainfall and drainage are practical concerns. The city’s current public information includes drainage construction on Max, Gerda, and Lesiker Streets, illustrating how locally significant drainage management can be.
Not every water loss is covered under the same policy. Surface flooding is commonly treated differently from rain entering through covered storm damage, plumbing leaks, or other insured causes. Our job is not to assume coverage. It is to document what happened, identify the physical source of damage, review the applicable policy language, and present the covered portions accurately.
Hail and Severe Thunderstorms
Brookside Village is also exposed to Texas thunderstorms capable of producing hail, strong straight-line wind, lightning, and sudden heavy rain.
Hail damage can be difficult for a property owner to evaluate from the ground. Property owners can review our guide on how to document hail damage for an insurance claim before cleanup or repairs begin. An asphalt roof may still appear intact while individual shingles have impact fractures or granule displacement. Soft-metal components such as vents, gutters, downspouts, flashing, and HVAC fins can provide additional evidence of a hail event.
For commercial roofs, hail can affect membranes, metal panels, rooftop equipment, coatings, skylights, and drainage components.
Wind and Tree Damage
The mature trees and larger lots that contribute to Brookside Village’s rural-suburban character can become significant factors during severe weather. Falling limbs may damage roofing, garages, fencing, sheds, exterior mechanical equipment, or vehicles.
The resulting claim can involve both visible impact damage and secondary water intrusion. A carrier estimate that addresses only the obvious broken materials may leave necessary repair work out of the scope.
Common Insurance Claims in Brookside Village
Hail Damage Claims
A hail claim should document the complete storm impact, not simply count damaged shingles.
We inspect and document roofing along with components such as:
- Gutters and downspouts
- Roof vents
- Flashing
- Metal trim
- Siding
- Window screens
- Exterior finishes
- HVAC equipment
- Detached structures
If your insurer has already inspected the property but the estimate seems too small for the actual damage, we can review the scope and help determine what may have been missed. For a deeper explanation of roof inspections, insurance estimates, and storm-related damage, read our hail damage roof insurance claim guide for Texas property owners.
Water Damage Claims
Water damage claims in Brookside Village may come from plumbing failures, appliance leaks, roof openings, wind-driven rain, or other sudden events.
These claims often become disputed because the visible stain on a ceiling is only the beginning. Moisture may extend into insulation, wall cavities, flooring, cabinets, electrical components, or adjacent rooms.
A proper claim review examines both the source and the resulting damage.
A water damage public adjuster can help evaluate the documented source of the loss, resulting property damage, carrier scope, and repair estimate when a covered water claim becomes disputed or underpaid.
Fire and Smoke Damage Claims
Fire claims can become some of the most detailed property claims we handle. Beyond burned materials, there may be smoke contamination, soot, odor, contents losses, water from firefighting activity, electrical damage, and temporary living or operating expenses.
A Brookside Village fire claim involving a home on a larger lot may also require documentation of garages, workshops, storage structures, fencing, equipment, or other insured property.
TX Public Adjusting helps organize the different components of the loss so they can be presented as a complete claim rather than a collection of disconnected repair issues. Learn more about the role of a fire insurance adjuster when a significant property fire creates structural, contents, smoke, or water damage.
Storm Damage Claims
A single severe thunderstorm can create a combination of wind, hail, rain, fallen debris, and roof damage.
Those combined losses are where scope problems frequently appear. One portion of the property gets documented thoroughly while another is overlooked.
We evaluate the full property and compare our findings against the carrier’s estimate.
Roof Damage Claims
Roof claims are among the most frequent reasons property owners contact a public adjuster.
Disputes can involve:
- Repair versus replacement
- Missing roofing components
- Incomplete measurements
- Underestimated labor
- Flashing and ventilation omissions
- Matching issues
- Interior damage connected to a roof opening
- Depreciation calculations
- Code-related repair items when applicable
If the insurer’s estimate does not appear to reflect the repairs actually required, a public adjuster for a roof claim can review the documented damage, measurements, repair scope, and carrier estimate.
Commercial Property Claims
Although Brookside Village is primarily residential, commercial property owners throughout the Pearland-Brookside area also face substantial losses from hail, wind, water, fire, and tropical weather.
Commercial claims may involve roofing systems, inventories, tenant improvements, equipment, exterior systems, business personal property, and interruption-related issues depending on the policy.
Our commercial public adjuster services include property claims involving offices, apartment properties, retail operations, restaurants, warehouses, self-storage facilities, churches, and other Texas businesses. Relevant commercial claim pages are included throughout the TX Public Adjusting site structure.
What Makes Brookside Village Property Claims Different?
Brookside Village is not simply another subdivision inside Houston.
The city covers only a little over two square miles and is characterized by low-density residential development, larger lots, mature vegetation, and varied housing styles. It sits directly beside the much larger Pearland market while maintaining its own municipal identity in Brazoria County.
Because the city does not divide neatly into numerous large named subdivisions, local claim inspections are better understood by residential pockets and streets than by artificial neighborhood labels. We commonly think of Brookside Village in terms of the acreage properties and residential streets around Brookside Road, Max Road, Gerda Street, Lesiker Street, and the edges of the community closest to Pearland.
Nearby reference points include Brookside Village City Hall and Community Center, the Pearland area, and Tom Bass Regional Park to the north. Tom Bass Regional Park is also commonly cited as one of the major recreational destinations near the community.
That local property pattern matters after a storm. A loss may involve a main residence, detached garage, workshop, fencing, gates, trees, outbuildings, and other improvements spread across a larger site. An inspection focused only on the roof of the principal structure can miss meaningful portions of the claim.
Why Insurance Claims Become Underpaid
Insurance claims can be underpaid without the property owner immediately realizing it.
The carrier may issue a detailed-looking estimate with many pages of line items. The question is not how long the estimate is. The question is whether it accurately describes the damage and the work required to restore the insured property.
Missed Damage
Short inspections can overlook secondary structures, elevation-specific damage, interior moisture, siding, fencing, gutters, flashing, or mechanical components. Roof losses can be especially susceptible to scope omissions, which is why property owners should understand what insurance adjusters miss on roof claims before accepting an estimate as complete.
Scope Omissions
A repair estimate may recognize a damaged material but leave out the labor or related work needed to properly remove, replace, access, finish, or reinstall it.
Depreciation Issues
Depreciation can materially affect the amount initially paid on a claim. We review how depreciation has been applied and whether the carrier’s calculations correspond with the documented property and policy.
Low Estimates
Material and labor pricing, quantities, waste factors, repair methods, and required trades can all affect the estimated loss.
An estimate that looks close at first glance can become substantially different once omitted components are added.
Documentation Problems
Insurance companies make decisions based on the information in the claim file. Missing photographs, incomplete inventories, unclear moisture documentation, weak estimates, or inconsistent descriptions can make legitimate damage harder to evaluate.
Our role is to build an organized claim file supported by the physical evidence.
Our Public Adjusting Process
1. Claim Review
We begin by reviewing your situation, insurance documents, carrier correspondence, estimates, and payments already issued.
If the claim is already underway, you do not necessarily have to start over. A public adjuster can often become involved after an initial inspection or payment, depending on the circumstances and applicable deadlines.
2. Property Inspection
We inspect the reported loss and document relevant damage throughout the property.
For Brookside Village properties, that can include the main dwelling plus garages, workshops, fencing, exterior improvements, and other insured structures when applicable.
3. Documentation and Scope Preparation
We organize photographs, measurements, estimates, inventories, and other claim evidence.
The goal is to create a clear connection between what was damaged and what is required to repair or replace it.
4. Insurance Company Communication and Negotiation
TX Public Adjusting communicates with the carrier regarding the documented claim and addresses scope or valuation disagreements.
We advocate for the policyholder using the facts of the loss, supporting documentation, and applicable insurance policy provisions.
5. Claim Resolution
We continue working through the claim process toward an appropriate settlement based on covered damage.
No public adjuster can guarantee a particular settlement. What we can provide is experienced, independent representation and a properly documented claim presentation.
Why Choose TX Public Adjusting?
Property owners hire us because they want someone on their side of the insurance claim.
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839.
Our approach includes:
- Licensed Texas public adjuster representation
- Residential and commercial claim experience
- Thousands of claims reviewed
- Texas-focused storm and property-loss experience
- Independent representation for policyholders
- Detailed inspections and claim documentation
- Carrier estimate and scope reviews
- Negotiation of disputed and underpaid claims
- Free Claim Review
- No upfront fees
Insurance company adjusters perform an important role, but they represent the insurance carrier. A public adjuster represents the policyholder. That independence is the foundation of our service.
Concerned Your Brookside Village Claim Is Too Low?
A low insurance estimate does not automatically mean the carrier acted improperly. It may mean additional documentation, measurements, damage evidence, or scope clarification is needed.
Send TX Public Adjusting the estimate and tell us what happened.
Request your Free Claim Review today.
Areas We Serve Near Brookside Village
Our Brookside Village public adjusting services extend throughout the surrounding Brazoria County and southeast Houston area. Pearland is the closest major neighboring city, with Friendswood, Manvel, Fresno, South Houston, and Iowa Colony also located nearby.
We serve property owners in and around:
- Pearland
- Friendswood
- Manvel
- Fresno
- Iowa Colony
- South Houston
- Pasadena
- League City
- Greater Houston
The existing Pearland area page is confirmed in the TX Public Adjusting site inventory.
Frequently Asked Questions About Public Adjusters in Brookside Village
What does a public adjuster in Brookside Village do?
A public adjuster represents you during a property insurance claim. We inspect damage, review the policy and carrier estimate, prepare supporting documentation, and communicate with the insurance company regarding disputed scope or value.
Unlike the insurance company’s adjuster, TX Public Adjusting works for the policyholder.
When should I hire a public adjuster after a Brookside Village storm?
You can contact a public adjuster soon after discovering significant damage, but many property owners first call us after receiving an estimate that seems incomplete or a settlement that does not appear sufficient for the documented repairs.
Getting help earlier can make documentation easier because storm conditions and damaged materials have not yet changed through cleanup or repairs.
Can you help after the insurance company has already paid my claim?
Potentially, yes. Receiving an initial payment does not necessarily mean every issue in the claim has been resolved. We can review the carrier estimate, documentation, payments, and policy to determine whether additional covered damage or omitted scope may warrant further discussion. Because deadlines can matter, property owners should also understand when it may be too late to hire a public adjuster.
Can a Brookside Village public adjuster help with hurricane damage?
Yes. We handle wind, roof, rain intrusion, contents, commercial, and other property damage claims associated with hurricanes and tropical storms when coverage applies.
Because water damage after a Gulf Coast storm can have several possible causes, we focus closely on documenting how the structure was damaged and how water entered the property.
Do you handle hail claims in Brookside Village?
Yes. Hail can damage shingles, gutters, vents, flashing, siding, HVAC components, fencing, windows, and commercial roofing systems.
If your insurance company says the roof has little or no storm damage but you believe the inspection missed something, we can perform an independent claim review.
What if my Brookside Village roof claim was underpaid?
We can compare the carrier’s roof estimate against documented conditions at the property and identify possible omissions in quantities, materials, labor, associated components, or interior damage.
An underpaid claim often requires more than requesting additional money. It requires evidence showing why a different repair scope or valuation is justified.
Can you help with water damage caused by heavy rain?
It depends on the cause and your policy. Water entering through storm damage may be treated differently from surface flooding or rising water.
We document the source and pathway of the water rather than assuming all water damage is covered the same way.
Do you work on Brookside Village commercial insurance claims?
Yes. TX Public Adjusting represents both residential and commercial policyholders.
Commercial losses can involve roofing, interior build-outs, equipment, inventory, business personal property, and interruption-related issues depending on the policy.
How much does it cost to have TX Public Adjusting review my claim?
The initial claim review is free, and there are no upfront fees.
If representation makes sense, the engagement terms and public adjusting fee are explained before you hire us so you know how the arrangement works.
Why hire a public adjuster instead of relying only on the insurance company’s adjuster?
The difference is who the adjuster represents.
The insurance company’s adjuster works on behalf of the carrier. A licensed public adjuster works on behalf of the policyholder. We independently document the loss and advocate for your interests during the claim process.
Get Insurance Claim Help in Brookside Village, TX
When your home or business has been damaged, you should not have to guess whether the insurance estimate includes everything that was lost.
TX Public Adjusting helps Brookside Village property owners document storm damage, review insurance estimates, address scope omissions, and negotiate disputed or underpaid claims.
TX Public Adjusting
Operated by Rise Public Adjusting LLC
Texas License #3356839
Free Claim Review. No upfront fees. Residential and commercial claims.
Contact TX Public Adjusting today and let us review your Brookside Village property damage claim.