

Property damage in Quintana can become serious quickly. This small Brazoria County community sits directly on the Texas Gulf Coast near the mouth of the Brazos River, Freeport Harbor, and the Gulf of Mexico. That location gives property owners beautiful coastal surroundings, but it also creates exposure to hurricanes, tropical storms, strong coastal winds, wind-driven rain, storm surge, salt-air deterioration, roof damage, and water intrusion. Quintana Beach County Park, the Quintana Jetty, and the nearby ship channel make the town unmistakably coastal—and insurance claims here often reflect that environment.
If you need a public adjuster in Quintana, TX Public Adjusting represents you as the policyholder, not the insurance company. We inspect property damage, review insurance estimates, document the scope of loss, identify items that may have been overlooked, and negotiate the claim based on the policy and available evidence.
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839. We assist residential and commercial property owners throughout Texas and have experience reviewing thousands of claims involving storm, roof, water, fire, hail, hurricane, and commercial property damage.
Need help with an insurance claim in Quintana? Request a Free Claim Review from TX Public Adjusting. There is no upfront fee for the claim review.
Why Property Owners Hire a Public Adjuster in Quintana
Quintana is not an inland suburb where storm damage is limited to an occasional thunderstorm. It is a barrier-coast community exposed directly to Gulf weather.
The town lies on the western side of the Freeport Harbor channel, across from Surfside Beach and only a short distance from Freeport. Quintana Beach County Park reaches the Gulf shoreline, while the Quintana Jetty forms part of the entrance to the Freeport ship channel. Brazoria County identifies hurricanes and flooding as longstanding regional hazards, and Quintana’s own history has repeatedly been shaped by major coastal storms.
That coastal setting can complicate an insurance loss. A single tropical system may produce several different kinds of damage at the same property:
- Wind-lifted or missing roofing materials
- Damaged flashing, vents, gutters, and exterior components
- Wind-driven rain entering through compromised roofing or openings
- Interior ceiling, wall, insulation, and flooring damage
- Broken windows or damaged doors
- Siding and exterior finish damage
- Water entering around roof penetrations
- Detached structure damage
- Commercial roof and equipment damage
- Debris impact
- Electrical or mechanical damage
Determining what happened, documenting when it happened, and separating potentially covered wind or rain damage from excluded flood or storm-surge damage can be especially important along the Gulf Coast.
A public insurance adjuster in Quintana works for the policyholder. The insurance company’s adjuster works on behalf of the insurer. That distinction matters when there is disagreement about the cause of damage, the amount of damage, repair methods, pricing, depreciation, or what should be included in the claim.
Quintana’s Coastal Storm and Property Damage Risks
Quintana deserves a storm discussion of its own because geography drives many of the insurance issues property owners face here.
Hurricanes and Tropical Storms
Direct Gulf exposure puts Quintana in a location where tropical systems can bring intense winds, heavy rain, airborne debris, and prolonged weather exposure. Historical accounts show that storms have played a major role in the community’s development, including the devastating 1900 hurricane that heavily affected the Brazoria County coastline.
Modern buildings may be stronger, but hurricane claims are still complicated. Roof damage may occur before interior water intrusion becomes visible. Wind can loosen roofing materials without removing them completely. Flashing can separate. Water can enter through vulnerable transitions and openings.
Documentation should therefore extend beyond the obvious damaged room. Property owners dealing with a major coastal storm can also review our guide to hurricane property damage claims for a closer look at the types of damage that can follow a hurricane.
Storm Surge and Flooding
Because Quintana is directly on the coast, property owners also have to think carefully about flood and storm-surge issues.
Flood coverage is often separate from a standard homeowners or commercial property policy. After a major coastal storm, one structure may have wind damage that falls under one policy and flood-related damage that falls under another.
That makes cause-of-loss documentation especially important. A public adjuster can evaluate the property claim and help document potentially covered damage, but coverage always depends on the actual policies, endorsements, exclusions, deductibles, and facts of the loss.
Coastal Wind and Wind-Driven Rain
Not every serious Quintana claim comes from a named hurricane.
Strong Gulf winds can damage shingles, membrane roofing, metal components, siding, fencing, soffits, fascia, windows, and exterior attachments. Once the building envelope is compromised, rain can reach insulation, ceilings, drywall, flooring, cabinets, equipment, or contents.
These claims sometimes become underpaid when the estimate focuses only on the visible interior stain instead of the exterior opening that caused it.
Salt-Air Exposure
Salt air is part of everyday life near Quintana Beach and the Freeport channel. Although normal deterioration and corrosion are generally maintenance issues rather than sudden covered losses, pre-existing coastal wear can become a point of disagreement after a storm.
For example, an insurer may attribute damaged metal components to corrosion while the policyholder believes a wind event caused sudden physical damage.
Clear photographs, maintenance records, weather information, inspection findings, and a well-defined scope can help distinguish old conditions from new storm damage.
Severe Thunderstorms and Hail
Quintana’s hurricane exposure gets the most attention, but Brazoria County properties can also experience severe thunderstorms, lightning, hail, and powerful straight-line winds.
Hail may affect shingles, metal roofing, vents, flashing, gutters, HVAC components, siding, windows, and commercial roof systems. Damage is not always obvious from ground level, which is one reason a thorough property inspection matters. If a Quintana storm damages your roofing system, our guide to hail damage roof insurance claims explains common roof damage, documentation issues, and insurance claim concerns.
Common Insurance Claims in Quintana
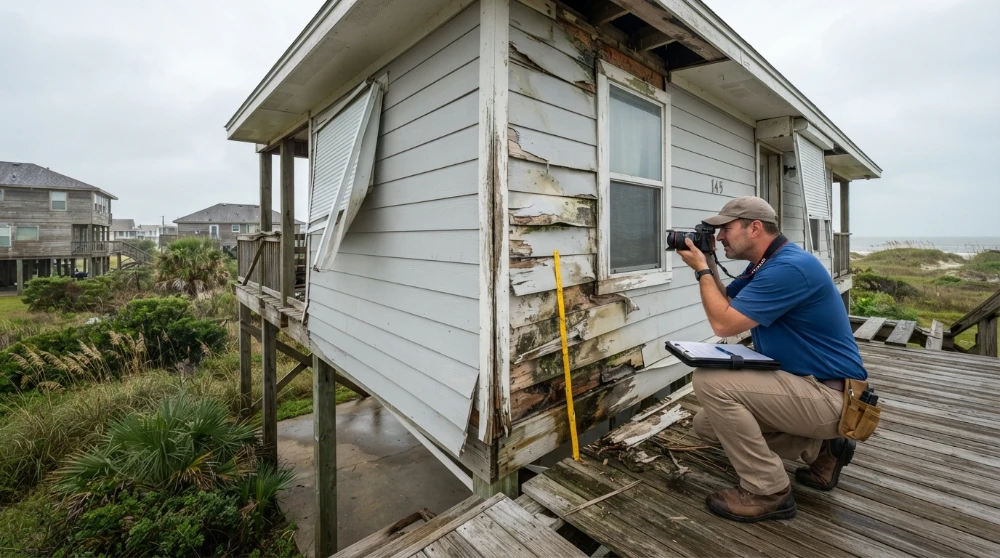
| Claim Type | Damage We Commonly Review |
| Hurricane & Wind | Roofing, siding, windows, doors, exterior systems, wind-driven rain |
| Roof Damage | Shingles, metal roofing, flashing, penetrations, underlayment, commercial roofing |
| Water Damage | Ceilings, drywall, insulation, flooring, cabinets, contents |
| Hail Damage | Roofing, soft metals, HVAC equipment, gutters, exterior finishes |
| Fire & Smoke | Structural damage, contents, smoke residue, odor, cleanup |
| Commercial Claims | Roof systems, interiors, equipment, tenant areas, business property |
| Storm Damage | Debris impact, exterior openings, fences, detached structures |
Hail Damage Claims
A Quintana hail claim may involve more than bruised shingles. Metal roofs, HVAC fins, roof vents, flashing, gutters, fencing, siding, and other exterior components can all be affected.
When reviewing a hail claim, we look at the entire loss rather than one isolated roof surface.
Water Damage Claims
Water losses can result from plumbing failures, appliance leaks, roof openings, wind-driven rain, or other covered causes. When the scope becomes disputed, a water damage public adjuster can review the carrier’s estimate against the documented conditions at the property.
The source matters.
A proper water damage claim may require documentation of moisture migration, demolition requirements, insulation, drywall, flooring, cabinetry, paint, trim, contents, and mitigation work. The question is not simply where the water ended up—it is what caused the loss and what must be repaired to restore the property.
Fire Damage Claims
Fire claims often involve several overlapping categories: direct fire damage, smoke, soot, odor, water from firefighting, damaged contents, demolition, electrical components, and temporary living or operating expenses where coverage applies. A fire insurance adjuster representing the policyholder can help organize these different portions of the loss.
TX Public Adjusting reviews the claim scope and supporting documentation to determine whether important items have been omitted.
Storm Damage Claims
For Quintana property owners, storm claims may involve a combination of roof, exterior, interior, wind, and rain damage.
That is particularly relevant near Quintana Beach, the jetty, and the ship channel, where Gulf winds can have a direct path toward buildings.
Roof Damage Claims
Roof claims are one of the most common reasons policyholders contact us. A public adjuster for a roof claim can review whether the carrier’s estimate accounts for the documented roofing damage, related components, and resulting interior damage. There may also be disagreement about matching, damaged accessories, flashing, underlayment, code-related items, commercial roof assemblies, or interior damage caused by a roof opening.
We review the estimate against the physical conditions and available policy information.
Commercial Property Claims
Quintana and the surrounding Brazosport area include residential, recreational, maritime, industrial, lodging, and business properties.
Commercial losses can involve:
- Flat or low-slope roofing
- Metal roof systems
- Building envelope damage
- Mechanical equipment
- Interior build-outs
- Inventory or contents
- Tenant improvements
- Water mitigation
- Business-related property damage
Commercial claims often require a more detailed scope because several building systems may be affected at once. Property owners facing a larger business loss can learn more about how we handle commercial property claims throughout Texas.
Why Insurance Claims Become Underpaid
A claim can be underpaid even when the insurance company has inspected the property and issued an estimate.
Missed Damage
An inspection may focus on one obvious area while overlooking other affected elevations, roof components, interior rooms, mechanical systems, or related repairs.
Scope Omissions
An estimate may include the damaged material but omit work required to remove, access, replace, detach, reset, protect, or finish surrounding components.
Depreciation Issues
Depreciation can materially affect the initial payment. Policyholders should understand how depreciation was calculated and whether recoverable depreciation may be available after qualifying repairs are completed.
Low Estimates
Pricing, quantities, labor assumptions, waste, material selection, or repair methodology can differ from what is actually needed to restore the property.
Documentation Problems
Insurance claims are evidence-driven.
If photographs are incomplete, damage is discarded before documentation, repair estimates lack detail, or the cause of loss is not clearly supported, the carrier may have less information available when evaluating the claim.
That is why property owners should preserve records, photographs, contractor documents, invoices, communications, and damaged materials whenever practical.
Our Public Adjusting Process
1. Claim Review
We start by reviewing the insurance claim, available policy documents, carrier correspondence, estimates, photographs, and the property’s loss history relevant to the claim.
We look for questions that need answers before the claim moves forward.
2. Property Inspection
We inspect the affected property and identify visible damage related to the reported event.
For a coastal property in Quintana, that may include roofing, exterior elevations, windows, doors, interior finishes, water intrusion, detached structures, and commercial building systems.
3. Documentation and Scope
We organize photographs, measurements, estimates, inventories, invoices, reports, and other supporting information.
The objective is to present a clear scope showing what was damaged and what is reasonably required to repair or replace it, subject to the policy.
4. Insurance Company Communication and Negotiation
We communicate with the insurance company regarding the documented claim and address differences between the carrier’s scope and our findings.
This can include omitted damage, measurements, repair methodology, pricing, documentation requests, or supplemental items.
5. Settlement Review
We review the carrier’s position and settlement documents to help the policyholder understand what has been included, what remains disputed, and what steps may still be available.
Every claim is different, and no public adjuster can guarantee a particular settlement.
A Closer Look at Quintana Property Claims
Quintana is small enough that it does not have the conventional collection of named residential neighborhoods found in Houston, Dallas, or Austin. Local property references are better understood by geography: the residential streets around Quintana Beach, properties approaching the Quintana Jetty and Freeport Harbor channel, the CR 723/F.M. 1495 access area, and nearby coastal properties toward Freeport and Surfside Beach.
That difference matters when creating a local claim strategy.
The east end of Quintana Beach reaches the jetty forming the west side of the Freeport ship channel, while the west end includes the fishing-pier area. Brazoria County also notes the historic Fort Bates site and World War II harbor-defense remains within Quintana Beach County Park.
The town’s Neotropical Bird Sanctuary adds another distinctive local reference point and reflects the wetlands and migratory habitat surrounding this part of the coast.
Properties in this setting should not be evaluated as though they were miles inland. Wind direction, coastal exposure, roof design, building orientation, elevation, maintenance condition, flood source, and the path of water intrusion can all matter when investigating a loss.
Why Choose TX Public Adjusting
Licensed Texas Public Adjuster
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839.
We Represent Policyholders
A public adjuster works for the person or business making the claim—not for the insurance company.
Our job is to document and present the policyholder’s claim.
Texas-Focused Experience
Texas claims can involve hail, hurricanes, tornadoes, severe thunderstorms, frozen pipes, wind, fire, water, and commercial property losses.
Our team has reviewed thousands of claims and brings experience with both residential and commercial losses.
Residential and Commercial Claim Experience
We assist:
- Homeowners
- Rental-property owners
- Commercial building owners
- Business owners
- Multifamily properties
- Retail properties
- Warehouses
- Restaurants
- Offices
- Other insured Texas properties
Detailed Claim Documentation
We focus on the actual scope of damage.
That includes inspecting the loss, documenting the property, reviewing estimates and policy information, and identifying differences that should be addressed with the carrier.
Claim underpaid, delayed, or more complicated than expected? Contact TX Public Adjusting for a Free Claim Review.
Areas We Serve Near Quintana
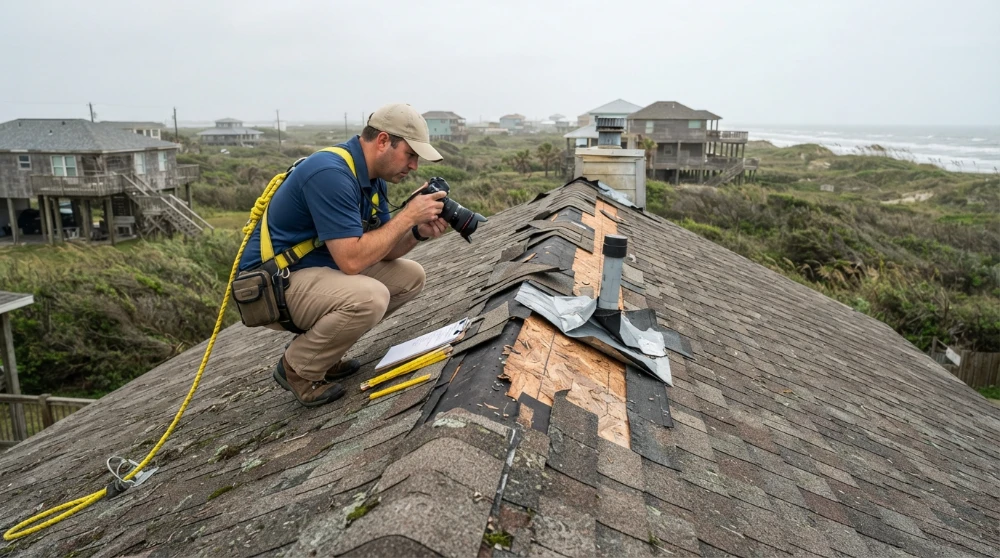
TX Public Adjusting assists property owners throughout Brazoria County and the surrounding Texas Gulf Coast area.
Communities near Quintana include:
- Freeport
- Surfside Beach
- Clute
- Lake Jackson
- Oyster Creek
- Jones Creek
- Richwood
- Brazoria
- Angleton
- Other Brazoria County communities
Because Quintana sits immediately beside the Brazosport communities, we also assist property owners who need a public adjuster in Freeport or a public adjuster in Clute.
If a storm damages multiple properties across coastal Brazoria County, we can review residential and commercial claims throughout the surrounding area.
Frequently Asked Questions About Public Adjusters in Quintana
What does a public adjuster in Quintana do?
A public adjuster represents the property owner during an insurance claim. That can include reviewing the policy, inspecting damage, documenting the loss, preparing a repair scope, analyzing the carrier’s estimate, communicating with the insurer, and negotiating disputed claim items.
TX Public Adjusting represents policyholders rather than insurance companies.
Why can Quintana insurance claims be more complicated than inland claims?
Quintana sits directly on the Gulf Coast beside Freeport Harbor. A major storm can produce wind damage, wind-driven rain, flooding, surge, roof damage, and interior water intrusion during the same event.
Different causes of damage can be treated differently under an insurance policy. Carefully documenting what caused each portion of the loss can therefore be especially important for a Quintana property.
Can you help with hurricane claims in Quintana?
Yes. We review hurricane and tropical-storm property claims involving wind, roofing, exterior damage, interior water intrusion, damaged openings, debris impact, and other potentially covered losses.
Coverage depends on the policy. Flood and storm-surge damage may require separate flood coverage, so we do not assume every form of hurricane-related water damage falls under the same policy.
What if my insurance company says the damage is from flooding rather than wind?
Cause-of-loss disputes can become significant after a coastal storm.
We review the physical damage, available photographs, weather information, timeline, inspection findings, and policy documents to help determine how the claim should be presented. Where specialized engineering, legal, or other expert analysis is required, that work may need to be performed by the appropriate qualified professional.
Can a public adjuster help with an underpaid roof claim?
Yes. Roof claims can become underpaid when the scope omits damaged components, quantities, flashing, accessories, interior damage, or necessary repair operations.
We compare the carrier’s estimate with documented property conditions and identify differences that may need to be addressed.
Should I hire a public adjuster before or after the insurance company inspects?
A public adjuster can be hired at different stages of a claim.
Some Quintana property owners contact us shortly after a major loss so documentation begins early. Others contact us after receiving a low estimate, denial, or settlement they believe does not reflect the damage. Earlier involvement can make documentation easier, but an existing claim may still be reviewable. If your claim has already been open for some time, read our guide explaining when it is too late to hire a public adjuster.
Can you reopen or review an older Quintana insurance claim?
Possibly.
The answer depends on the policy, the date of loss, claim status, applicable deadlines, prior payments, releases, repairs already completed, and Texas law. If an older Quintana claim appears underpaid, we can review the available documentation and explain whether further action may be worth considering.
Do I need a public adjuster for a small claim?
Not necessarily.
A straightforward claim with limited damage, clear coverage, and an adequate carrier estimate may not justify hiring a public adjuster. Public adjusting is generally most useful when the loss is substantial, technically complicated, underpaid, disputed, or difficult for the property owner to manage.
We offer a Free Claim Review so you can understand whether professional claim assistance makes sense before making a decision.
Do you handle commercial claims around Quintana and Freeport?
Yes. We handle commercial property claims involving storm damage, roofing systems, water intrusion, fire, equipment, interiors, and other insured property losses.
This can be especially relevant in the Quintana-Freeport area, where commercial and industrial buildings may have large metal, membrane, or low-slope roofing systems that require detailed inspection and estimating.
How much does it cost to have TX Public Adjusting review my Quintana claim?
The initial claim review is free, with no upfront fee for that review.
If you decide to hire TX Public Adjusting, the agreement will explain the applicable public-adjusting fee and terms before representation begins. We want property owners to understand the arrangement before moving forward.
Get Insurance Claim Help in Quintana, TX
A coastal insurance claim should be documented with the same care as the property itself.
If your Quintana home, rental, business, or commercial property has suffered hurricane, wind, hail, roof, water, fire, or other covered property damage, TX Public Adjusting can review the claim and help determine whether the insurance estimate reflects the full documented scope.
We work for policyholders—not insurance companies.
TX Public Adjusting
Rise Public Adjusting LLC
Texas License #3356839
Request your Free Claim Review today. There is no upfront fee for the review. Contact TX Public Adjusting for insurance claim assistance in Quintana, Texas.