

Property damage in New Ulm can become complicated quickly. A severe thunderstorm can damage a metal roof, shingles, barns, exterior siding, fencing, or outbuildings in a matter of minutes. Heavy rain can enter through storm-created openings. A fire or plumbing loss can affect both the structure and personal property. And when the insurance company’s estimate leaves out part of the damage, the property owner is left trying to determine what was missed.
TX Public Adjusting provides public adjuster services in New Ulm, Texas, for homeowners, landowners, business owners, and other policyholders dealing with residential and commercial property insurance claims.
We represent the policyholder—not the insurance company.
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839. Our team reviews property damage, examines carrier estimates, documents the scope of loss, prepares claim support, and negotiates insurance claims on behalf of Texas property owners.
Need insurance claim help in New Ulm? Request a Free Claim Review. There are no upfront fees to have us evaluate whether your claim may need a closer look.
Why Property Owners Hire a Public Adjuster in New Ulm
New Ulm is different from a dense Houston or Austin neighborhood. Properties around this part of western Austin County can include traditional single-family residences, older homes, newer rural residences, acreage properties, metal buildings, barns, workshops, agricultural improvements, and locally operated commercial properties.
The community sits at the intersection of FM 109 and FM 1094 in western Austin County. Historically, New Ulm developed as an agricultural community and became closely associated with the German settlements that formed throughout this part of Texas.
Those property characteristics can make an insurance claim more detailed than it first appears.
A roof claim, for example, may involve more than roofing material. A storm can also affect:
- Ridge caps and flashing
- Gutters and downspouts
- Roof vents
- Metal trim
- Window screens
- Exterior paint and siding
- Detached garages
- Shops and barns
- Fences and gates
- Interior ceilings or walls after water intrusion
If the insurer’s initial inspection concentrates on only one portion of the loss, legitimate damage elsewhere on the property can be omitted from the estimate.
A public insurance adjuster in New Ulm reviews the claim from the policyholder’s side. Our job is to identify and document covered damage and present the claim as thoroughly as the policy and facts support.
When a Second Look at the Claim Makes Sense
Property owners commonly contact TX Public Adjusting when:
- The insurance payment seems too low for the repairs required
- The carrier says the roof can be repaired when contractors identify broader damage
- Important structures or exterior components were omitted
- Interior damage was not connected to the storm loss
- The insurer applied depreciation that the owner does not understand
- Multiple estimates differ significantly
- A claim has been partially denied
- The claim involves both residential and detached structures
- A commercial loss is interfering with operations
- The owner does not have time to manage documentation and repeated carrier communication
You do not necessarily need to wait until a claim becomes a dispute. Bringing in a public adjuster earlier can help create a clearer record of the loss from the start.
Property Damage Risks in New Ulm, Texas
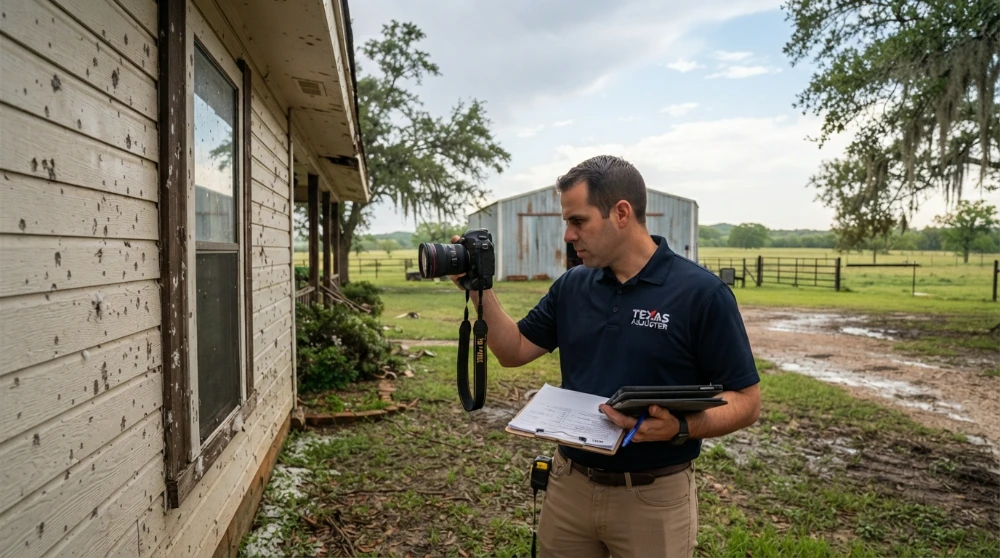
New Ulm’s location in southeast-central Texas exposes property owners to a combination of Gulf moisture, strong thunderstorms, hail, straight-line winds, heavy rainfall, and occasional tropical-system impacts that move inland.
That mix produces several recurring insurance claim situations.
Severe Thunderstorms and Wind Damage
Strong thunderstorms can move across Austin County with damaging winds capable of lifting roofing materials, breaking tree limbs, damaging metal panels, and creating openings that allow rain into the structure.
On rural properties, the loss may extend well beyond the main residence. Workshops, barns, equipment buildings, detached garages, fences, and other insured structures may also need to be inspected.
Wind damage can be subtle. Shingles do not always disappear completely. They may crease, lift, lose their seal, or suffer damage around edges and flashing.
A complete New Ulm storm claim should therefore consider both obvious and less visible damage.
Hail Damage in New Ulm
Hail is especially important because roof damage is not always obvious from the ground.
Depending on the construction, hail can affect:
- Asphalt shingles
- Standing-seam or exposed-fastener metal roofs
- Gutters
- Downspouts
- Roof vents
- Flashing
- Window screens
- Exterior light fixtures
- HVAC fins
- Painted surfaces
- Siding
- Fences and accessory structures
Texas hailstorms can damage shingles, metal roofing, gutters, vents, siding, and other exterior components. Property owners dealing with a hail damage roof insurance claim should document more than the obvious roof impacts because related exterior damage may also affect the overall scope of the loss.
If your insurer inspected after a New Ulm hailstorm but the repair estimate does not appear to account for the complete property, we can review the scope and documentation.
Heavy Rain and Water Intrusion
Thunderstorms do not need to produce catastrophic flooding to create a serious property claim.
Wind-driven rain can enter through damaged roofing, flashing, windows, doors, or exterior building components. Plumbing failures and appliance leaks can also create significant interior losses.
Once water enters a building, damage may extend to:
- Insulation
- Drywall
- Paint
- Flooring
- Cabinets
- Trim
- Electrical components
- Contents
One of the most important questions in a water claim is what caused the water to enter. Coverage can depend heavily on the cause of loss and policy language.
Hurricane and Tropical Storm Effects
New Ulm is inland from the Texas Gulf Coast, but inland communities are not immune to tropical weather.
Large Gulf systems can carry heavy rain and strong winds well beyond coastal counties. Understanding the different types of property damage after a hurricane can help inland property owners recognize roof, exterior, structural, and water-related damage that may not be immediately obvious.
By the time a storm reaches Austin County, conditions may still be capable of damaging roofs, trees, exterior structures, and building envelopes.
For New Ulm property owners, that means tropical-system claims may involve a combination of wind damage and resulting water intrusion rather than direct coastal storm-surge damage.
Fire and Smoke Damage
Fire insurance claims often require considerably more documentation than the visible burn area suggests.
A fire can generate claims involving:
- Structural components
- Smoke contamination
- Soot
- Odor
- Water used during firefighting
- Electrical systems
- HVAC contamination
- Personal property
- Debris removal
- Temporary living expenses when applicable
For rural residences and commercial properties around New Ulm, detached buildings and contents stored in those structures may create additional claim questions.
Common Insurance Claims in New Ulm
TX Public Adjusting assists New Ulm policyholders with a wide range of property damage claims.
| Claim Type | Damage We Commonly Review |
| Hail Damage | Shingles, metal roofing, gutters, vents, siding, windows and exterior components |
| Wind & Storm Damage | Roofing, flashing, fascia, trees, fences, detached structures and rain intrusion |
| Water Damage | Drywall, flooring, cabinets, insulation, ceilings and contents |
| Fire Damage | Structure, smoke, soot, contents, debris and related water damage |
| Roof Claims | Missing or damaged materials, accessories, flashing and related interior losses |
| Commercial Claims | Buildings, roofing systems, contents and property-related business losses where covered |
Hail Damage Claims
A carrier inspection following hail may identify some damage while overlooking related components.
The resulting estimate should be reviewed against what is physically present at the property. Roof accessories, gutter systems, elevations, detached structures, and other damaged components can materially affect the repair scope.
Water Damage Claims
Water losses can become expensive because damage frequently extends behind visible finishes. A water damage public adjuster can review the reported cause of loss, affected building materials, mitigation documentation, and the insurance company’s estimate when the scope appears incomplete.
We review the reported cause, carrier estimate, mitigation documentation, affected rooms, building materials, and other available evidence to determine whether the claim scope reflects the documented loss.
Fire Damage Claims
Fire losses are rarely limited to the room where flames were visible. Smoke can travel throughout a building, and firefighting activities can create secondary water damage. For larger losses, a fire insurance adjuster working for the policyholder can help document structural damage, smoke, soot, contents, debris removal, and related claim expenses.
Thorough documentation becomes especially important when structure, contents, debris removal, and temporary-use issues overlap.
Storm Damage Claims
A single severe storm may cause several forms of loss simultaneously.
A New Ulm property might have roof damage, fallen-tree impact, a damaged fence, water intrusion, and harm to a detached building from the same event. We look at the complete property rather than treating each visible symptom in isolation.
Roof Damage Claims
Roof disputes are among the most common reasons property owners ask for another opinion. Hiring a public adjuster for a roof claim may be appropriate when the carrier’s estimate calls for limited repairs but the documented storm damage appears broader or important roofing components have been omitted.
An insurance estimate may call for a repair while a contractor identifies damage across a larger portion of the roof. There can also be disagreement over flashing, vents, underlayment, edge components, metal accessories, or interior damage connected with the roof opening.
TX Public Adjusting reviews the physical damage, documentation, estimates, and applicable policy provisions when evaluating a roof claim.
Commercial Property Claims
New Ulm and the surrounding Austin County area include locally operated businesses, agricultural facilities, workshops, event properties, and other commercial buildings.
Commercial claims can require additional attention because a loss may involve larger roofing systems, specialized equipment, inventory, tenant spaces, or operational concerns.
TX Public Adjusting handles both residential and commercial property claims. A business owner dealing with a large storm, fire, water, or roof loss can learn more about working with a commercial public adjuster for Texas business property claims.
Why New Ulm Insurance Claims Become Underpaid
An insurance claim can be underpaid without every part of the carrier’s estimate being wrong.
Often the problem is that the estimate is incomplete.
Missed Damage
An inspection may focus heavily on the primary structure while failing to document damaged gutters, fencing, a detached garage, metal buildings, or other insured property.
On acreage and rural properties around New Ulm, that distinction can matter.
Scope Omissions
Even when the insurer recognizes a damaged roof, its estimate may leave out work required to complete the repair correctly.
Common disagreements can involve:
- Flashing
- Ventilation components
- Roofing accessories
- Removal and disposal
- Interior repairs
- Exterior finishes
- Detached structures
- Matching or adjacent damaged materials
Depreciation Issues
Property estimates frequently include depreciation.
Policyholders may receive an initial payment that appears substantially lower than the estimated replacement cost without understanding what was withheld, why it was withheld, or what requirements apply before recoverable depreciation may be released.
We help owners understand how the carrier calculated the claim.
Low or Incomplete Estimates
Construction costs involve labor, materials, access, quantities, disposal, and the specific design of the property.
If the carrier’s estimate does not reflect the work actually required, the claim may need additional documentation and an updated scope.
Documentation Problems
A claim is easier to evaluate when the file contains clear evidence.
Useful documentation can include:
- Photographs
- Measurements
- Repair estimates
- Contractor findings
- Damage inventories
- Receipts
- Mitigation records
- Prior carrier correspondence
- The insurer’s estimate
Our role is to organize the available information into a claim presentation that clearly explains the documented loss.
Our Public Adjusting Process
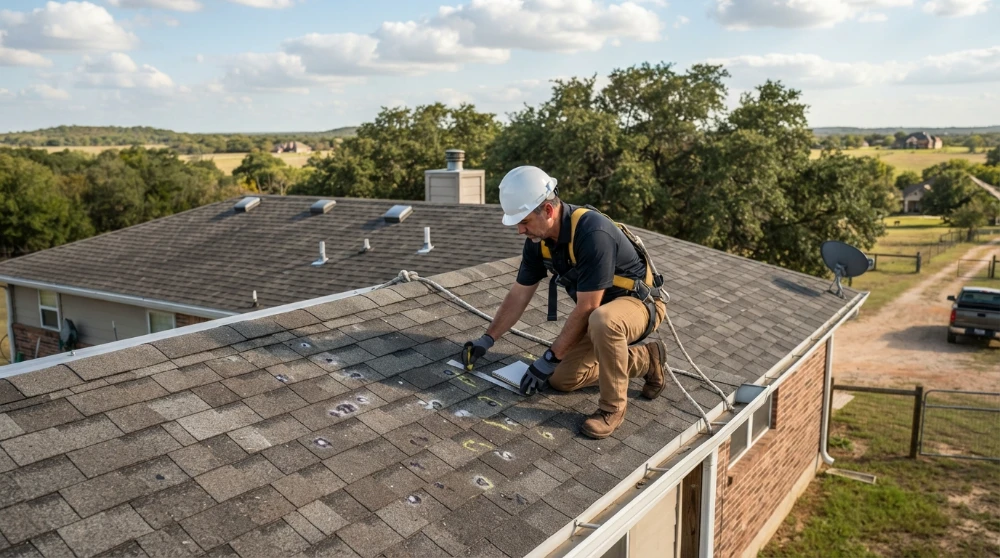
Every claim has its own facts, but our work generally follows five stages.
1. Claim Review
We begin by discussing the loss and reviewing the available claim information.
That may include the insurance estimate, coverage correspondence, photographs, contractor documentation, payment information, and relevant policy provisions.
2. Property Inspection
When representation is appropriate, the damage is inspected and documented.
For a New Ulm property, that inspection may include the main residence or commercial structure along with insured garages, shops, roofing systems, exterior components, and other affected areas.
3. Documentation and Scope Preparation
We organize the damage into a detailed claim file.
The goal is not to inflate a claim. It is to make sure legitimate covered damage is identified, measured, supported, and communicated.
4. Insurance Company Communication and Negotiation
TX Public Adjusting communicates with the insurance carrier concerning the property claim and presents supporting documentation when the carrier’s scope needs to be addressed.
We represent the policyholder throughout that process.
5. Claim Resolution
We continue working through the claim toward the settlement supported by the policy, documentation, and verified damage.
Every insurance claim is different, so no ethical public adjuster can guarantee a particular payment. What we can provide is professional claim preparation and policyholder-focused representation.
Already received a low estimate? TX Public Adjusting can review your New Ulm property claim before you simply accept the carrier’s numbers. Request a Free Claim Review.
Why Choose TX Public Adjusting for a New Ulm Claim?
TX Public Adjusting is focused on Texas property claims.
Our team has experience reviewing thousands of claim files involving residential and commercial losses. We understand that rural and small-community claims can involve different property layouts and structures than a typical subdivision home.
Licensed Texas Public Adjuster
TX Public Adjusting operates through:
Rise Public Adjusting LLC
Texas License #3356839
We Represent Policyholders
The insurance company’s adjuster works within the carrier’s claim process, while a public adjuster represents the insured property owner. Understanding the difference between a public adjuster vs. independent adjuster can help property owners understand who each professional represents during an insurance claim.
Our responsibility is to prepare, document, and present the policyholder’s claim—not to protect the insurance carrier’s financial interests.
Residential and Commercial Experience
We assist with claims involving homes, rental property, businesses, commercial buildings, roofing systems, detached structures, and other insured property.
Texas-Focused Property Claim Experience
Texas weather is demanding on buildings.
From hail and severe thunderstorms to hurricane remnants, water losses, freezes, and fire damage, our work is centered on property claim situations Texas owners regularly face.
Detailed Claim Documentation
The quality of a claim often depends on the quality of its documentation.
We focus heavily on inspection records, photographs, scope details, estimates, policy information, and communication with the carrier.
New Ulm: A Rural Austin County Community
New Ulm is not divided into large named subdivisions in the same way as Houston, Dallas, or Austin. Local relevance here is better understood through roads, nearby historic communities, farms, acreage, and the broader western Austin County area.
New Ulm sits around FM 109 and FM 1094, about 22 miles southwest of Bellville and approximately 16 miles northeast of Columbus.
The community was once known as Duff’s Settlement and later took the name New Ulm as German-speaking settlers moved into the surrounding area. Agriculture became central to the local economy, with cotton, poultry, eggs, and butter historically shipped from the community.
That history still matters when considering today’s property stock. The area includes residences and improvements spread over larger parcels where damage to a secondary building can be easy to overlook during a short inspection.
Local New Ulm Reference Points
Recognizable local reference points include:
- The FM 109 and FM 1094 crossroads
- New Ulm’s historic community center
- New Ulm Lions Club Community Service Building
- The wider rural corridor toward Industry, Frelsburg, Bellville, and Columbus
Austin County records describe New Ulm and neighboring Industry, Cat Spring, Nelsonville, and other nearby settlements as communities with roots extending to some of the earliest German settlement in the county.
Areas We Serve Near New Ulm
TX Public Adjusting assists property owners in New Ulm and throughout surrounding parts of Austin County and the neighboring region, including:
- Industry
- Shelby
- Frelsburg
- Bellville
- Cat Spring
- Columbus
- Sealy
- Fayetteville
- Alleyton
- Bernardo
If your property lies outside the New Ulm ZIP code, contact us. TX Public Adjusting serves policyholders throughout Texas.
Frequently Asked Questions About Public Adjusters in New Ulm
1. What does a public adjuster do for a New Ulm property owner?
A public adjuster represents you, the policyholder, during a property insurance claim. We can inspect and document damage, review the insurer’s estimate, prepare a detailed scope, organize supporting records, and communicate with the insurance carrier.
That can be especially useful around New Ulm when a loss involves multiple structures such as a residence, detached garage, barn, workshop, fencing, or other insured improvements.
2. When should I hire a public adjuster in New Ulm?
You can contact a public adjuster soon after a significant property loss or later if your carrier has issued a payment that does not appear to cover the documented damage. If your claim has already been open for some time, our guide explaining when it is too late to hire a public adjuster covers several timing considerations for property owners.
Many property owners reach out after seeing a large difference between the insurer’s scope and a contractor’s assessment. Earlier involvement can also make documentation easier because conditions have not yet changed through repairs or additional weather exposure.
3. Can TX Public Adjusting help with an underpaid hail claim?
Yes. We review hail claims involving roofing, gutters, exterior components, metal surfaces, detached buildings, and related property damage.
We compare the carrier’s scope with available evidence from the property to identify items that may require additional documentation.
4. Can you review damage to barns or detached buildings?
Potentially, yes, when the structure is insured and the loss falls within the applicable policy coverage.
This is particularly relevant in the New Ulm area because many properties include more than one building. We review the policy and claim information to determine which damaged structures are part of the insured loss.
5. Do you handle New Ulm commercial insurance claims?
Yes. TX Public Adjusting handles commercial as well as residential property claims.
Commercial losses may involve roofing systems, building exteriors, interiors, equipment, inventory, tenant improvements, or other insured property. We tailor the documentation to the nature of the business and the policy.
6. Can you help after my insurance company has already inspected the property?
Yes. An initial carrier inspection does not necessarily mean every legitimate issue has been fully documented.
We can review the carrier’s estimate and the current condition of the property to identify differences in scope, quantities, or documented damage.
7. What if my New Ulm roof claim was partially denied?
A partial denial deserves a careful review.
We look at the carrier’s explanation, available policy language, inspection evidence, photographs, estimates, and other supporting information. Depending on the circumstances, additional documentation may help clarify portions of the claim that remain disputed.
8. How much does a public adjuster cost in Texas?
Public adjusters commonly work under a contingency-based fee arrangement rather than charging the property owner a large upfront adjusting fee.
The exact fee and terms of representation should always be disclosed in the written agreement before work begins. TX Public Adjusting offers a Free Claim Review so you can first determine whether professional claim assistance makes sense for your situation.
9. Does TX Public Adjusting work for my insurance company?
No.
TX Public Adjusting represents policyholders. That distinction is fundamental to what a public adjuster does. We prepare and advocate for your property claim based on the policy, documented damage, and supporting evidence.
10. What information should I have ready for a free New Ulm claim review?
Bring whatever you already have. You do not need a perfectly organized file before contacting us.
Helpful materials can include the carrier’s estimate, claim number, insurance correspondence, photographs, repair estimates, contractor reports, proof of payments, and a copy of your policy if available. We can review what you have and explain what additional information may be useful.
Get Insurance Claim Help in New Ulm, Texas
If your New Ulm home, acreage property, business, roof, or other insured building has been damaged, you do not have to evaluate the insurance company’s estimate alone.
TX Public Adjusting can review the claim, inspect the documented loss, identify scope issues, and represent you during the claim process.
TX Public Adjusting
Rise Public Adjusting LLC
Texas License #3356839
Licensed Texas Public Adjuster
Residential & Commercial Claims
Free Claim Review
No upfront fees for the initial claim review
Contact TX Public Adjusting today and request your Free Claim Review.