

Property damage in Kemah can become complicated quickly. This small Galveston County waterfront city sits beside Clear Lake and Galveston Bay, which means homes, restaurants, retail properties, marinas, offices, and other buildings can face hurricane-force winds, wind-driven rain, storm surge, flooding, roof damage, and water intrusion. If an insurance company’s estimate does not reflect the full extent of your loss, a public adjuster in Kemah can help you document the damage and present your claim from the policyholder’s side.
TX Public Adjusting provides insurance claim assistance to residential and commercial property owners throughout Kemah and the surrounding Texas Gulf Coast. We are operated by Rise Public Adjusting LLC, Texas License #3356839, and our role is different from the insurance carrier’s adjuster: we represent the policyholder.
If your Kemah property has been damaged, your claim was underpaid, or you are unsure whether important damage was left out of an insurance estimate, contact TX Public Adjusting for a Free Claim Review. There are no upfront fees for the initial review.
Licensed Texas Public Adjuster | Residential & Commercial Claims | Free Claim Review
Why Property Owners Hire a Public Adjuster in Kemah
Insurance claims along the Texas Gulf Coast often involve more than one type of damage. A tropical system can damage roofing with high winds, drive rain through openings in the building envelope, damage exterior components, interrupt business operations, and allow moisture to spread inside a structure.
Kemah presents its own claim challenges because of its waterfront environment. The City of Kemah identifies seven distinct local precincts: Lighthouse District, Old Kemah, West Kemah, Bayview, Kemah Oaks, South Kemah, and Kemah Crossing. Properties range from established single-family homes to waterfront structures and commercial buildings serving visitors around the Boardwalk and Highway 146 corridor.
A public insurance adjuster in Kemah may be brought into a claim when:
- The insurance estimate appears too low.
- Roof damage was partially documented or overlooked.
- Interior water damage extends beyond the rooms included in the estimate.
- The carrier attributes damage to wear and tear rather than the reported storm.
- Exterior components were omitted from the scope.
- Depreciation or replacement-cost calculations are unclear.
- A commercial loss involves equipment, inventory, contents, or business-related damage.
- The property owner is overwhelmed by inspections, estimates, documentation, and carrier communication.
- A previously paid claim appears incomplete or underpaid.
TX Public Adjusting reviews the loss from the property owner’s perspective. We examine available policy information, inspect the property, document covered damage, develop an appropriate scope, and communicate with the insurance company during the claim process.
Kemah Claims Require Gulf Coast Experience
Kemah is not an inland Texas market where hail is the only significant weather concern. Its location near Galveston Bay creates exposure to tropical storms, hurricanes, storm surge, heavy rainfall, and damaging winds.
The City of Kemah specifically warns that all areas of the city have some flood risk because of the city’s Gulf Coast location and proximity to Galveston Bay. The city notes that flooding can result from storm surge or heavy rainfall overwhelming drainage systems.
Texas Department of Insurance wind-zone information also places Kemah within Galveston County’s Inland I windstorm area, further demonstrating the importance of wind-related building considerations in this part of the coast.
Those conditions can create complicated losses where determining the cause, extent, timing, and appropriate repair scope matters.
Common Insurance Claims in Kemah
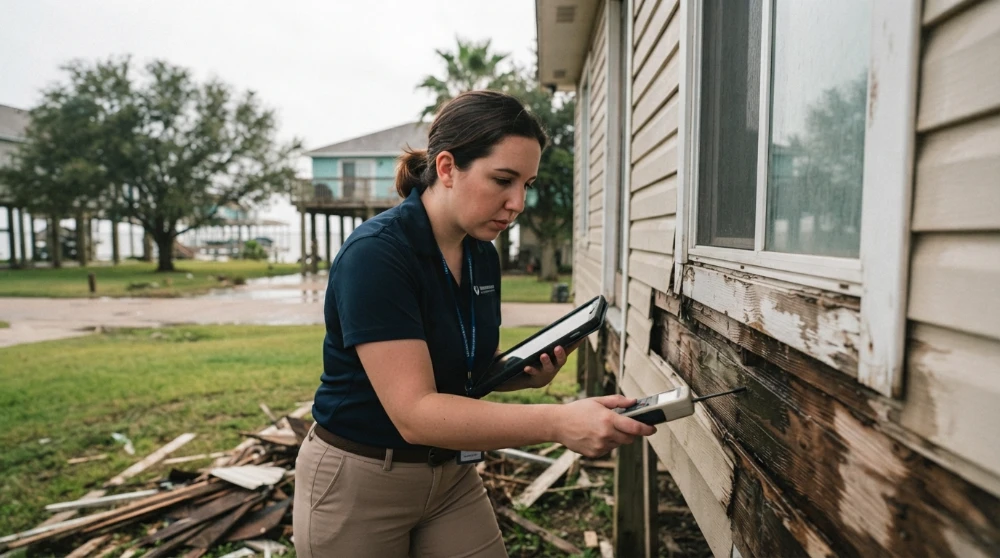
Property claims in Kemah range from isolated plumbing losses to major hurricane and commercial storm losses. Some claims involve a single damaged component. Others affect the roof, exterior, interior finishes, electrical systems, mechanical equipment, contents, and business operations at the same time.
Hail Damage Claims
Kemah is best known for Gulf Coast wind and hurricane exposure, but severe thunderstorms can also produce hail.
Hail may damage:
- Asphalt shingles
- Metal roofing
- Roof vents and flashing
- Gutters and downspouts
- HVAC equipment
- Siding
- Window screens
- Fencing and exterior finishes
Hail damage is not always obvious from ground level. A roof may appear intact while shingles, membranes, metal surfaces, accessories, or rooftop equipment show impact damage after a professional inspection. Property owners can also review our hail damage insurance claim guide for more information about documenting storm-related hail damage.
A Kemah public adjuster can compare the physical evidence with the insurance company’s scope and determine whether potentially covered components were excluded.
Water Damage Claims
Water claims are especially important in a waterfront community.
Water claims are especially important in a waterfront community. Kemah properties can experience water damage from plumbing failures, roof leaks following storms, broken supply lines, wind-driven rain, damaged windows or doors, appliance leaks, and other covered events. A water damage public adjuster can help review the affected areas, existing carrier scope, and documentation when the extent of the loss is disputed.
Water can travel behind walls, beneath flooring, through insulation, and into adjacent rooms. The visible stain on a ceiling may represent only a small portion of the actual affected area.
Insurance documentation should identify not only where water appeared, but also the building materials and property affected by the event.
For Gulf Coast property owners, it is also important to distinguish between water entering because of a covered building opening and rising surface water or storm surge. Standard property policies and flood policies may respond differently depending on the cause of loss. The City of Kemah notes that standard homeowners policies generally do not cover flooding, which is one reason property owners should understand exactly what caused the damage before assuming how coverage applies.
Fire Damage Claims
Fire insurance claims can involve far more than burned building materials.
A serious loss may include:
- Structural fire damage
- Smoke contamination
- Soot
- Water from firefighting efforts
- Damaged electrical components
- HVAC contamination
- Personal property
- Demolition and debris removal
- Temporary repairs
- Loss of use
- Commercial equipment and inventory
Smoke and soot may spread into rooms that were never directly touched by flames. For businesses around Kemah’s commercial corridors, a fire can also disrupt operations while repairs are being completed.
TX Public Adjusting helps policyholders organize and document these interconnected portions of the loss rather than treating the fire as simply a list of visibly burned materials. For a deeper explanation of how these losses are evaluated, see our guide to working with a fire insurance adjuster after a property loss.
Storm Damage Claims
Kemah’s coastal location makes storm claims one of the most important categories for local property owners.
The Atlantic hurricane season runs from June 1 through November 30, and the City of Kemah maintains specific emergency and hurricane-preparation resources because of its exposure.
A major storm may create:
- Wind damage
- Missing or lifted shingles
- Roof membrane damage
- Broken exterior components
- Wind-driven rain
- Window and door damage
- Interior moisture
- Ceiling and drywall damage
- Electrical damage
- Damage from falling branches or debris
- Commercial equipment damage
For a more detailed breakdown of the issues that can develop after a tropical system, read our guide to property damage after a hurricane, including roof, interior, structural, water, equipment, and debris-related losses. Hurricane Harvey and Hurricane Ike are among the historic events specifically referenced in Kemah’s flood-preparedness materials.
For a coastal claim, documenting how water entered the property can be particularly important because wind-related water intrusion and flood-related damage may involve different policy provisions.
Roof Damage Claims
A roof claim is rarely just about shingles.
A roof claim is rarely just about shingles. When evaluating whether a public adjuster for a roof claim may be helpful, the entire roofing assembly and related exterior damage should be considered—not only the most obvious damaged shingles.
- Shingles or roofing membrane
- Underlayment
- Flashing
- Ridge and hip components
- Vents
- Pipe boots
- Metal accessories
- Gutters
- Fascia
- Decking when affected
- Code-related requirements when applicable
Kemah’s salt-air environment, severe storms, strong winds, and tropical weather can also make roof-condition disputes more complicated. Insurers may question whether damage resulted from a recent event or pre-existing deterioration.
Detailed photographs, inspection findings, weather information, construction knowledge, and a clear repair scope can become important when those disagreements arise.
Commercial Property Claims
Kemah has a distinctive commercial environment because tourism, restaurants, retail, entertainment, boating, and waterfront activity are significant parts of the local economy.
The Kemah Boardwalk is the city’s best-known landmark, while commercial activity also extends through the Lighthouse District, Highway 146, FM 518, and nearby marina areas. The city itself highlights the Boardwalk and Lighthouse District as defining parts of local life.
Commercial claims may involve:
- Restaurant buildings
- Retail properties
- Offices
- Warehouses
- Multi-tenant buildings
- Marina-related structures
- Apartment or multifamily properties
- Roofing systems
- Mechanical equipment
- Contents and inventory
- Business property
A commercial insurance claim may require substantially more documentation than a straightforward residential loss.
TX Public Adjusting works with both residential and commercial property claims and can review existing carrier estimates, inspection findings, repair scopes, supporting documents, and other available evidence.
Why Kemah Insurance Claims Become Underpaid
A carrier estimate is not necessarily the final measure of what a covered loss requires.
Insurance adjusters often inspect properties under significant time pressure, particularly after widespread Gulf Coast storms when hundreds or thousands of claims may be filed across the region. Communication can also slow after a major catastrophe. Property owners dealing with a delayed response can review our explanation of how long an insurance adjuster has to contact you and what options may exist when a claim is not progressing as expected.
Underpayment can occur for several reasons.
Missed Damage
Some damage is difficult to identify during a short inspection.
Interior moisture may extend beyond visible staining. Roof damage may require closer evaluation. Flashing, vents, gutters, exterior finishes, HVAC components, insulation, or adjoining materials may not be included in the first estimate.
Scope Omissions
An insurance company might recognize that damage occurred but leave necessary repair operations out of the scope.
For example, repairing one component can require removing, replacing, detaching, resetting, protecting, or finishing other components around it.
Those related operations can materially change the cost of restoring the property.
Depreciation Issues
Replacement-cost and actual-cash-value calculations can be confusing.
Property owners may not understand what depreciation was withheld, when recoverable depreciation can be claimed, or which documents may be required after repairs.
A public adjuster can review the carrier’s estimate and help the policyholder understand how the numbers were calculated.
Low Estimates
Two estimates can describe the same building but contain dramatically different quantities and repair assumptions.
Differences may involve:
- Square footage
- Material type
- Labor operations
- Roof measurements
- Number of affected rooms
- Demolition
- Finish work
- Equipment
- Contents
- Contractor overhead and related costs when applicable
The purpose of a detailed scope review is to identify those differences rather than simply accepting the first figure issued.
Documentation Problems
The strongest claim position is usually supported by organized evidence.
Photographs, measurements, damage descriptions, inventories, contractor documentation, invoices, receipts, correspondence, and policy information can all play a role.
When documentation is incomplete, the carrier may have less information available to support additional payment.
Our Public Adjusting Process
Every property loss is different, but our approach is built around careful investigation and documentation.
1. Claim Review
We begin by discussing what happened, reviewing the current status of your Kemah insurance claim, and examining available documents.
If the insurer has already issued an estimate or payment, we can review what was included.
2. Property Inspection
We inspect accessible areas of the property and document visible damage associated with the reported loss.
Depending on the claim, this may include roofing, exterior components, interior rooms, commercial areas, equipment, or contents.
3. Documentation and Scope Development
Our team organizes the information needed to present the property damage claim.
That can include photographs, measurements, itemized damage descriptions, repair considerations, estimates, and supporting documentation.
4. Claim Presentation and Negotiation
TX Public Adjusting communicates with the insurance company regarding the documented loss.
Our responsibility is to advocate for the policyholder—not the carrier.
5. Settlement and Claim Resolution
We continue working through applicable claim issues and carrier responses as the loss moves toward resolution.
No public adjuster can guarantee a specific settlement amount. What we can do is make sure your claim is professionally documented and that the insurer receives a detailed presentation of the damage being claimed.
Think your Kemah claim may be underpaid? Contact TX Public Adjusting for a Free Claim Review before assuming the carrier’s first estimate is the last word.
Why Choose TX Public Adjusting in Kemah?
Property owners have options when deciding who should assist with a claim. Our focus is representing Texas policyholders through residential and commercial property losses.
Licensed Texas Public Adjuster
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839.
Licensing matters. Property owners should know who is representing them and verify the credentials of anyone offering public adjusting services.
We Represent Policyholders
An insurance company adjuster works for the insurer.
A public adjuster works for the policyholder.
That distinction matters when there are questions about the scope of damage, repair requirements, estimates, or documentation.
Texas-Focused Claim Experience
Texas claims can involve hail, wind, hurricanes, tornadoes, freezes, fire, water losses, and major commercial losses.
Our experience includes reviewing thousands of claims involving residential and commercial properties. That background helps us recognize areas of a loss that may deserve closer examination.
Residential and Commercial Experience
A Kemah homeowner with storm-damaged roofing has different needs than a waterfront restaurant or commercial property with extensive wind and water damage.
Our work includes both residential and commercial losses, allowing us to adapt the documentation process to the property and claim involved.
Detailed Claim Documentation
A successful claim presentation depends on more than saying the insurance estimate is too low.
The difference has to be supported.
We focus on inspection, documentation, scope review, damage analysis, and communication so the carrier has a clear record of what the policyholder is claiming.
Kemah Neighborhoods and Areas We Serve
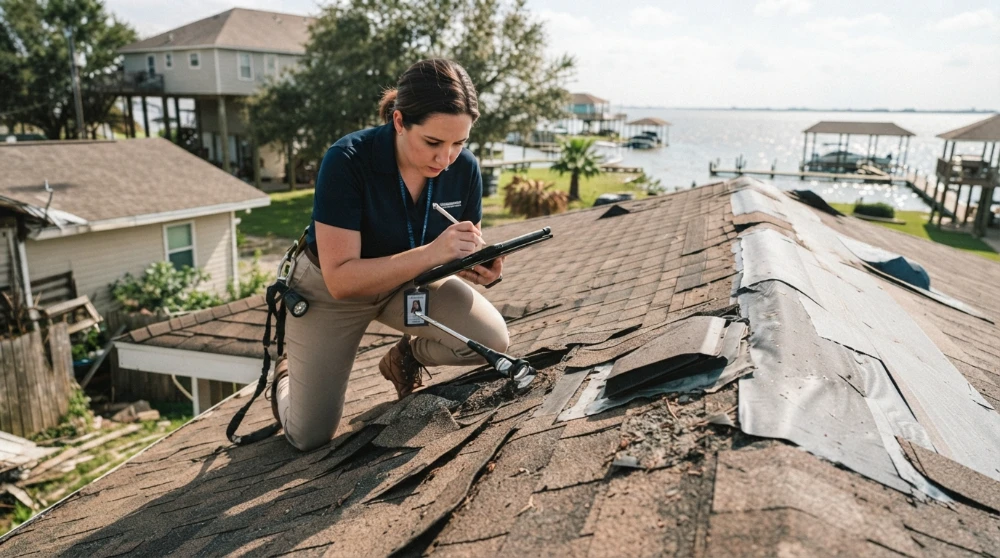
Kemah may be geographically small, but its property mix changes noticeably from one part of the city to another.
The city’s own planning documents recognize seven distinct areas: Old Kemah, Lighthouse District, West Kemah, Bayview, Kemah Oaks, South Kemah, and Kemah Crossing.
Old Kemah and the Lighthouse District
Old Kemah and the Lighthouse District sit near some of the city’s most recognizable waterfront activity. Properties here may include older buildings, restaurants, shops, homes, and structures exposed to coastal winds and heavy rain.
The proximity to Galveston Bay makes careful storm documentation particularly important after tropical systems.
Kemah Oaks
Kemah Oaks is an established residential subdivision near FM 518 and close to the Boardwalk area.
For homeowners here, common property claims may involve hail, wind-damaged roofing, plumbing leaks, interior water losses, fires, and tropical storm damage.
West Kemah and Kemah Crossing
Properties west of Highway 146 experience many of the same regional weather events but may have different drainage, development, and building characteristics than structures immediately along the bay.
Bayview and South Kemah
Bayview and South Kemah add to the city’s mix of coastal residential and commercial property.
Because Kemah’s public guidance states that flood exposure exists throughout the community rather than only along the immediate shoreline, property owners should not assume a building is immune to water problems simply because it sits farther from the Boardwalk.
Areas We Serve Near Kemah
TX Public Adjusting also assists property owners throughout the greater Clear Lake and Galveston County area, including:
- Clear Lake Shores
- League City
- Seabrook
- Bacliff
- San Leon
- Dickinson
- Texas City
- Webster
- Nassau Bay
- Friendswood
- Galveston
- Houston-area communities
Kemah, Clear Lake Shores, Bacliff, and nearby waterfront communities share many of the same Gulf Coast weather risks, particularly severe wind, tropical rainfall, storm surge, and hurricane-related property damage.
Frequently Asked Questions About Public Adjusters in Kemah
What does a public adjuster in Kemah do?
A public adjuster represents the policyholder during a property insurance claim. That can include reviewing the loss, inspecting damaged property, preparing documentation, examining the carrier’s estimate, developing a scope, and communicating with the insurer.
TX Public Adjusting works for the property owner rather than the insurance company.
When should I hire a public adjuster after a Kemah storm?
A public adjuster can become involved early in the claim or later if problems develop. Kemah property owners often seek help when damage is extensive, the claim involves several areas of the building, the insurance estimate seems too low, or the carrier has already issued a payment that does not appear sufficient.
Timing can affect the options available, so property owners who already have an older or previously paid claim may also want to understand when it is too late to hire a public adjuster. Waiting can make documentation more difficult, so having the claim reviewed promptly is often helpful.
Can a public adjuster help if my Kemah claim has already been paid?
Possibly. An issued payment does not always mean every claim issue has been resolved.
We can review the insurer’s estimate, available documentation, and current claim status to determine whether there appear to be scope omissions or other items worth examining. Contractual deadlines and policy conditions can affect available options, so timing matters.
Can you help with hurricane damage in Kemah?
Yes. Hurricane and tropical-storm losses are highly relevant to Kemah because the city sits directly beside Galveston Bay.
Claims can involve wind damage, roofing, wind-driven rain, interior water intrusion, exterior components, windows, doors, commercial equipment, and other property damage. Flood or storm-surge losses can involve separate coverage considerations, so identifying the cause of damage is especially important in coastal claims.
Does homeowners insurance cover flooding in Kemah?
Standard homeowners insurance generally does not cover rising floodwater, and Kemah specifically encourages residents to maintain flood insurance because of the city’s exposure to storm surge and heavy-rain flooding.
A storm can also involve both wind-related and flood-related damage. Determining which damage resulted from which cause can therefore become an important part of documenting a coastal insurance loss.
Can a Kemah public adjuster help with roof claims?
Yes. Roof claims are one of the property-loss categories we review.
We may examine roofing materials, flashing, vents, accessories, gutters, related exterior components, interior evidence of water intrusion, and the insurer’s existing roof scope. The specific damage and available coverage depend on the individual loss and policy.
Do you handle commercial claims near the Kemah Boardwalk?
Yes. TX Public Adjusting works with commercial as well as residential property claims.
Kemah’s waterfront economy includes restaurants, retail operations, entertainment properties, offices, marina-related businesses, and other commercial buildings. Large commercial claims can involve roofing, interior finishes, equipment, inventory, contents, and other property components requiring detailed documentation.
What if the insurance company says my Kemah property has wear and tear instead of storm damage?
Cause-of-loss disagreements are common in roof and exterior claims.
The condition of the property, location and pattern of damage, storm information, photographs, inspection findings, maintenance history, and other evidence may all become relevant. A public adjuster can document the physical conditions and present the policyholder’s claim to the carrier, but coverage decisions remain subject to the policy and claim facts.
How much does a public adjuster in Kemah charge?
Public adjusting fees are normally explained in the written agreement before representation begins and must comply with applicable Texas requirements.
TX Public Adjusting offers a Free Claim Review with no upfront fee for the review, giving you an opportunity to discuss your situation before deciding whether public adjusting services make sense for your claim.
Why use a local Texas public adjuster instead of handling the claim myself?
You are allowed to handle your own insurance claim. Some straightforward losses can be managed without professional representation.
A public adjuster becomes particularly useful when damage is extensive, estimating is complicated, important items appear to be missing, a commercial loss requires detailed documentation, or a disagreement develops with the insurer. In Kemah, coastal wind and water issues can add another layer of complexity because multiple causes of damage may need to be documented separately.
Get a Free Kemah Insurance Claim Review
You pay for property insurance to protect your home or business when a covered loss occurs. If your Kemah claim is complicated, delayed, underpaid, or missing damage, you do not have to rely solely on the insurance company’s assessment.
TX Public Adjusting represents Texas property owners—not insurance companies.
Rise Public Adjusting LLC
Texas Public Adjuster License #3356839
Residential & Commercial Property Claims
Free Claim Review
No upfront fees for the initial claim review
Contact TX Public Adjusting today to discuss your property damage and find out whether professional claim representation could help.