

Property damage in Jones Creek can turn into a complicated insurance claim quickly. This small Brazoria County community sits close enough to the Texas Gulf Coast to face hurricane winds, tropical rainfall, wind-driven rain, flooding concerns, severe thunderstorms, and occasional tornado activity. A damaged roof may be only the beginning; moisture can travel into decking, insulation, ceilings, walls, flooring, electrical components, and contents before the full scope of the loss becomes clear.
TX Public Adjusting provides public adjuster services in Jones Creek, TX for homeowners, business owners, landlords, and other policyholders dealing with residential or commercial property damage. We represent the policyholder—not the insurance company—and help document the loss, review the carrier’s estimate, identify missing or undervalued damage, and negotiate the insurance claim.
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839. Our team has reviewed thousands of property claims involving residential and commercial losses across Texas.
Have a damaged, denied, delayed, or underpaid claim in Jones Creek? Request a Free Claim Review from TX Public Adjusting. There are no upfront fees.
Why Property Owners Hire a Public Adjuster in Jones Creek
Jones Creek has a property-loss profile that is different from inland Texas communities. The village stretches along State Highway 36 in southwestern Brazoria County, only a short drive from Freeport and the Gulf Coast. Historic parts of the community include Perry’s Landing, Peach Point, Peach Crest, and Gulf Park.
That location matters when an insurance claim occurs.
A Gulf Coast storm can produce multiple kinds of damage during a single event. High winds may affect shingles, metal roofing, flashing, gutters, fencing, siding, windows, outbuildings, and trees. Wind-driven rain can then enter through openings created by the storm. Heavy rainfall can create additional water problems, while power interruptions may complicate mitigation and business operations.
A public insurance adjuster in Jones Creek works exclusively for the policyholder. The insurance company’s adjuster has a different role: evaluating the claim for the carrier. Our job is to independently evaluate your loss and present the documentation supporting the amount you are entitled to claim under your policy.
Property owners often call TX Public Adjusting when:
- The insurance company’s estimate appears too low.
- Roof or exterior storm damage was omitted.
- Interior water damage was treated as unrelated to the storm.
- The carrier approved a repair when the owner believes more extensive work is necessary.
- Depreciation or pricing significantly reduced the estimate.
- A large residential claim has become difficult to manage.
- A commercial loss involves multiple buildings, systems, tenants, or business operations.
- A claim was already paid, but important damage may have been overlooked.
- The policyholder needs experienced help communicating and negotiating with the carrier.
The earlier the loss is documented correctly, the easier it generally is to preserve evidence and establish what happened.
Jones Creek Property Damage Risks Are Closely Tied to the Gulf Coast
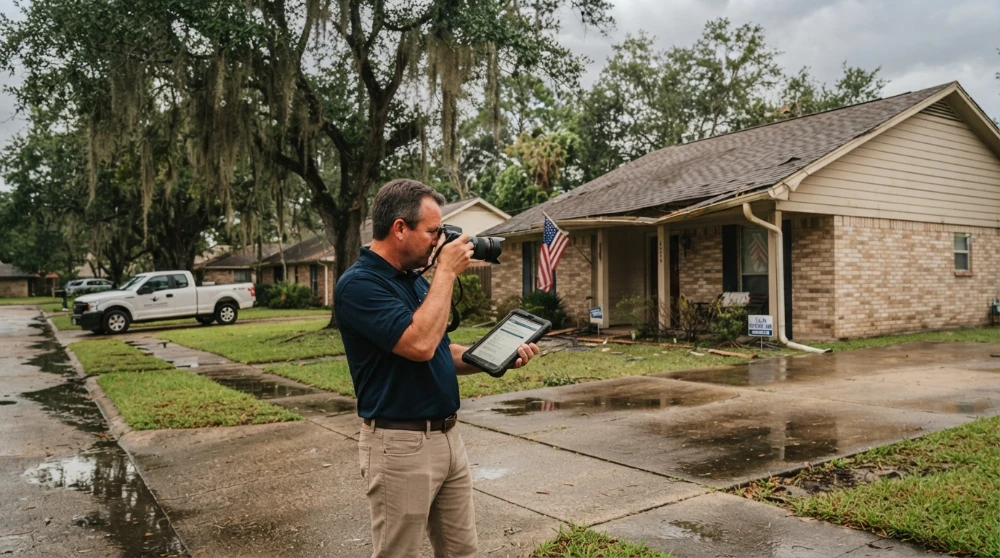
Jones Creek lies within Brazoria County’s Gulf Coast environment. The community is close to Bryan Beach, Quintana Beach, Surfside Beach, Freeport, and the Brazosport area, while Jones Creek itself is associated with coastal prairie, marsh, creek, and bottomland environments.
That geography creates several recurring property-claim concerns.
Hurricanes and Tropical Storms
For a Jones Creek property owner, hurricane season is not an abstract concern. Tropical systems moving toward the upper Texas coast can bring powerful wind, prolonged rainfall, flying debris, falling tree limbs, damaged roofing components, and water intrusion. Property owners dealing with property damage after a hurricane should document both the visible exterior damage and any resulting interior damage as early as possible.
After a hurricane, the most visible damage is not necessarily the complete damage.
A few missing shingles may accompany:
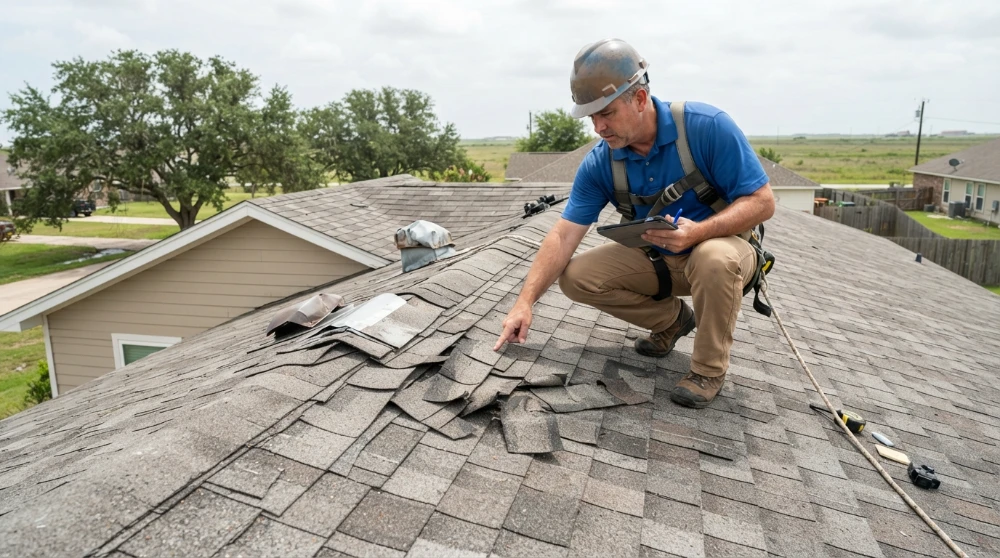
- Lifted or creased shingles that remain on the roof
- Damaged flashing and vents
- Compromised roof penetrations
- Wet decking
- Attic moisture
- Ceiling or wall staining
- Damaged gutters and downspouts
- Fence and detached-structure damage
- Window or door damage
- Interior contents losses
Separating wind damage, rain entry, flood damage, and pre-existing conditions can also become a major issue in Gulf Coast insurance claims. Coverage depends on the specific policy and cause of loss, which makes careful documentation particularly important.
Heavy Rain and Flood-Related Issues
Flood risk is a real local consideration. FEMA includes the Village of Jones Creek in Brazoria County’s flood-hazard mapping program, and the National Weather Service regularly monitors coastal and inland Brazoria County for excessive-rainfall flooding.
Not every water loss is the same from an insurance standpoint. Water entering through storm-created roof damage is different from rising surface water. Plumbing failures, drainage backups, wind-driven rain, and floodwater can also be treated differently under an insurance policy.
Our work on a water-related loss includes identifying and documenting the claimed cause, the areas affected, and the resulting repair scope.
Severe Wind and Tornadoes
Strong thunderstorms can create significant property damage even when no named hurricane is involved. A recent National Weather Service warning for central Brazoria County specifically included Jones Creek and identified the potential for 60 mph wind gusts capable of damaging roofs, siding, and trees.
Jones Creek also has a documented tornado history. An EF-1 tornado tracked through the area in October 2015, with the National Weather Service estimating peak winds around 90 mph.
Those conditions can produce claims involving shingles, metal panels, siding, fencing, windows, detached buildings, fallen trees, and water intrusion.
Hail Damage
Hail is less synonymous with the upper Texas coast than it is with North Texas, but Jones Creek can still experience hail during severe thunderstorms. Hail damage can be especially difficult for a property owner to evaluate from ground level.
A roof may show no obvious hole and still have functional damage to shingles, metal components, vents, flashing, gutters, rooftop equipment, screens, or siding.
For commercial properties, hail may also affect membrane roofs, metal roofing systems, HVAC equipment, skylights, and exterior components.
Common Insurance Claims in Jones Creek
Hail Damage Claims
A hail damage insurance claim should be based on more than a quick glance at the roof. We evaluate the complete storm-loss scope, including roofing, gutters, vents, flashing, siding, windows, fences, exterior equipment, and interior areas when water intrusion followed the storm.
Documentation can include photographs, measurements, damage mapping, repair estimates, and supporting information about the loss.
Water Damage Claims
Water damage can spread far beyond the point where it first becomes visible.
A roof leak may affect insulation and drywall before a stain appears on the ceiling. A plumbing failure may extend beneath flooring or cabinets. Moisture can also remain within wall assemblies after surfaces appear dry.
A water damage public adjuster can review water-loss documentation, mitigation records, damaged materials, repair estimates, and the carrier’s scope to determine whether important items were omitted.
Fire and Smoke Damage Claims
A fire claim may involve far more than rebuilding the visibly burned section of a property. An experienced fire insurance adjuster can help document structural damage, smoke and soot contamination, contents losses, debris removal, and other parts of the claim.
Potential components include:
- Structural repairs
- Smoke and soot contamination
- Contents damage
- Odor treatment
- Electrical systems
- HVAC contamination
- Demolition and debris removal
- Temporary repairs
- Additional living expenses where applicable
- Commercial equipment and inventory
Fire losses often require extensive inventories and coordination. TX Public Adjusting helps organize the claim so each category of damage receives appropriate attention.
Storm Damage Claims
Jones Creek storm claims frequently require an understanding of how several types of damage connect.
For example, a thunderstorm may lift roofing materials, damage flashing, drive rain beneath the roof covering, soak insulation, stain ceilings, and damage flooring. If each part of that sequence is evaluated separately, the resulting estimate may fail to reflect the actual restoration work required.
Our goal is to present the loss as a complete, documented scope.
Roof Damage Claims
Roof claims are among the most common situations in which property owners question an insurance estimate. A public adjuster for a roof claim can review the carrier’s measurements, repair scope, roofing components, pricing, and related interior damage.
Carrier estimates can become disputed over:
- Repair versus replacement
- Number of damaged slopes
- Shingle or material availability
- Flashing
- Underlayment
- Decking
- Ridge caps
- Drip edge
- Gutters
- Roof vents
- Metal components
- Interior water damage
- Labor or material pricing
Jones Creek also has many established residential properties rather than only new subdivisions. Local housing includes older homes, with ranch-style construction common in the area. Older roofing systems and previous repairs can make documenting the precise storm-related damage particularly important.
Commercial Property Claims
The broader Brazosport area includes substantial industrial, commercial, retail, and service activity. Jones Creek property owners may therefore be dealing not only with houses but also rental buildings, offices, shops, warehouses, and other commercial properties.
Businesses and property owners facing a significant loss may benefit from working with a commercial public adjuster who can organize the building, equipment, inventory, and other documented portions of the loss. Commercial claims can involve:
- Low-slope and metal roofing systems
- Exterior wall systems
- HVAC units
- Electrical equipment
- Inventory
- Interior finishes
- Water mitigation
- Tenant improvements
- Code-related work
- Business interruption documentation where coverage applies
A commercial claim can become much larger than the initial carrier estimate when interconnected building components are not fully scoped.
If your Jones Creek claim has already been inspected and the numbers do not appear to match the damage, TX Public Adjusting can provide a Free Claim Review.
Why Insurance Claims Become Underpaid
An insurance claim can be underpaid even when the insurer acknowledges that a covered loss occurred.
Damage Was Missed During the Initial Inspection
Storm inspections can move quickly. Some damage is difficult to see without inspecting the roof, attic, exterior elevations, interior rooms, and related building components.
A carrier may acknowledge roof damage but miss wet insulation, ceiling damage, gutters, flashing, fencing, or related exterior items.
The Estimate Does Not Include the Complete Scope
The dollar amount follows the scope.
If an estimate leaves out necessary work, the settlement can be too low even when individual line-item prices appear reasonable.
We compare the carrier’s scope with the actual conditions observed at the property.
Depreciation Reduces the Initial Payment
Insurance estimates may include depreciation depending on the policy and claim. Property owners sometimes focus only on the first check without understanding how recoverable depreciation, deductibles, or other policy provisions affect the total claim.
A public adjuster can help a policyholder understand how the carrier calculated the estimate and what documentation may be required as the claim progresses.
Pricing or Quantities Are Too Low
A missing roofing square, an incorrect room dimension, omitted labor, or unrealistic material allowance can affect the final estimate.
These problems become more significant when repeated throughout a large residential or commercial loss.
Documentation Is Incomplete
Insurance claims are evidence-driven.
Photographs, videos, measurements, inventories, invoices, mitigation records, weather information, contractor estimates, and other documentation may all become relevant.
Property owners should not have to rely solely on a verbal explanation that “the storm damaged everything.” The claim needs a clear paper trail showing what was damaged and why it belongs in the scope.
Our Public Adjusting Process
Every property loss is different, but our work generally follows five stages.
1. Claim Review
We start by reviewing the circumstances surrounding the loss.
That may include the policyholder’s existing claim documents, insurance estimate, payment information, photographs, correspondence, contractor estimates, or denial letter.
If the claim has not yet been fully documented, we identify what information needs to be gathered.
2. Property Inspection
We inspect the property to identify visible damage and determine what additional documentation may be needed.
Depending on the loss, an inspection may involve the roof, exterior elevations, interior rooms, attic areas, damaged contents, commercial systems, or other affected portions of the property.
3. Documentation and Scope Development
We build a detailed claim file.
That can involve photographs, measurements, estimates, damaged-property inventories, supporting invoices, and other documentation necessary to explain the loss.
The objective is straightforward: clearly show the carrier what happened, what was damaged, and what restoring the property reasonably requires.
4. Insurance Company Communication and Negotiation
TX Public Adjusting communicates with the insurer concerning the documented claim.
We address scope differences, missing items, estimate discrepancies, and supporting documentation while advocating for the policyholder’s position.
5. Settlement and Claim Resolution
We continue working through the claim process toward resolution according to the policy and documented damage.
A public adjuster cannot guarantee a particular settlement amount, but experienced representation can help ensure that the claim is thoroughly prepared and that overlooked damage is brought to the carrier’s attention.
Local Claim Experience Matters in Jones Creek
Jones Creek is not simply another Houston-area suburb.
It is a small Gulf Coast community with a long local history and a distinct physical setting. State Highway 36 runs through the village toward Freeport, while Stephen F. Austin Road and Gulf Prairie Road connect areas associated with some of the earliest Anglo-American settlement in Texas. The community is home to the Gulf Prairie Cemetery, where Stephen F. Austin was originally buried, and to historical sites associated with Peach Point and the Old Three Hundred.
Those local details matter because the property environment is equally distinctive.
Jones Creek combines:
- Mature trees surrounding many residential properties
- Established homes rather than exclusively new construction
- Low-lying Gulf Coast terrain
- Proximity to marshes, creeks, and coastal waterways
- Exposure to tropical weather
- Heavy-rain potential
- Strong thunderstorm winds
- Nearby industrial and commercial activity in the Brazosport area
A fallen mature tree can turn a wind claim into a roof, structural, electrical, water, and contents claim at the same time. A tropical storm can create exterior damage followed by interior moisture problems. A commercial building may have roof damage that affects equipment or operations beneath it.
The claim needs to reflect those connections.
Why Choose TX Public Adjusting
Licensed Texas Public Adjuster
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839.
We focus on Texas property insurance claims and understand the documentation, estimating, inspection, and negotiation issues that frequently arise after storms and other major losses.
We Represent Policyholders
A public adjuster represents the insured property owner.
We do not work for the insurance company on your claim. Our role is to evaluate and document the loss from the policyholder’s side of the process.
Residential and Commercial Claim Experience
Our team has reviewed thousands of claims and works with both residential and commercial property losses.
That experience includes roof, hail, wind, hurricane, water, fire, smoke, and complex commercial property damage.
Detailed Claim Documentation
A strong claim is built on evidence.
We focus on documenting the physical damage, developing the repair scope, reviewing estimates, and identifying areas where the carrier’s evaluation may be incomplete.
Free Claim Review
You do not need to guess whether a public adjuster can help.
TX Public Adjusting offers a Free Claim Review with no upfront fees so you can understand the situation before deciding how to proceed.
Areas We Serve Near Jones Creek
Our public adjusting services extend throughout Jones Creek and the surrounding Brazoria County and Brazosport communities, including:
- Peach Point
- Perry’s Landing
- Peach Crest
- Gulf Park
- Freeport
- Lake Jackson
- Clute
- Brazoria
- Richwood
- Oyster Creek
- Quintana
- Surfside Beach
- Angleton
- Other communities throughout Brazoria County
Jones Creek’s historic local sections—Perry’s Landing, Peach Point, Peach Crest, and Gulf Park—are documented as established parts of the community rather than names added simply for geographic targeting.
Frequently Asked Questions About Public Adjusters in Jones Creek
What does a public adjuster in Jones Creek do?
If you are unfamiliar with what a public adjuster does, the key distinction is that a public adjuster represents you, the policyholder, during a property insurance claim. We inspect and document damage, review the insurance company’s estimate, prepare supporting claim documentation, communicate with the carrier, and negotiate disputed scope or valuation issues.
For Jones Creek property owners, this frequently means evaluating wind, hurricane, roof, water, hail, fire, or commercial property damage where the initial carrier estimate may not show the complete loss.
When should I hire a public adjuster after a Jones Creek storm?
You can contact a public adjuster shortly after the loss, but you may also be able to hire one after the insurance company has inspected or paid the claim.
Property owners often seek help when the claim is large, the damage affects multiple areas, the carrier’s estimate appears low, or the insurer has denied part of the loss. If your claim has already been open for some time, our guide explains when it is too late to hire a public adjuster and why claim deadlines and circumstances matter.
Can TX Public Adjusting review a claim that has already been paid?
Yes. A payment does not necessarily mean every issue has been resolved. We can review the carrier estimate, photographs, repair scope, and claim documents to look for damage or necessary work that may not have been included.
The options available will depend on the policy, claim status, deadlines, previous communications, and circumstances of the loss.
Are Jones Creek hurricane claims different from ordinary storm claims?
They can be. A hurricane may cause wind damage, wind-driven rain, fallen-tree damage, roof openings, interior water intrusion, and flood-related damage during the same event.
Insurance policies may treat these causes differently. Careful documentation of how water entered the building and what physical storm damage occurred can therefore become particularly important.
Does homeowners insurance cover flooding in Jones Creek?
Standard homeowners policies generally distinguish flood from other sources of water damage, and coverage depends on the specific policies involved. Jones Creek is included in FEMA’s Brazoria County flood-hazard mapping, so local property owners should understand the difference between flood coverage and coverage for other causes of water intrusion.
For example, rain entering through a roof opening created by wind involves a different coverage analysis from rising water entering from outside. Always review the actual policy language applicable to your loss.
Can you help with roof damage even if only part of the roof was approved?
Yes. Partial roof approvals are a common reason property owners request a second look at their claim.
We can inspect the roof, compare conditions across slopes, review accessories and related exterior components, examine the carrier’s measurements and estimate, and document additional storm-related damage when supported by the evidence.
Do you handle commercial claims around Jones Creek and Freeport?
Yes. TX Public Adjusting works with commercial as well as residential property claims.
Commercial losses may involve roof systems, HVAC equipment, interiors, inventory, tenant spaces, exterior components, water mitigation, and other property-related issues. Large losses require organized documentation because even small omissions can add up across a sizable building.
How much does it cost to hire a Jones Creek public adjuster?
Public adjusting fees depend on the engagement and applicable Texas requirements. TX Public Adjusting provides a Free Claim Review and has no upfront fees.
Before you retain us, the fee arrangement and scope of our services are explained so you can make an informed decision.
What should I do immediately after storm damage in Jones Creek?
Protect people first. When it is safe, take photographs and video of the property before damaged materials are removed. Make reasonable temporary efforts to prevent additional damage, keep invoices and receipts, and avoid disposing of damaged property before it has been adequately documented when practical.
For major losses, consider having the claim reviewed early. Jones Creek storms can cause interconnected roof, exterior, and interior damage that may become harder to document after repairs begin.
Why hire TX Public Adjusting instead of relying only on the insurance company’s adjuster?
The carrier’s adjuster evaluates the claim on behalf of the insurance company, while TX Public Adjusting represents the policyholder. If you want a deeper explanation of the different roles, see our guide to a public adjuster vs. independent adjuster.
We independently inspect the loss, develop documentation, review the insurance estimate, identify omitted or undervalued items, and advocate for the claim supported by the policy and evidence. Rise Public Adjusting LLC is licensed in Texas under License #3356839.
Get Insurance Claim Help in Jones Creek
A damaged property is stressful enough without spending weeks trying to determine why an insurance estimate does not match what you see at the property.
If your home, rental property, or commercial building in Jones Creek has suffered hurricane, wind, hail, roof, water, fire, smoke, or other covered property damage, contact TX Public Adjusting.
We can review a new claim, an existing estimate, an underpaid loss, or a claim where important damage appears to have been missed.
Request your Free Claim Review today.
- Licensed Texas Public Adjuster
- Rise Public Adjusting LLC
- Texas License #3356839
- Residential & Commercial Claims
- Independent Policyholder Representation
- No Upfront Fees
Contact TX Public Adjusting and find out what may be missing from your Jones Creek property insurance claim.