Property damage in Hidalgo can become complicated quickly. A severe thunderstorm can lift shingles, drive rain beneath a roofing system, damage exterior finishes, and allow water to spread into ceilings or walls before the full loss is visible. Tropical weather can bring a different set of problems, including prolonged rain, wind-driven water, drainage backups, and damage that affects several parts of a home or commercial building at once.
TX Public Adjusting provides insurance claim help in Hidalgo for residential and commercial property owners. As a licensed Texas public adjuster, we represent the policyholder—not the insurance company. Our team reviews the policy, inspects the damage, prepares supporting documentation, identifies omissions in the carrier’s estimate, and presents the claim based on the actual scope of covered damage.
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839. We have experience reviewing thousands of property claims involving roofs, interiors, mechanical systems, commercial buildings, contents, water intrusion, fire losses, and storm damage throughout Texas.
Concerned that your Hidalgo property claim was underpaid, delayed, or documented incorrectly? Contact TX Public Adjusting for a free claim review. There are no upfront fees.
Insurance Claim Help for Hidalgo Property Owners
Hidalgo is located in southern Hidalgo County along the Rio Grande, approximately five miles south of McAllen. The city is part of the broader McAllen–Edinburg–Pharr metropolitan area and has deep historical ties to trade, agriculture, transportation, and cross-border commerce.
Those local characteristics matter during a property insurance claim. Hidalgo includes single-family homes, rental properties, neighborhood businesses, warehouses, retail spaces, offices, institutional buildings, and properties connected to international commerce. A storm that damages several blocks can create very different claims depending on the roof system, building age, drainage conditions, interior finishes, equipment, and policy language involved.
A homeowner near the Hidalgo Historic District may face different repair considerations than the owner of a newer home closer to the McAllen city limit. A business near the Hidalgo–Reynosa International Bridge or State Highway 336 may have additional concerns involving inventory, tenant improvements, signage, equipment, lost access, or business interruption.
The city’s historic area, known locally as “The District,” includes buildings more than a century old. Older construction can require a more careful inspection because replacement materials, code-related work, concealed deterioration, and matching issues may affect the repair scope.
A public adjuster helps bring those property-specific details into the claim instead of relying on a short inspection or a generic estimate.
Why Property Owners Hire a Public Adjuster in Hidalgo
An insurance carrier assigns an adjuster to investigate the loss on behalf of the insurance company. A public adjuster works for the policyholder.
That distinction becomes especially important when a claim involves widespread storm damage, competing causes of loss, complicated policy provisions, or a disagreement over the cost and scope of repairs.
Hidalgo property owners may hire a public adjuster when:
- The insurance company’s estimate appears too low.
- Roof damage was classified as cosmetic or repairable.
- Water intrusion was documented without identifying the storm-created opening.
- Interior damage was omitted from the estimate.
- The carrier paid for isolated repairs instead of a complete repair scope.
- Depreciation appears excessive or unsupported.
- Matching concerns were ignored.
- Commercial equipment, inventory, or tenant improvements were missed.
- The claim has stalled without a clear explanation.
- A previously closed claim needs to be reviewed for overlooked damage.
- The property owner does not have time to manage inspections, estimates, documents, and carrier communications.
TX Public Adjusting evaluates the claim from the policyholder’s side. We do not decide coverage, and we do not promise a particular settlement. We document the loss, identify supportable claim items, and advocate for a fair evaluation under the policy.
Hidalgo’s Storm and Property-Damage Risks
Hidalgo’s location in the Rio Grande Valley exposes local properties to several types of severe weather. County emergency planning specifically addresses hurricanes, flood events, fires, and other severe-weather incidents. Hidalgo County also publishes evacuation guidance for residents when a hurricane threatens the region.
Hurricanes and Tropical Storms
Hidalgo is inland from the Gulf Coast, but tropical systems can still bring destructive wind and heavy rainfall into the Rio Grande Valley. The National Weather Service maintains a history of significant tropical events affecting Deep South Texas and the Rio Grande Valley.
A hurricane-related property claim may include:
- Missing, creased, or lifted shingles
- Roof membrane damage
- Wind-driven rain intrusion
- Broken windows or damaged doors
- Exterior cladding and stucco damage
- Fence and gate damage
- Damaged rooftop equipment
- Interior ceiling and wall damage
- Electrical or mechanical damage
- Fallen-tree or debris impact
- Business interruption
- Spoiled inventory following a covered power interruption
Wind and water damage may occur during the same storm, but they are not always handled under the same coverage. The source and pathway of the water must be documented carefully. A public adjuster can help distinguish roof or opening-related water intrusion from conditions that may fall under a separate flood policy or exclusion.
Heavy Rain and Flood-Related Damage
Intense rainfall is a serious concern across the Rio Grande Valley. Hidalgo County warns that hurricanes and tropical storms can cause flooding many miles inland and encourages residents to evaluate the flood risk for their specific address.
In March 2025, record-breaking rainfall caused severe flooding across parts of Hidalgo County and the Texas–Mexico border region, damaging property and infrastructure and stranding motorists.
Not every water loss is covered by the same policy. Surface flooding is generally treated differently from rain entering through storm damage, a plumbing failure, or water released by a covered building-system loss. Before making assumptions, the property owner should identify:
- Where the water entered
- When the intrusion began
- Whether the roof or exterior was damaged
- Whether doors, windows, flashing, or penetrations failed
- Whether water rose from the ground
- Which rooms and building components were affected
- Whether emergency mitigation was performed
- Whether moisture remains behind walls, cabinets, flooring, or insulation
Photos, moisture readings, drying records, repair invoices, weather information, and inspection findings can all influence how the claim is evaluated.
Severe Thunderstorms, Wind, and Hail
South Texas thunderstorms can produce strong wind, hail, lightning, and intense rainfall within a short period. Windstorm insurance can apply to damage caused by hail or wind from thunderstorms, tornadoes, and hurricanes, depending on the property’s location and the coverage purchased.
Hail damage is not always obvious from the ground. A roof may remain in place while shingles, metal panels, vents, flashing, gutters, coatings, or rooftop equipment sustain functional damage. Wind can also loosen roofing materials without removing them completely.
A complete storm inspection should consider more than the field of the roof. It may need to include:
- Shingles, tiles, panels, or membrane
- Ridge caps and roof edges
- Flashing and penetrations
- Gutters and downspouts
- Vents and rooftop units
- Skylights
- Window screens and glazing
- Fences and gates
- Exterior paint or stucco
- Garage doors
- Detached structures
- Interior signs of water intrusion
Extreme Heat and Secondary Damage
Hidalgo’s hot climate can aggravate damaged roofing materials. Once shingles, coatings, seams, or flashing have been compromised, continued heat and sun exposure may accelerate deterioration.
Heat can also complicate commercial losses involving refrigeration, air-conditioning equipment, food inventory, electronics, or temperature-sensitive materials. The cause of the equipment failure and the applicable policy provisions must be reviewed before the loss is presented.
Common Insurance Claims in Hidalgo
Hail Damage Claims
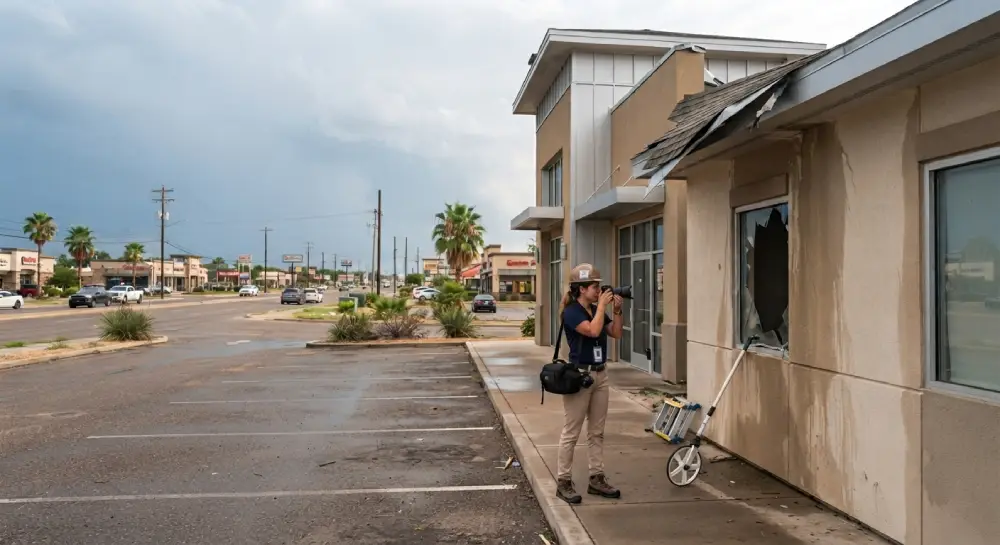
Hail claims often become disputed because the visible damage may be scattered across multiple slopes or building components. The carrier may estimate a small repair while the contractor or property owner believes a larger scope is required.
TX Public Adjusting reviews the condition of the roof and related exterior components, examines the carrier’s estimate, and documents supportable differences. We also evaluate whether accessories, flashing, underlayment, code-related items, access requirements, and interior damage were included.
Read more about hail damage insurance claims in Texas.
Water Damage Claims
Water can spread far beyond the first visible stain. It may travel through insulation, drywall, flooring, cabinetry, framing, or mechanical spaces.
A water-damage claim should document both the source and the complete area affected. That may require moisture mapping, photographs, mitigation records, contractor estimates, plumbing reports, or roof inspection findings.
Our team reviews whether the insurer’s estimate includes reasonable removal, drying, cleaning, repairs, material replacement, access, detach-and-reset work, and related finishes.
Property owners dealing with an active or disputed water loss can review our guide to dealing with an insurance adjuster after water damage.
Fire and Smoke Damage Claims
Fire losses can affect the structure, contents, electrical systems, HVAC equipment, roofing, finishes, and indoor air quality. Smoke and soot may travel into rooms that were not directly touched by flames.
A complete fire claim may involve:
- Structural repairs
- Smoke and soot cleaning
- Odor treatment
- Debris removal
- Contents inventory
- Textile or electronics evaluation
- Temporary repairs
- Additional living expenses
- Business interruption
- Code-related work
- Mechanical and electrical inspection
TX Public Adjusting helps organize the claim so that the visible and less-visible portions of the loss are presented together. Learn more about working with a fire insurance adjuster and understanding fire damage insurance claims.
Storm and Wind Damage Claims
Wind damage may affect roofing materials, soffits, fascia, vents, windows, doors, fences, signs, and detached structures. Wind-driven rain can then cause interior damage.
A carrier inspection performed after the roof has dried may document only a ceiling stain or a few lifted shingles. That can leave the repair estimate incomplete. The claim should connect the exterior storm damage, the water-entry pathway, and the resulting interior repairs when the evidence supports that connection.
Roof Damage Claims
Roof claims are among the most frequently disputed property claims because repairability, age, wear, matching, material availability, and causation can all become points of disagreement.
A fair roof evaluation should consider:
- The documented date of loss
- The type and age of the roofing system
- The direction and pattern of damage
- The number of affected slopes or sections
- Whether spot repairs are technically practical
- Whether materials can be matched
- The condition of flashing and accessories
- Interior water damage
- Local code requirements
- Policy deductibles, exclusions, and endorsements
See our guide on hiring a public adjuster for a roof claim.
Commercial Property Claims
Commercial claims often involve more than the physical building. A loss may affect inventory, equipment, tenants, employees, customers, operations, access, and revenue.
TX Public Adjusting assists Hidalgo businesses with claims involving:
- Retail buildings
- Restaurants
- Offices
- Warehouses
- Multifamily properties
- Hospitality properties
- Churches and nonprofit facilities
- Industrial buildings
- Medical or professional offices
- Mixed-use properties
Commercial losses near major roads, border infrastructure, retail corridors, and the Hidalgo–Reynosa International Bridge may require detailed documentation of business personal property, tenant improvements, specialized equipment, and interruption-related expenses.
Have a residential or commercial claim in Hidalgo? Request a free claim review before accepting a settlement that may not include the full documented loss.
Why Hidalgo Insurance Claims Become Underpaid
An underpaid claim does not always result from one obvious mistake. It often reflects several smaller omissions that add up.
Damage Was Missed During the Inspection
A brief exterior inspection may overlook secondary structures, roof accessories, multiple elevations, interior moisture, equipment, or less-visible storm damage.
The Repair Scope Was Too Narrow
The insurer may estimate only the visibly damaged item without including the work required to access, remove, reinstall, protect, or finish the surrounding materials.
For example, an estimate may include drywall replacement but omit insulation, texture matching, painting adjacent surfaces, trim removal, or electrical fixture handling.
Depreciation Was Applied Incorrectly
Some depreciation may be recoverable after repairs, depending on the policy. Other depreciation may be calculated incorrectly or applied to labor and materials in a way that warrants further review.
The Estimate Used Incomplete Quantities
Room dimensions, roofing measurements, cabinet runs, flooring areas, exterior elevations, or equipment counts can be understated. Small quantity differences can create a large gap on a major loss.
Documentation Was Incomplete
The insurer may not receive the photographs, estimates, inventories, moisture records, receipts, or expert findings needed to evaluate the full claim.
Damage Was Attributed to Wear and Tear
Carriers may distinguish storm damage from aging, deterioration, installation defects, or maintenance conditions. The property owner needs clear evidence connecting the claimed damage to the reported event.
Commercial Losses Were Treated Like Simple Building Repairs
A commercial property claim may require separate consideration of building damage, business personal property, tenant improvements, extra expenses, lost income, equipment, and operational delays. A basic construction estimate may not address all of those categories.
Our Public Adjusting Process
1. Claim Review
We begin by reviewing the status of the loss. This may include the policy, declarations, carrier correspondence, estimates, payment letters, photographs, contractor documents, and prior inspection reports.
We identify the main claim issues and determine whether a more detailed inspection or documentation package may be appropriate.
2. Property Inspection
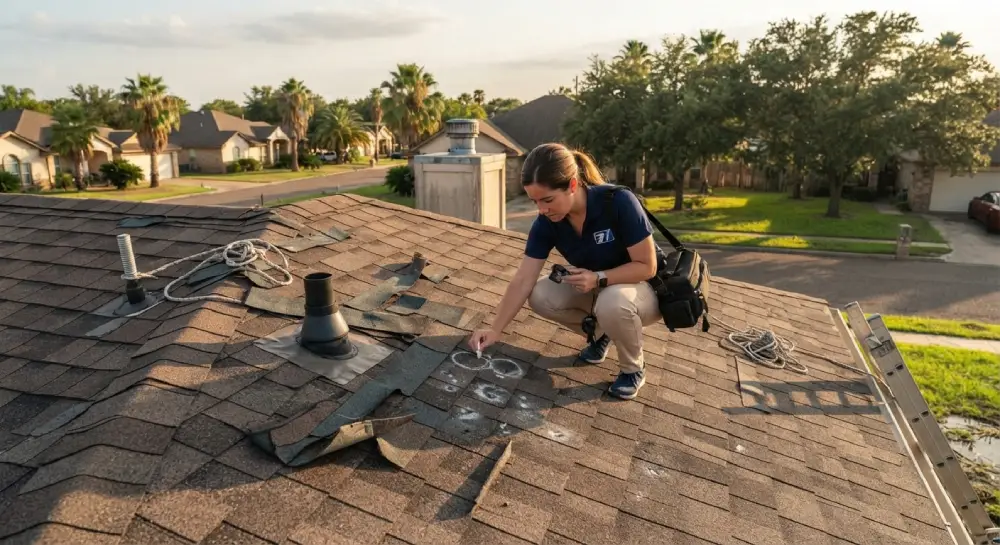
Our team inspects the reported damage and looks for related conditions that may have been overlooked. The inspection is tailored to the type of loss and the building.
For a Hidalgo storm claim, that may include the roof, exterior elevations, windows, doors, fencing, rooftop equipment, interior water damage, and detached structures.
3. Damage Documentation
We organize photographs, measurements, repair information, inventories, estimates, and other supporting material. The goal is to present a clear, supportable account of what was damaged and what may be required to repair or replace it.
4. Scope and Estimate Review
We compare the carrier’s estimate with the documented loss. We look for missing quantities, omitted rooms, incomplete trades, pricing differences, depreciation concerns, and related work that may be necessary to complete repairs.
5. Claim Presentation and Negotiation
TX Public Adjusting communicates with the insurance carrier and presents the policyholder’s documented position. We respond to questions, address scope differences, and participate in the claim process on the property owner’s behalf.
6. Settlement Review
When the carrier issues a revised estimate, payment, or coverage position, we review the documents with the policyholder. The insurer determines what it will pay, but our role is to help ensure the claim was presented accurately and thoroughly.
Why Choose TX Public Adjusting in Hidalgo?
Licensed Texas Public Adjuster
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839.
Representation for the Policyholder
We work for property owners and policyholders, not insurance companies. Our responsibility is to document and advocate for the policyholder’s claim.
Residential and Commercial Experience
Our experience includes homes, multifamily buildings, retail properties, offices, warehouses, churches, restaurants, and other commercial facilities.
Thousands of Claims Reviewed
Our team has reviewed thousands of insurance claims involving storm, hail, roof, water, fire, smoke, and commercial property damage.
Texas-Focused Claim Knowledge
Texas property claims are affected by severe weather, policy endorsements, deductibles, construction requirements, repair practices, and carrier procedures. Our work is focused on helping Texas property owners understand and present those claims.
Detailed Scope Review
We do not limit the review to the carrier’s bottom-line number. We examine how that number was calculated and whether the documented repair scope is complete.
No Upfront Fees
The initial claim review is free, and there are no upfront fees. Any public-adjusting fee and the terms of representation are explained in writing before services begin.
Hidalgo Neighborhoods and Nearby Areas We Serve
TX Public Adjusting assists property owners throughout Hidalgo and surrounding communities in the Rio Grande Valley.
Local service areas include:
- Hidalgo Historic District and The District
- Las Milpas
- South McAllen
- Pharr
- Mission
- San Juan
- Alamo
- Palmview
- Granjeno
- Penitas
- Edinburg
- Donna
- Weslaco
- Palmhurst
- McAllen
- Nearby unincorporated areas of Hidalgo County
We also assist property owners near local destinations and commercial corridors such as the Hidalgo–Reynosa International Bridge, Payne Arena, State Highway 336, U.S. Highway 281, and the historic center of Hidalgo.
Frequently Asked Questions
What does a public adjuster do for a Hidalgo property claim?
A public adjuster represents the policyholder during the insurance claim. The work may include reviewing the policy, inspecting the property, documenting damage, preparing an estimate or claim package, communicating with the carrier, and addressing differences in scope or valuation.
For Hidalgo claims, that often means connecting roof, wind, rain, and interior damage into one well-supported presentation rather than treating each visible symptom as an isolated repair.
When should I hire a public adjuster in Hidalgo?
Property owners often call after receiving a low estimate, partial denial, delayed response, or claim payment that does not appear sufficient to complete repairs. You may also hire a public adjuster earlier when the loss is large, technically complex, or disruptive to a business.
The right timing depends on the claim. Review our guide explaining when it may be too late to hire a public adjuster.
Can a public adjuster help after the insurance company has already paid?
Possibly. A payment does not always mean every claim issue has been resolved. The estimate may still omit damage, quantities, materials, code-related work, or necessary repairs.
TX Public Adjusting can review the existing documents and explain whether there appear to be supportable issues worth presenting. Policy deadlines and claim-specific circumstances matter, so it is better to request a review promptly.
Can you help with a denied Hidalgo insurance claim?
We can review the denial letter, policy, reported cause of loss, inspection findings, photographs, and other available evidence. Some denied claims may involve a factual or documentation dispute that warrants further presentation.
A public adjuster cannot guarantee that a denial will be reversed and does not provide legal advice. Claims involving legal interpretation, litigation, or bad-faith allegations may require an attorney.
How much does a public adjuster cost in Texas?
Public adjusters typically work under a written agreement that explains the fee and services. The fee may be calculated as a percentage of the insurance recovery obtained through the public adjuster’s work, subject to applicable Texas requirements and the contract terms.
TX Public Adjusting offers a free initial claim review and does not charge an upfront fee. The compensation structure is explained before you decide whether to hire us.
Can a public adjuster help with flood damage in Hidalgo?
A public adjuster may assist with a flood insurance claim or with separating flood damage from damage claimed under another property policy. The key issue is identifying how the water entered and which policy may apply.
Surface water and rising water are generally treated differently from rain entering through wind-created openings, plumbing failures, or other covered building losses. Each source should be documented rather than grouped together without analysis.
What should I do immediately after storm damage?
Protect people first. When it is safe, take photographs and videos before moving or discarding damaged property. Make reasonable temporary repairs to prevent additional damage, keep receipts, and avoid permanent repairs until the damage has been documented.
Report the loss promptly, preserve damaged materials when practical, and keep a written record of conversations with the insurer, contractor, mitigation company, or property manager.
Can you help with commercial claims near the Hidalgo border corridor?
Yes. Commercial claims may involve building repairs, inventory, machinery, furniture, tenant improvements, signage, extra expenses, or business-income issues.
Properties near the Hidalgo–Reynosa International Bridge and major transportation corridors may face additional disruption when a loss affects access, deliveries, customer traffic, refrigeration, security, or operations. Those impacts should be documented carefully and evaluated under the applicable policy.
How long does a Hidalgo property claim take?
The timeline depends on the size of the loss, the insurer’s response, the number of inspections, the documents required, coverage questions, and whether the parties disagree about scope or value.
A straightforward roof claim may move more quickly than a large commercial fire or water loss. Read more about how long an insurance adjuster has to contact you.
Is TX Public Adjusting part of the insurance company?
No. TX Public Adjusting represents policyholders. We are not the carrier’s adjuster, an independent adjuster hired by the carrier, or an insurance-company employee.
The business operates through Rise Public Adjusting LLC under Texas License #3356839. Our role is to help the property owner document and present the claim.
Request a Free Hidalgo Claim Review
A low insurance estimate can leave a Hidalgo homeowner or business owner with a serious repair gap. Missing roof components, incomplete water-damage scopes, incorrect measurements, omitted commercial property, and unsupported depreciation can materially change the outcome of a claim.
TX Public Adjusting helps policyholders understand what the carrier included, what may have been missed, and what documentation may be needed to support the loss.
Contact TX Public Adjusting today for a free claim review.
- Licensed Texas Public Adjuster
- Rise Public Adjusting LLC
- Texas License #3356839
- Residential and commercial claims
- No upfront fees
- Independent representation for policyholders