

Property damage in Hardin can turn into a complicated insurance claim quickly. Severe thunderstorms can bring damaging wind and hail, tropical systems can push heavy rain and strong winds well inland from the Gulf, and water can enter a property through damaged roofing, openings in the building envelope, plumbing failures, or drainage problems. For homeowners and business owners looking for a Public Adjuster Hardin, TX, TX Public Adjusting provides independent representation focused entirely on the policyholder.
Hardin is a small Liberty County community centered near the intersection of State Highway 146 and FM 834, about six miles north of the City of Liberty. Its location between the Houston and Beaumont regions puts local properties in a weather pattern influenced by both inland thunderstorms and Gulf Coast tropical systems. The City of Hardin identifies SH 146 as the major north-south route through town and reports a 2020 population of 961.
TX Public Adjusting is a Texas public adjuster operated by Rise Public Adjusting LLC, Texas License #3356839, assisting residential and commercial policyholders with storm, hail, roof, water, fire, hurricane, and other covered property damage claims. Our team has reviewed thousands of property claims across Texas, giving us experience with the documentation, estimating, policy questions, and negotiations that often determine how a claim progresses.
Get a Free Claim Review. If your Hardin property has suffered damage, or your insurance payment appears too low for the repairs actually required, contact TX Public Adjusting for an independent review. There are no upfront fees to have us evaluate whether we may be able to assist.
Why Property Owners Hire a Public Adjuster in Hardin
An insurance claim contains two separate issues: what physically happened to the property and what the insurance policy provides for that loss. Problems often arise when those two pieces do not line up correctly in the carrier’s estimate.
The adjuster sent by an insurance company evaluates the loss for the carrier. A public insurance adjuster in Hardin represents the policyholder instead. If you’re unfamiliar with the different roles involved in a property claim, our guide explaining public adjuster vs. independent adjuster breaks down who each adjuster represents and why that distinction matters. Our responsibility is to document the loss from the property owner’s perspective and present the covered damage as completely and accurately as possible.
That can include:
- Reviewing the insurance policy and available coverage
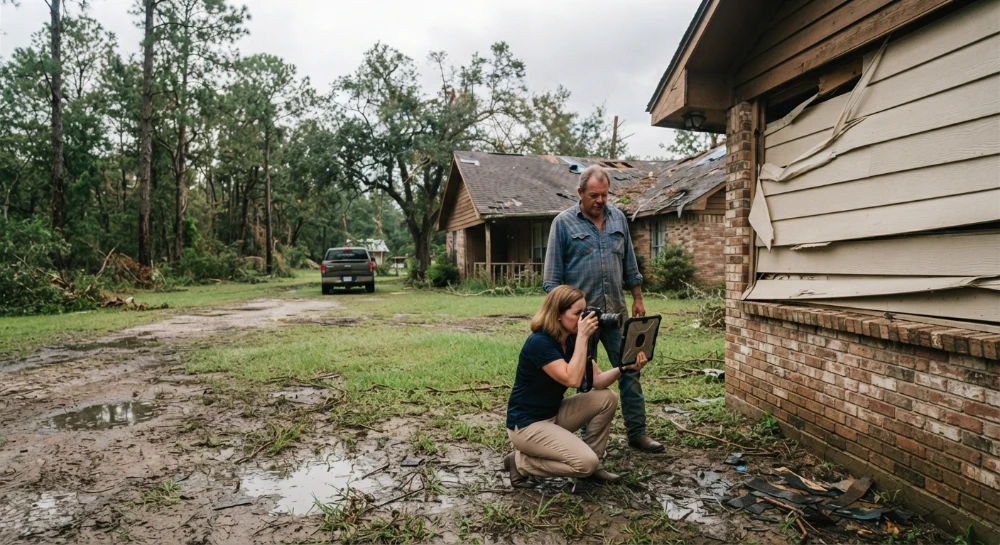
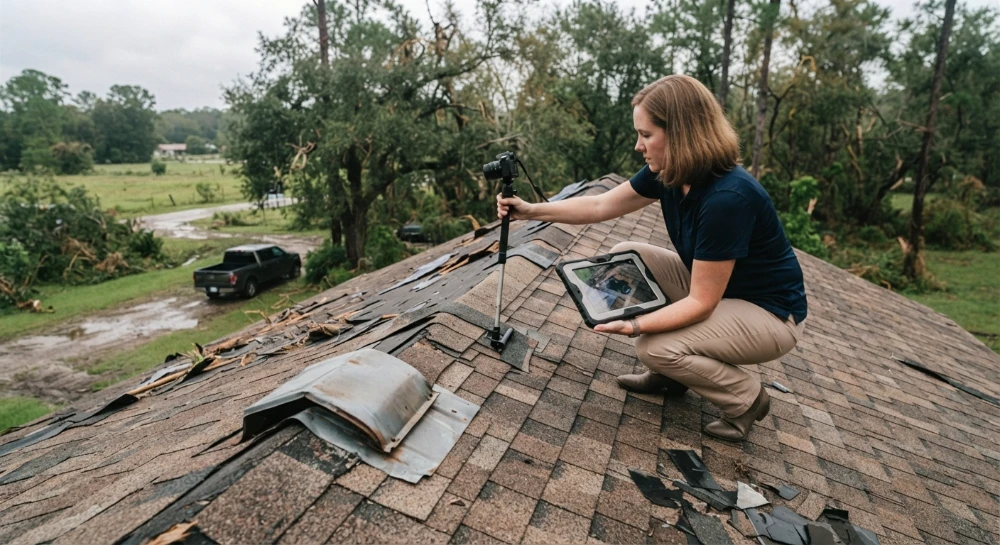
- Inspecting damaged areas
- Photographing and documenting visible conditions
- Reviewing roofing, siding, interiors, and other building components
- Comparing the carrier’s estimate against observed damage
- Identifying missing repair items
- Preparing or reviewing detailed scopes and estimates
- Organizing supporting invoices and documentation
- Communicating with the insurance carrier
- Preparing supplemental claim information when appropriate
- Negotiating disputed scope and pricing issues
Property owners who want a deeper explanation of the profession can also read what is a public adjuster and how public adjusters assist policyholders throughout a claim. This type of representation can be particularly useful after a widespread Liberty County storm, when insurance companies may be handling a large number of claims at the same time.
Property Damage Risks Unique to Hardin and Liberty County
Hardin is sometimes confused with Hardin County because of the city’s name. The City of Hardin is actually located in Liberty County, a Southeast Texas county extending through the Trinity River region between the Houston and Beaumont areas.
That location creates a distinctive combination of property risks.
Severe Thunderstorms and Damaging Wind
Thunderstorms can form quickly across Southeast Texas, bringing straight-line wind, lightning, hail, and heavy rainfall.
The risk is not theoretical. On July 22, 2026, the National Weather Service issued a severe thunderstorm warning for south-central Liberty County when a storm was located over Hardin. The warning identified potential wind gusts of approximately 60 mph and specifically warned of possible roof, siding, and tree damage.
Wind claims can involve considerably more than missing shingles. We frequently evaluate potential damage to:
- Shingle seals and roof edges
- Ridge caps
- Flashing
- Metal roofing components
- Fascia and soffits
- Siding
- Windows and screens
- Gutters and downspouts
- Fencing and exterior structures
- Interior ceilings and walls after rain intrusion
A storm does not have to remove an entire roof to create an expensive insurance loss.
Hurricanes and Tropical Storms
Hardin is inland, but inland does not mean protected from tropical weather.
Liberty County experienced significant effects from Hurricane Beryl in July 2024. National Weather Service reporting noted widespread downed trees in the county, power outages, a reported 57 mph gust near Dayton, and roughly two to four inches of rain across much of Liberty County, with locally higher amounts.
Liberty County also issued a disaster declaration for Hurricane Beryl, along with multiple severe-weather disaster declarations during 2024. For a deeper look at roof, interior, structural, water, equipment, and other losses that can follow a tropical system, see our guide to property damage after a hurricane.
For Hardin property owners, tropical systems may generate claims involving:
- Wind-damaged roofing
- Fallen trees or branches
- Damaged exterior components
- Wind-driven rain
- Interior water intrusion
- Wet insulation and drywall
- Commercial roof damage
- Business interruption issues
- Damage to detached structures
Determining whether water entered because of covered storm damage can become particularly important when a claim involves both wind and water.
Heavy Rain and Flood Exposure
Liberty County’s current FEMA-approved hazard mitigation planning specifically includes the City of Hardin, and the county plan contains flood-depth mapping for Hardin. The county is also developing a countywide master drainage plan focused on existing flood risks and long-term mitigation.
Insurance coverage for water depends heavily on the source. Surface flooding is different from water entering through a storm-created roof opening, a burst pipe, an appliance failure, or another covered cause.
That distinction is why documentation matters. A public adjuster can help determine how the physical evidence and policy language relate before damage is incorrectly grouped into a category that may have different coverage.
Tornado and High-Wind Risk
Southeast Texas thunderstorms can also produce rotating storms, tornado warnings, and intense wind events. Even when a tornado does not directly strike Hardin, severe convective storms can create localized damage that looks very different from one property to another.
A house on one side of town may have little visible damage while a building only a short distance away has lifted shingles, damaged metal components, fallen limbs, or water intrusion.
Winter Freeze Claims
Hardin’s Gulf Coast-influenced climate is generally warm, but severe winter events can still create damaging freezes. Plumbing lines, exterior fixtures, water heaters, commercial systems, and poorly insulated piping may be vulnerable during prolonged cold.
Freeze claims can become complicated once water travels from the original pipe failure into flooring, walls, cabinets, ceilings, insulation, or adjoining rooms.
Common Insurance Claims in Hardin
Hail Damage Claims
Hail damage is often less obvious than homeowners expect. A roof may remain in place while individual shingles, metal components, vents, gutters, window screens, or siding sustain impact damage.
A thorough hail claim inspection may evaluate:
- Asphalt shingles
- Metal roofing
- Roof vents
- Flashing
- Gutters
- Downspouts
- Soft metals
- Window screens
- Exterior cladding
- HVAC components
- Fencing and accessories
Problems often develop when an insurance estimate acknowledges some hail impacts but does not include the complete repair scope.
If hail has affected your Hardin property, our hail damage roof insurance claim guide explains how roof damage is documented, what insurers may look for, and what property owners should consider during the claim process.
Water Damage Claims
Water claims in Hardin can originate from several sources:
- Burst plumbing lines
- Water-heater failures
- Appliance supply lines
- HVAC drainage issues
- Overflowing fixtures
- Roof leaks
- Storm-created openings
- Wind-driven rain
Visible water is only part of the loss. Moisture may migrate under flooring, behind cabinets, into insulation, through drywall, or between levels of a building.
Documentation should address both the origin of the water and the extent of resulting damage. When the scope or cause of loss becomes disputed, a water damage public adjuster can help document damaged materials, review the carrier’s estimate, and present supporting claim information.
Fire and Smoke Damage Claims
Fire claims can involve much more than burned building materials.
A significant residential or commercial fire may require evaluation of:
- Structural damage
- Smoke contamination
- Soot
- Electrical systems
- HVAC systems
- Contents
- Furniture
- Interior finishes
- Debris removal
- Temporary living arrangements
- Business equipment
- Lost or damaged inventory
Smoke can travel throughout a building even when flames remain concentrated in one area. That makes proper scoping essential. For larger losses involving structural damage, smoke, soot, contents, and additional living expenses, learn how a fire insurance adjuster can help a policyholder document and manage the claim.
Storm Damage Claims
A strong Hardin thunderstorm can produce several damage mechanisms at once.
Wind may affect the roof. Rain may enter afterward. A tree limb may damage another part of the structure. Power disruption may affect equipment. Interior materials may then become wet.
Instead of treating every visible symptom as an isolated problem, we evaluate how the complete loss occurred and how the resulting damage should be presented under the policy.
Roof Damage Claims
Roof claims are among the property claims most likely to develop scope disputes.
Common disagreements include:
- Repair versus replacement
- Number of damaged shingles
- Wind versus wear and tear
- Hail impact identification
- Flashing replacement
- Roofing accessories
- Underlayment
- Drip edge
- Interior leak damage
- Matching issues
- Code-related repair requirements where applicable
Roof losses often become disputed when the carrier and property owner disagree about repairability, replacement, quantities, or omitted components. Our guide on hiring a public adjuster for a roof claim explains how these disputes can be evaluated. A carrier estimate may initially appear detailed while still omitting components required to complete the actual repair.
Commercial Property Claims
Hardin remains closely tied to the agricultural and small-business character described by the city, with local businesses and services concentrated around the community’s primary roadways. The town developed historically around railroad activity, agriculture, and the Hardin oilfield.
TX Public Adjusting assists commercial policyholders with losses involving:
- Retail properties
- Offices
- Agricultural-related buildings
- Warehouses and storage facilities
- Churches
- Multifamily properties
- Restaurants
- Commercial roofing systems
- Inventory
- Equipment
- Interior build-outs
Commercial losses often involve more documentation because the claim can affect the building, business personal property, equipment, inventory, and ongoing operations at the same time.
Hardin Areas and Community Corridors We Serve
Hardin is a small community and does not have the large, formally branded neighborhood system found in Houston, Dallas, or other major cities. Creating artificial neighborhood names would not accurately represent the area.
Instead, local property owners tend to identify locations through familiar roads, schools, community facilities, and nearby rural areas.
Our Hardin public adjuster services extend throughout:
- Central Hardin near State Highway 146 and FM 834
- Properties surrounding the Hardin ISD campuses
- Residential areas extending along the SH 146 corridor
- Rural homes and acreage around the city limits
- Properties west of town toward the historic Hardin oilfield area
- Homes and businesses south toward Liberty
Community anchors include Hardin City Hall, the Hardin Community Center, and the Hardin ISD campuses. Hardin High School is located along FM 834, reinforcing that corridor’s role as a recognizable center of local activity.
That smaller-town development pattern also means storm damage can affect a wide mix of construction: traditional single-family homes, rural properties, metal outbuildings, commercial roofs, agricultural structures, and older buildings that may respond differently to wind, hail, and moisture.
Why Insurance Claims Become Underpaid
An insurance company does not necessarily have to deny a claim for the property owner to have a problem.
Many disputes begin with an approved claim that simply does not contain the complete repair scope.
Missed Damage
A short inspection may document the most obvious damage while overlooking other affected components.
Examples can include roof accessories, siding, gutters, flashing, interior moisture, insulation, trim, or damage concealed behind finished materials.
Scope Omissions
A repair estimate is more than a price.
It is a list of the work required to return damaged property to its covered pre-loss condition. When necessary tasks are left out, the total can be substantially lower even if the individual prices appear reasonable.
Depreciation Issues
Many policies calculate depreciation on damaged materials.
Understanding whether depreciation is recoverable, when it may be recovered, and which policy conditions apply can affect the amount ultimately available for repairs.
Low or Incomplete Estimates
The carrier’s estimate and the contractor’s real-world repair scope may not match.
When that happens, the answer should not simply be to choose the cheapest number. The underlying scope needs to be compared line by line so the disagreement can be documented.
Documentation Problems
Insurance companies evaluate evidence.
Poor photographs, missing invoices, unclear timelines, incomplete inventories, and inconsistent descriptions can weaken an otherwise legitimate claim. Our role is to organize the loss into a documented claim package that clearly explains what happened and what covered repairs are being requested.
Our Public Adjusting Process
Step 1 – Claim Review
We begin by discussing what happened, when the damage occurred, whether a claim has already been filed, and what the insurance company has done so far.
If you have already received an estimate, payment, reservation-of-rights letter, or denial, we review those documents as part of the initial evaluation.
Step 2 – Property Inspection
We inspect the affected property and document relevant damage.
Depending on the loss, that can include roofing, exterior components, interior rooms, structural materials, contents, or commercial building systems.
Step 3 – Documentation and Scope Development
Next, we organize the evidence.
That may include photographs, measurements, inventories, estimates, invoices, reports, mitigation records, and other supporting material needed to explain the claim.
Step 4 – Carrier Communication and Negotiation
TX Public Adjusting communicates with the insurance carrier regarding the documented loss and addresses legitimate differences involving scope, quantities, pricing, or other claim issues.
When an insurance estimate leaves out covered damage, we present supporting documentation rather than simply arguing that the amount should be higher.
Step 5 – Settlement and Claim Resolution
We continue working through the claim toward a settlement supported by the policy and documented damage.
Additional damage may sometimes become visible once repairs begin. When appropriate and permitted by the policy and claim circumstances, supplemental documentation can be prepared to address those newly identified conditions.
A Hardin Claim Deserves More Than a Generic Storm Inspection
Hardin’s location creates a different risk profile from West Texas, North Texas, or even communities directly along the coast.
Here, property owners deal with the overlap of Southeast Texas thunderstorms, heavy rainfall, tropical systems, wind exposure, occasional hail, rural drainage considerations, tree damage, and aging roofs.
The difference matters.
For example, consider a home near the SH 146 corridor after a severe thunderstorm. A carrier may identify several wind-damaged shingles. But the complete claim may also require investigation of ridge materials, vents, flashing, gutters, ceiling staining, attic insulation, or rain entering through a storm-created opening.
The visible roof damage is only the beginning of the investigation.
That local storm context is one reason a detailed property damage claim in Hardin should be evaluated as a complete loss rather than a collection of isolated repair items.
Concerned that something was missed? Request a Free Claim Review from TX Public Adjusting before accepting an incomplete scope as the final word on your loss.
Why Choose TX Public Adjusting
Licensed Texas Public Adjuster
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839.
We focus on Texas property insurance claims and the types of losses Texas property owners regularly encounter.
We Represent Policyholders
A public adjuster works for the insured property owner.
We do not represent the insurance carrier when handling your claim. That independent role allows us to focus on documenting your covered loss and protecting your interests throughout the adjusting process.
Residential and Commercial Experience
Our team has reviewed thousands of residential and commercial claims across Texas.
That experience includes roofing systems, water losses, fire damage, storm claims, interior repairs, contents, and complex commercial losses.
Detailed Claim Documentation
A strong claim requires evidence.
We focus heavily on photographs, measurements, repair scope, estimates, supporting documents, and clear communication with the carrier.
Texas-Focused Experience
Hardin property losses are not evaluated in a vacuum.
Understanding Texas construction, weather patterns, roofing systems, regional storm events, and the insurance claim process helps us identify issues that a rushed inspection may overlook.
Free Initial Claim Review
You can speak with us about the claim before deciding how to proceed.
There are no upfront fees for the initial review.
Areas We Serve Near Hardin
TX Public Adjusting provides insurance claim assistance throughout Hardin and surrounding Liberty County communities, including:
- Liberty
- Ames
- Dayton
- Kenefick
- Daisetta
- Hull
- Devers
- Cleveland
- Rural areas throughout Liberty County
Property owners outside Hardin can also find local claim information through our Public Adjuster Liberty, TX and Public Adjuster Cleveland, TX service pages. The City of Hardin’s location along SH 146 places it immediately north of Liberty and within practical reach of communities across central and northern Liberty County.
Frequently Asked Questions About Public Adjusters in Hardin
What does a public adjuster in Hardin do?
A public adjuster represents the policyholder during a property insurance claim. We review the policy, inspect the damage, develop supporting documentation, review estimates, communicate with the insurance carrier, and negotiate claim issues on behalf of the property owner.
The key distinction is representation. The insurance company’s adjuster evaluates the loss for the insurer. TX Public Adjusting represents you.
When should I contact a public adjuster after storm damage in Hardin?
The best time is usually before important evidence disappears or major repairs make the original damage harder to document. You do not necessarily have to wait until the insurance company denies or underpays the claim.
If a severe storm damages your roof, allows water inside, knocks down trees, or affects multiple areas of the property, an early claim review can help establish the condition of the property while the evidence is fresh.
Can you help if my Hardin insurance claim has already been paid?
Potentially, yes.
An initial insurance payment does not always mean every covered component was included. We can review the carrier’s estimate, supporting documentation, and visible damage to determine whether legitimate scope items appear to have been omitted.
Your policy, deadlines, prior claim activity, and individual circumstances still matter, so the first step is reviewing the actual documents.
What if my insurance company says my roof damage is wear and tear?
Wear-and-tear disputes are common in Texas roof claims.
The question is not simply whether a roof is older. The relevant issue is whether a covered event caused direct physical damage and what the policy provides for that loss. Photographs, storm information, roof conditions, repairability, and inspection findings may all become important.
Does homeowners insurance cover flooding in Hardin?
Standard property policies often treat surface flooding differently from many other types of water loss, so the source of the water must be identified before assuming coverage.
Water entering through storm-damaged roofing, a plumbing failure, or another covered cause may be treated differently from rising surface water. A public adjuster can review the loss and policy, but coverage always depends on the specific facts and insurance contract.
Can you handle Hurricane or tropical-storm claims in Hardin?
Yes. Hardin is inland but remains exposed to damaging wind and rainfall from Gulf Coast tropical systems. Liberty County experienced significant wind, tree, power, and rainfall impacts during Hurricane Beryl in 2024.
We assist with documented covered losses involving roofing, exterior damage, wind-driven rain, interior water intrusion, contents, and commercial property.
Do you handle commercial insurance claims in Hardin?
Yes.
TX Public Adjusting works with commercial property owners, landlords, businesses, churches, warehouse operators, agricultural-related properties, and other insured organizations. Commercial claims may involve the structure as well as equipment, inventory, tenant improvements, and other covered property.
How do I know if my insurance settlement is too low?
Start by comparing the carrier’s estimate with the actual work required to repair the property.
Warning signs can include missing rooms, missing roof components, unexplained quantity differences, unusually limited repair areas, omitted water damage, or a contractor scope that is substantially broader than the carrier’s estimate. A professional claim review can help identify why the numbers differ.
Is it too late to hire a public adjuster after the claim has been open for months?
Not necessarily. Public adjusters are sometimes hired after an initial payment, during supplemental negotiations, or after a dispute develops. Our guide explaining when is it too late to hire a public adjuster covers this issue in greater detail. However, policy deadlines and Texas insurance requirements can affect what options remain. Waiting longer can also make physical evidence harder to preserve.
Have the claim reviewed as soon as you suspect there may be a problem.
How much does it cost to have TX Public Adjusting review my Hardin claim?
The initial claim review is free, with no upfront fee for us to evaluate whether the circumstances may justify public-adjusting assistance.
If you decide to retain TX Public Adjusting, the fee structure and contract terms are explained before representation begins so you understand the arrangement before signing anything.
Get a Free Hardin Insurance Claim Review
A damaged home or business deserves a complete evaluation—not an assumption that the first insurance estimate captured everything.
If your Hardin property has suffered hail, wind, roof, water, fire, hurricane, storm, or commercial property damage, TX Public Adjusting can review the claim and help you understand your options.
TX Public Adjusting
Rise Public Adjusting LLC
Texas Public Adjuster License #3356839
- Free Claim Review
- No Upfront Fees
- Licensed Texas Public Adjuster
- Residential & Commercial Claims
- Independent Policyholder Representation
- Serving Hardin and communities throughout Liberty County
Contact TX Public Adjusting today and request your Free Claim Review.