

Property damage in Barker can turn into a difficult insurance claim quickly. Hail can bruise shingles and damage soft metals, Gulf Coast storms can send strong winds through western Harris County, plumbing failures can affect multiple rooms, and periods of extreme rainfall can create water-related losses that require careful investigation. A Public Adjuster in Barker, TX can help you document the damage, review the insurance company’s estimate, and present a more complete claim when important items have been missed or underpaid.
TX Public Adjusting represents homeowners, commercial property owners, landlords, and other policyholders—not insurance companies. We inspect property damage, review claim documents and estimates, prepare supporting documentation, and communicate with the carrier throughout the claim process.
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839. Our team has experience reviewing thousands of residential and commercial property claim files throughout Texas.
If your Barker property has suffered hail, roof, wind, water, fire, storm, or other covered damage, contact TX Public Adjusting for a Free Claim Review. There is no upfront fee to have us review the circumstances of your claim and explain the available next steps.
Property Claims in Barker Have a Distinct West Harris County Risk Profile
Barker is not simply another name for Houston. It is an unincorporated community in western Harris County located along the I-10/Katy Freeway corridor, roughly between Houston and Katy. The community grew around the Missouri-Kansas-Texas Railroad in the late 1800s, and Barker-Clodine Road still reflects the area’s local identity.
That location creates a combination of property risks that deserves its own discussion.
Barker sits near the Barker Reservoir watershed, an important part of the regional flood-control system. The reservoir receives drainage from a 126-square-mile watershed, including Upper Buffalo Bayou and Mason Creek. During major rainfall events, drainage conditions throughout this part of Harris County can become a significant concern. Flood exposure varies considerably by individual property, elevation, drainage system, and policy, so water losses in Barker should be evaluated according to both the source of the water and the actual insurance coverage involved.
At the same time, Barker properties remain exposed to the broader weather patterns of southeast Texas: severe thunderstorms, hail, damaging wind, tropical systems, wind-driven rain, lightning, and occasional freezes.
That combination can produce claims involving more than one building component. A storm that initially appears to have caused only roof damage may also affect gutters, flashing, vents, fencing, windows, siding, interior ceilings, insulation, or commercial equipment.
A detailed claim review looks beyond the first visible problem.
Why Property Owners Hire a Public Adjuster in Barker
The insurance company sends an adjuster to investigate the loss on behalf of the carrier. A public adjuster works on the policyholder’s side of the claim.
That distinction becomes especially important when the insurance company’s estimate does not reflect what the property owner sees on the building.
A Public Insurance Adjuster in Barker can assist with situations such as:
- A roof claim that was approved only for minor repairs
- Hail damage that was classified as wear, aging, or cosmetic damage
- Interior water damage where portions of the repair scope were excluded
- A wind claim where exterior and interior damages were separated incorrectly
- A fire claim involving structure, contents, smoke, or additional living expenses
- A commercial loss involving roofing, inventory, equipment, tenant spaces, or business operations
- A claim that remains delayed or difficult to move forward
- A settlement estimate that appears significantly lower than contractor pricing
- A denied or partially denied claim that deserves closer review
Our role is to determine what happened, identify the covered damage that can be documented, compare the carrier’s position with the actual condition of the property, and prepare the claim in an organized way.
Barker Storm Risks and Property Damage
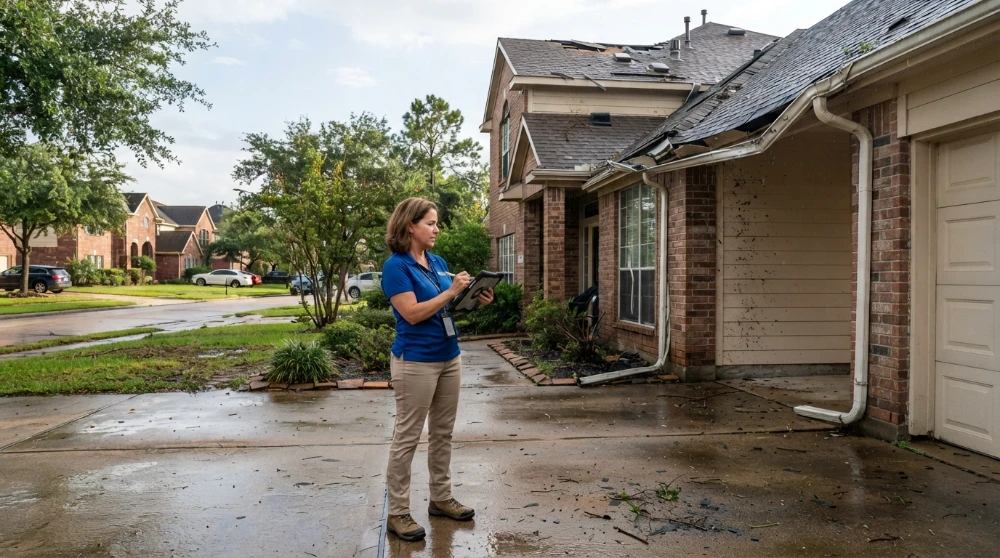
Barker’s location in western Harris County makes storm-related claims particularly relevant.
Heavy Rain and Barker Reservoir Conditions
The Barker Reservoir is a defining part of this area. It was constructed with Addicks Reservoir as part of the region’s flood-risk-management system and controls releases into Buffalo Bayou. During extreme rainfall, reservoir levels and surrounding drainage conditions can become major concerns.
Harris County records show that major rainfall events have affected the Barker and Addicks watersheds before. During the April 2016 floods, portions of the Upper Cypress Creek, Addicks, and Barker watersheds received 13 to 17 inches of rainfall within approximately 12 hours. Hurricane Harvey later demonstrated just how severe reservoir-related flooding can become during an exceptional event.
For an insurance claim, however, the source of the water matters. Surface flooding, wind-driven rain, roof openings, plumbing failures, overflowing fixtures, and storm-related water intrusion can be treated differently under a policy. Standard homeowners or commercial property insurance should not automatically be assumed to cover flood damage.
We review what caused the loss before attempting to define the claim.
Hail Damage
Hail can damage asphalt shingles without creating an obvious hole in the roof. A Barker homeowner may first notice granule loss, bruising, dents to vents or gutters, damaged window screens, or water staining after a later rain.
A hail inspection should consider the entire roofing system rather than a few selected shingles.
Potential hail-related damage includes:
- Asphalt shingles
- Metal roofing
- Roof vents and flashing
- Gutters and downspouts
- Window screens
- Fencing
- Siding
- Garage doors
- HVAC fins and exterior equipment
Our Hail Damage Roof Insurance Claim Guide explains what property owners should document after a Texas hailstorm. The site’s existing hail content is also a priority claim cluster identified in the company’s strategy materials.
Wind and Tropical Storm Damage
Although Barker is inland from the immediate coast, hurricanes and tropical systems can still bring significant wind and rainfall into western Harris County.
Strong wind may lift shingles, loosen flashing, damage fences, break tree limbs, affect exterior cladding, or allow rain to enter through newly created openings. On commercial buildings, wind can also affect membrane systems, rooftop equipment, parapets, and drainage components.
Damage from a storm does not always stop at the roof line. Interior staining, wet insulation, drywall damage, flooring damage, and contents losses may all be connected to the same event.
Freeze and Pipe Damage
A hard Texas freeze can create a different type of claim. Frozen plumbing lines may burst behind walls, above ceilings, in attics, or inside commercial spaces.
By the time the water is discovered, the damage may involve drywall, cabinets, insulation, flooring, baseboards, electrical components, and personal property.
The visible water is only part of the scope.
Common Insurance Claims in Barker, TX
Hail Damage Claims
Hail claims are among the most common storm losses we review across Texas. The dispute often centers on whether the roof has functional storm damage, whether repair is sufficient, and whether the carrier’s estimate includes all related components.
TX Public Adjusting documents the roof and associated exterior damage, reviews the carrier estimate, and identifies items that may require additional evaluation.
Roof Damage Claims
A roof claim can involve much more than shingles.
Flashing, vents, underlayment, decking, ridge materials, gutters, drip edge, valleys, penetrations, and interior damage may all matter depending on the loss.
If your insurance company has approved only a partial roof repair or the estimate appears incomplete, see our Public Adjuster for Roof Claim guide.
Water Damage Claims
Water claims require careful documentation because cause and coverage are closely connected.
A Barker water-damage claim may result from a burst pipe, appliance connection, plumbing leak, roof opening, storm-created damage, or another covered event.
Documentation may need to include moisture readings, affected materials, mitigation records, photographs, invoices, and the repair scope. Learn more in our Water Damage Public Adjuster guide.
Fire and Smoke Damage Claims
Fire claims can become complicated because the loss may extend far beyond burned materials.
Smoke and soot can travel through HVAC systems and into rooms that were not directly touched by flames. Contents may require cleaning, restoration, testing, or replacement. Temporary housing or other additional living expenses may also become relevant under a residential policy.
Our team reviews fire losses from the perspective of the complete property claim. You can also read our Fire Insurance Adjuster guide.
Storm and Wind Claims
Severe thunderstorms can create overlapping wind, rain, hail, tree, roof, and exterior damage.
When several types of damage occur during one weather event, identifying the complete scope becomes especially important. The claim should connect documented damage to the reported date and cause of loss rather than treating each symptom as an unrelated repair problem.
Commercial Property Claims
The Barker and west Houston corridor includes residential communities alongside office, retail, warehouse, service, and industrial properties.
Commercial claims can involve larger roofs, specialized construction, tenant improvements, inventory, equipment, signage, business personal property, and complicated repair sequencing.
TX Public Adjusting handles both residential and Commercial Property Claims throughout Texas.
Why Barker Insurance Claims Become Underpaid
An underpaid claim does not always result from one major mistake. More often, several smaller omissions reduce the total scope.
Damage Was Missed During the Initial Inspection
A quick inspection may document the main roof surface but fail to account for flashing, gutters, accessories, siding, windows, fencing, or interior damage.
The Scope Does Not Match the Actual Repair
An estimate may include replacing one damaged component without accounting for the work required to remove, access, detach, reset, or restore surrounding materials.
Depreciation Creates Confusion
Property owners often receive estimates showing replacement cost, depreciation, actual cash value, deductible amounts, and recoverable depreciation.
Understanding those figures matters before deciding whether the insurance payment accurately reflects the claim.
Contractor Pricing and Carrier Pricing Differ
A contractor may identify work that does not appear in the insurance estimate. The difference should be evaluated item by item rather than assuming either estimate is automatically correct.
Documentation Is Incomplete
Insurance claims are evidence-driven.
Photographs, measurements, weather information, mitigation records, inventories, estimates, invoices, and other documentation can materially affect how clearly the loss is presented.
Already received a payment but believe something was missed? Contact TX Public Adjusting for a Free Claim Review before assuming the first estimate is the final word.
Our Public Adjusting Process in Barker
1. Claim Review
We begin with the facts.
We review the reported loss, policy information available to us, carrier correspondence, estimates, photographs, contractor documentation, payments, and any denial or coverage letters.
2. Property Inspection
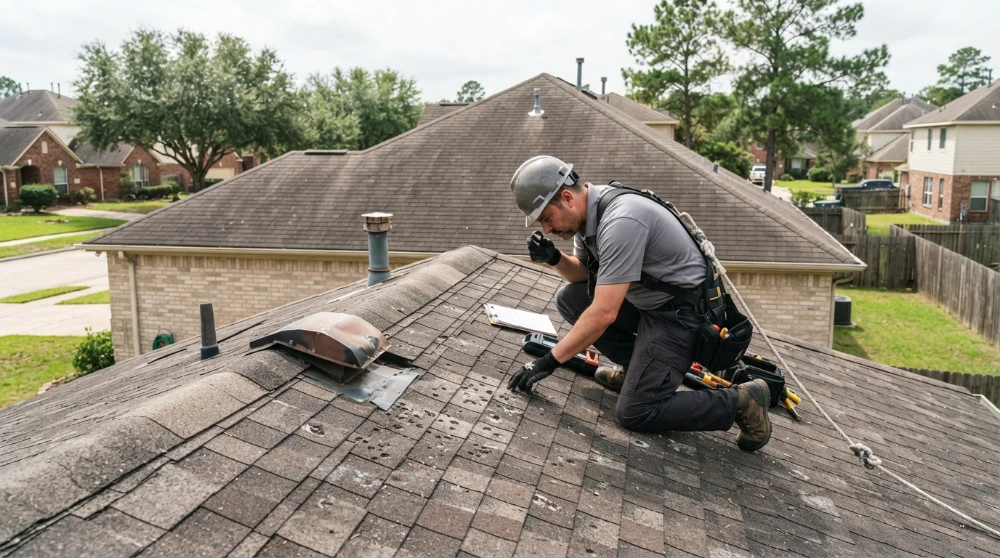
When appropriate, we inspect the Barker property to identify visible damage and determine which building components should be documented.
The inspection is based on the specific loss—not a generic checklist.
3. Damage Documentation
We organize photographs, measurements, estimates, inventories, supporting records, and other evidence needed to present the claim.
For larger residential or commercial losses, this stage can be extensive.
4. Scope and Estimate Review
We compare the carrier’s scope against the documented damage.
Missing line items, quantities, repair operations, associated components, and other differences are identified and supported where appropriate.
5. Carrier Communication and Negotiation
TX Public Adjusting communicates with the insurance company and presents the policyholder’s documented position.
Our objective is to pursue the settlement available under the policy based on the supported scope of covered damage. No public adjuster can guarantee a particular outcome, and every claim depends on its facts and policy terms.
Why Choose TX Public Adjusting for a Barker Property Claim?
TX Public Adjusting focuses on property insurance claims throughout Texas.
Licensed Texas Public Adjuster: Rise Public Adjusting LLC operates under Texas License #3356839.
Policyholder representation: We work for the insured property owner, not the insurance carrier.
Residential and commercial experience: Our experience includes homes, apartments, retail properties, warehouses, offices, restaurants, and other commercial losses.
Claim documentation experience: Our team has reviewed thousands of claim files involving roofing, hail, water, fire, wind, storm, and commercial property damage.
Texas-focused knowledge: Texas claims involve weather patterns, construction methods, policy provisions, and claim practices that require experienced review.
Free initial claim review: Property owners can have the circumstances of their claim reviewed before deciding whether representation makes sense.
Local Claim Help Around Barker
Barker’s local character is tied closely to west Harris County and the Katy Freeway corridor. The community developed around the railroad, and reminders of its earlier ranching history remain near Barker-Clodine Road. The LH7 Ranch historical site, associated with cattleman Emil Henry Marks, reflects the area’s history before the surrounding corridor became predominantly suburban and commercial.
George Bush Park is another major local reference point. The Harris County park covers roughly 7,800 acres inside Barker Reservoir and includes trails and recreational areas across the reservoir property.
We assist property owners around Barker and nearby west Harris County communities, including areas around:
- Green Trails
- Windsor Park Lakes
- Mayde Creek Farms
- Westlake Village
- Barkers Ridge
- Barker Cypress Road
- Barker-Clodine Road
- The I-10/Katy Freeway corridor
- Katy
- Addicks
- West Houston
- Cinco Ranch
- Cypress and surrounding communities
Because Barker is unincorporated, neighborhood names and mailing addresses can overlap with Houston and Katy-area identities. What matters for a property claim is the actual loss location, building condition, policy, and documented cause of damage—not simply the city name on the mailing address.
Property owners west of Barker can also visit our Public Adjuster Katy page, while property owners farther north can see Public Adjuster Cypress. Both URLs are confirmed in the existing site structure.
Frequently Asked Questions About Public Adjusters in Barker
What does a public adjuster in Barker do?
A public adjuster represents you, the policyholder, during a property insurance claim. That can include reviewing the loss, inspecting damage, preparing documentation, evaluating the carrier’s estimate, identifying omitted items, and communicating with the insurance company.
TX Public Adjusting does not work for your carrier. Rise Public Adjusting LLC represents insured property owners and holds Texas License #3356839.
When should I hire a public adjuster for a Barker property claim?
Property owners commonly contact us when the claim is large, the damage is difficult to document, the carrier estimate appears low, important repairs were omitted, the claim was partially denied, or communication with the insurer has become difficult.
You can also involve a public adjuster earlier in the claim when you want professional help preparing the loss from the beginning. If your claim is already underway, read When Is It Too Late to Hire a Public Adjuster?.
Can a public adjuster help with an underpaid roof claim in Barker?
Yes. An underpaid roof claim is a common reason property owners request a second review.
We can compare the carrier’s roof scope with the visible damage, roofing system, related components, measurements, photographs, and other available documentation. Depending on the facts, the review may identify additional items that should be presented to the insurer.
Does homeowners insurance cover flooding near Barker Reservoir?
Do not assume that it does. Standard homeowners policies commonly distinguish between flood or surface water and other forms of covered water damage. Flood insurance may be provided under a separate policy.
This distinction matters in Barker because the community is located near the Barker Reservoir watershed. The correct approach is to identify the actual source of the water and review the applicable policy before making assumptions about coverage.
Can you help after a Barker hailstorm if I do not see roof damage?
Yes. Hail damage can be difficult for an untrained property owner to identify from the ground.
Roof damage may involve bruised shingles, granule displacement, fractured materials, dented vents, gutters, flashing, screens, or other exterior components. If a significant hailstorm affected your property and you are concerned about damage, documentation should occur before repairs erase evidence of the loss.
Can TX Public Adjusting reopen or review an older claim?
Potentially. The answer depends on the age of the claim, policy requirements, prior payments, releases, deadlines, and other circumstances.
Do not assume an older claim can or cannot be addressed without reviewing the file. Send us the carrier estimate, settlement documentation, photographs, and correspondence, and we can evaluate the situation.
Do you handle commercial insurance claims in Barker?
Yes. TX Public Adjusting assists with residential and commercial property losses.
Commercial claims may involve roofing systems, exterior building components, interior improvements, inventory, equipment, tenant spaces, business personal property, and other covered property. Larger losses often require more documentation and coordination than a typical residential claim.
How long does a public adjuster claim take in Barker?
There is no single timeline. A straightforward residential claim may move more quickly than a large commercial loss involving multiple inspections, engineering questions, extensive contents damage, or coverage disagreements.
Our focus is on maintaining a documented claim process and responding to the carrier as the file develops rather than promising an artificial completion date.
What if the insurance company has already sent me a check?
Receiving an insurance payment does not necessarily mean you should stop reviewing the estimate.
Compare the payment and carrier scope with the actual work required. If you believe roofing, interior repairs, mitigation, materials, quantities, or other components were missed, a public adjuster can review the existing documentation and determine whether additional claim support may be appropriate.
How much does it cost to have TX Public Adjusting review my Barker claim?
The initial claim review is free, with no upfront fee for us to look at the circumstances and determine whether our services may be appropriate.
If you decide to hire TX Public Adjusting, the applicable fee arrangement and terms are explained in the written public adjusting agreement before representation begins.
Get a Free Barker Insurance Claim Review
If your home or commercial property has suffered hail, roof, wind, water, fire, storm, or other insured damage, you do not have to rely solely on the insurance company’s estimate to understand the scope of your loss.
TX Public Adjusting represents the policyholder.
Rise Public Adjusting LLC
Texas License #3356839
Residential & Commercial Property Claims
Contact TX Public Adjusting today for a Free Claim Review. There is no upfront fee for the initial review, and we can help you determine whether your Barker property claim deserves a closer look.