Property damage in Burkburnett can develop quickly when a North Texas thunderstorm brings large hail, straight-line winds, heavy rain, or tornado conditions across Wichita County. A roof that looked intact before the storm may suddenly have bruised shingles, damaged flashing, loosened metal panels, broken vents, or water entering through areas that were never inspected properly.
TX Public Adjusting helps homeowners, landlords, business owners, and commercial property managers document and negotiate insurance claims after serious property damage. As a licensed public adjuster in Burkburnett, we represent the policyholder—not the insurance company. Property owners who are unfamiliar with the process can learn more about what a public adjuster does before deciding whether professional claim representation makes sense.
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839. Our team has reviewed thousands of residential and commercial property claims across Texas, including complicated claims involving hail, wind, roofing systems, fire, water intrusion, contents, business property, and disputed repair scopes.
Need help with a Burkburnett insurance claim? Request a free claim review. There are no upfront fees for the initial review, and we will explain whether public adjusting services may be appropriate for your situation.
Insurance Claim Help for Burkburnett Property Owners
Burkburnett sits in northern Wichita County near the Red River, approximately ten miles north of Wichita Falls along Interstate 44. The city’s location in North Texas places homes and businesses in a region regularly exposed to severe thunderstorms, hail, damaging wind, tornado activity, lightning, and sudden temperature changes.
Those conditions can create several types of damage during the same event. Hail may affect the roof and exterior surfaces while wind lifts shingles, bends flashing, damages fencing, and allows rain into the structure. The resulting insurance claim may need to address far more than the most visible roof damage.
A public adjuster in Burkburnett evaluates the loss from the policyholder’s perspective. Our role is to investigate the property damage, organize the supporting evidence, review estimates and coverage documents, and present a detailed claim to the insurance carrier.
We can assist when:
- The insurance company’s estimate appears too low.
- Important damage was left out of the carrier’s scope.
- The adjuster approved a small repair instead of a larger replacement.
- A hail or wind claim was denied.
- Interior water damage was separated from the roof claim.
- Depreciation was applied incorrectly or not explained.
- The carrier requested more documents than the owner can reasonably organize.
- A commercial claim involves equipment, inventory, tenant improvements, or business interruption.
- A previously closed claim needs to be reviewed for missed damage.
Why Property Owners Hire a Public Adjuster in Burkburnett
Insurance policies place significant responsibilities on the policyholder. After a loss, the property owner may need to protect the property, report the claim, document damaged items, establish the cause of loss, provide repair estimates, prepare inventories, respond to information requests, and comply with policy deadlines.
The insurance company assigns an adjuster to investigate the claim for the carrier. A public adjuster works on the other side of the claim, representing the person or business that purchased the policy. Understanding the difference between a carrier representative and a policyholder representative is critical. Our guide to a public adjuster vs. independent adjuster explains who each adjuster works for and how their responsibilities differ.
Detailed Property Inspections
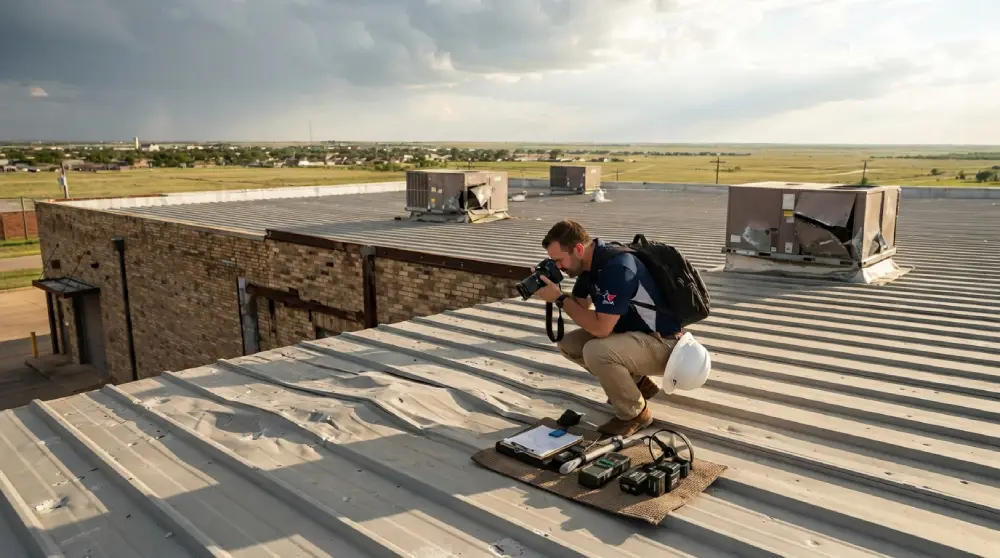
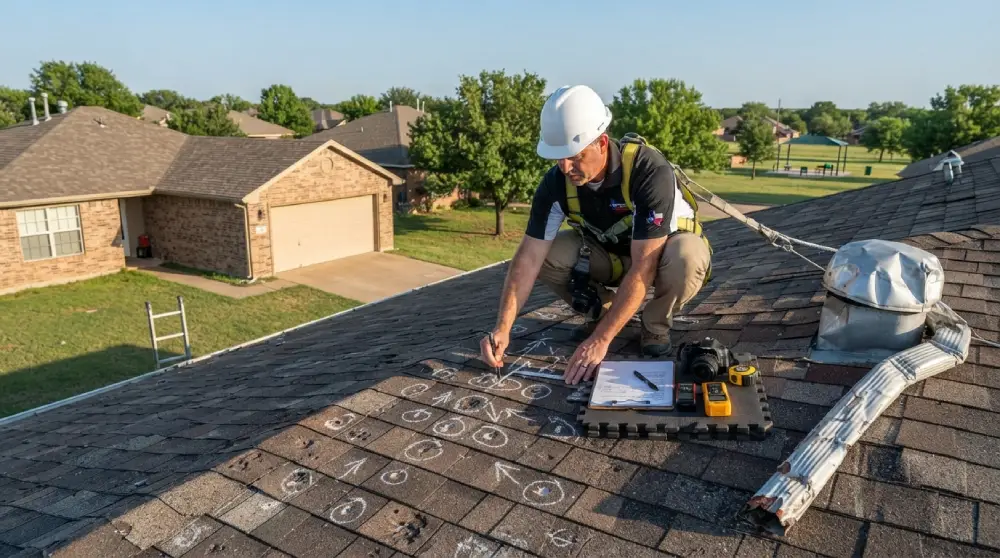
A proper inspection should go beyond a quick look at the roof. Depending on the loss, we may evaluate:
- Roofing materials and roof accessories
- Gutters, downspouts, fascia, soffits, and flashing
- Siding, stucco, brick, paint, and exterior finishes
- Windows, screens, doors, and overhead doors
- Fences, detached structures, and exterior equipment
- Attic areas, ceilings, insulation, and wall cavities
- Interior finishes affected by water
- Commercial roofing membranes and rooftop equipment
- Damaged contents, inventory, furnishings, or machinery
Independent Claim Documentation
Photos alone do not always explain the full repair requirement. Damage documentation may also involve measurements, repair estimates, room-by-room inventories, contractor information, moisture findings, material identification, code-related items, and a comparison between the visible damage and the carrier’s estimate.
Policy and Estimate Review
A low settlement is not always caused by an obvious denial. The issue may be hidden in a short estimate, an incorrect quantity, omitted labor, excessive depreciation, an unsupported repair assumption, or a coverage position that does not match the observed damage.
We compare the insurance company’s estimate with the conditions at the property and identify areas requiring clarification, correction, or additional documentation.
Claim Negotiation
Once the loss has been documented, TX Public Adjusting communicates with the insurance carrier and presents the policyholder’s position. This can include requesting a reinspection, submitting a supplemental estimate, answering claim questions, organizing supporting documents, and negotiating disputed portions of the loss.
Burkburnett Storm Risks and Property Damage
Burkburnett is known as “Boomtown, U.S.A.,” a name connected to the city’s early oil history. Today, the community includes established homes, newer residential construction, schools, churches, local businesses, rental properties, and commercial buildings serving residents along the I-44 corridor.
The same open North Texas landscape that gives the area its character can also expose buildings to fast-moving severe weather.
Hail Damage
Hail is one of the most significant property risks in and around Burkburnett. Property owners dealing with a recent storm can review our guide to filing and documenting a hail damage insurance claim. A severe storm struck the area in March 2023, generating specific warnings about roof insurance claims, and another substantial hail event affected the Wichita Falls–Burkburnett region in April 2026. Local reporting after the 2026 storm described a surge in roof inspections, repairs, and insurance activity.
Hail damage may include:
- Bruised, fractured, or missing asphalt shingles
- Granule loss that exposes the shingle surface
- Dents in metal roofing, gutters, vents, and flashing
- Cracked tile or specialty roofing products
- Damaged skylights and window components
- Dented siding and exterior mechanical equipment
- Punctures or fractured surfaces on commercial roofs
- Water intrusion that appears days or weeks later
Some hail marks are cosmetic. Others affect the performance and expected service life of the material. The distinction should be based on the specific product, policy language, installation, and observed damage—not a generalized statement made before a complete inspection.
Tornadoes and Straight-Line Wind
Burkburnett also faces tornado and severe-wind exposure. Regional risk assessments identify tornadoes and hail among the city’s more serious storm hazards.
Wind damage is not limited to buildings directly struck by a tornado. Straight-line winds can:
- Lift or crease shingles
- Break roof seals
- Displace metal panels
- Damage roof edges and perimeter flashing
- Pull gutters or fascia away from the structure
- Topple trees onto roofs, fences, and outbuildings
- Damage signs, awnings, and commercial façades
- Create openings that allow wind-driven rain inside
A claim may be underpaid when the carrier addresses only the most obvious missing shingles while overlooking damage to adjacent slopes, roof accessories, underlayment, or interior finishes.
Heavy Rain and Water Intrusion
Burkburnett’s overall flood exposure is lower than that of many coastal Texas communities, but local flooding and water intrusion can still occur during intense thunderstorms. One current risk model classifies the city’s long-term flood risk as minor while identifying a smaller number of properties with meaningful exposure.
Property owners should distinguish between rising surface water, plumbing losses, and rain entering through storm-created openings. These causes may be treated differently under the policy.
Common water-related losses include:
- Rain entering through wind-damaged roofing
- Water around windows and exterior doors
- Ceiling and wall damage after roof leaks
- Burst or frozen plumbing lines
- Water heater failures
- Appliance supply-line leaks
- HVAC condensation or drain problems
- Damage caused during fire suppression
- Mold or microbial growth following delayed drying
Winter Freeze Damage
North Texas properties are also vulnerable to sudden freezes. Pipes may rupture in exterior walls, attics, garages, vacant buildings, rental units, and commercial spaces that are not adequately heated.
A freeze claim can involve the failed plumbing component, water extraction, demolition, drying, insulation, drywall, paint, flooring, cabinets, electrical work, and damaged contents. An estimate that includes only the pipe repair may leave most of the loss unaddressed.
Fire and Smoke Damage
Residential and commercial fires can produce damage far beyond the burned area. Smoke, soot, heat, water, and firefighting activity may affect rooms that appear visually untouched.
A complete fire claim may involve:
- Structural repairs
- Smoke and soot cleaning
- Odor remediation
- Electrical and HVAC evaluation
- Roof or framing repairs
- Personal-property inventory
- Debris removal
- Temporary housing
- Commercial equipment and inventory
- Business-income documentation
Common Insurance Claims in Burkburnett
| Claim type | Damage frequently involved | Common claim dispute |
| Hail damage | Shingles, metal roofing, vents, gutters, siding, windows | Carrier calls damage cosmetic or recommends isolated repairs |
| Wind and tornado damage | Roofing, fences, trees, exterior finishes, water intrusion | Damage is divided into unrelated causes |
| Roof damage | Multiple slopes, decking, flashing, underlayment, accessories | Estimate covers only a small repair area |
| Water damage | Ceilings, drywall, insulation, floors, cabinets, contents | Source or duration of water is disputed |
| Fire and smoke | Structure, contents, soot, odor, HVAC, temporary living costs | Cleaning scope is too limited |
| Freeze damage | Plumbing, walls, flooring, cabinets, insulation | Estimate includes the pipe but not resulting water damage |
| Commercial property | Roofing, signs, equipment, inventory, tenant improvements | Business-related losses or code items are omitted |
Hail Damage Claims in Burkburnett
After a Burkburnett hailstorm, the first inspection can shape the rest of the insurance claim. When the initial scope is incomplete, later discussions may focus on correcting a low starting estimate rather than documenting the loss properly from the beginning.
The Texas Department of Insurance advises property owners to report hail or wind damage promptly and preserve documentation related to the claim.
Helpful steps include:
- Photograph visible exterior and interior damage.
- Protect openings from additional rain without making unnecessary permanent repairs.
- Save damaged materials when practical.
- Keep invoices for emergency work.
- Record when leaks or other symptoms first appeared.
- Avoid signing broad repair or assignment documents without understanding them.
- Request a complete copy of the carrier’s estimate and damage report.
- Compare the estimate with the actual repair requirements.
A public adjuster can become involved before the carrier inspection, after the estimate is issued, following a denial, or while a supplemental claim is being prepared.
Roof Damage Claims
Roof claims frequently become disputes over repairability rather than the existence of any damage at all. A public adjuster for a roof claim can review whether the carrier’s repair scope accounts for the complete roofing system and the conditions found at the property.
For example, an insurance adjuster may identify several damaged shingles and approve spot repairs. The property owner’s roofer may explain that the shingles are brittle, unavailable, mechanically bonded, or unable to be repaired without damaging surrounding materials.
Other commonly missed roof items include:
- Ridge and hip materials
- Starter course
- Valley components
- Drip edge and flashing
- Pipe boots and vents
- Detach-and-reset labor
- Steep or high-access charges
- Underlayment
- Decking where damaged or required
- Protection for landscaping and exterior areas
- Debris removal and disposal
- Code-related work when applicable
TX Public Adjusting reviews the complete roof system rather than treating each visible impact as an isolated repair.
Water Damage Claims
Water claims are highly dependent on the cause and timeline of the loss. A water damage public adjuster can investigate the affected areas, review the carrier’s scope, and organize documentation connecting the covered cause to the necessary repairs. The same room can show similar staining after a burst pipe, a long-term leak, wind-driven rain, surface flooding, or an HVAC overflow, but the coverage analysis may differ.
Our work may include documenting:
- The likely point of origin
- Areas affected by moisture
- Required demolition and access
- Drying and mitigation work
- Damage behind cabinets or built-in materials
- Flooring continuity
- Insulation and drywall replacement
- Personal-property damage
- Work performed by emergency vendors
- Repairs required after the source is addressed
Fire Damage Claims
Fire claims often involve multiple vendors, inspections, inventories, and living-expense questions. Property owners may be asked to make major decisions while displaced from the home or trying to reopen a business.
TX Public Adjusting can help organize the structural, contents, smoke, debris, and additional-expense portions of the claim so that each category is supported separately. Our Texas guide to a fire damage insurance claim explains how smoke, soot, heat, water, and firefighting activity can affect areas beyond the immediate burn zone.
Commercial Property Claims in Burkburnett
Burkburnett’s commercial properties include local retail spaces, restaurants, offices, churches, service businesses, warehouses, rental properties, and operations serving the nearby Wichita Falls and Sheppard Air Force Base area. The city is positioned along I-44 and near regional transportation routes connecting North Texas and Oklahoma.
Our commercial public adjuster services help business owners, landlords, churches, retailers, warehouse operators, and other commercial policyholders document complex property losses. Commercial claims may involve:
- Low-slope or metal roofing systems
- Rooftop HVAC equipment
- Signs, awnings, and exterior lighting
- Interior improvements
- Machinery and specialized equipment
- Inventory and stock
- Tenant and landlord responsibilities
- Loss of rents
- Extra expenses
- Business interruption
- Multiple buildings under one policy
Commercial buildings with layered asphalt roofing systems may also require specialized documentation because built-up roof repair can involve membranes, insulation, flashing, surfacing, drainage components, and rooftop equipment. Commercial estimates can become underpaid when the carrier focuses on building repairs but overlooks operational losses, specialty trades, access requirements, code issues, or tenant improvements.
Concerned that your Burkburnett commercial claim is incomplete? TX Public Adjusting offers a free review of the carrier’s estimate, inspection findings, and available claim documents.
Why Insurance Claims Become Underpaid
Damage Was Missed During the Inspection
Some insurance inspections are brief. Damage to secondary roof slopes, gutters, windows, fencing, attic areas, detached structures, or commercial equipment may not be included.
The Estimate Uses an Incomplete Scope
An estimate can contain reasonable prices and still be too low because entire repair operations are missing.
The Carrier Treats Related Damage Separately
Roof damage, interior water damage, and damaged contents may result from the same storm. Dividing them into unrelated issues can reduce or delay the claim.
Depreciation Is Misunderstood
Depreciation affects many replacement-cost claims. Property owners may not understand how much was withheld, which amounts may be recoverable, or what documentation is required after repairs.
Repairability Was Not Evaluated
A material may technically be replaceable but not practically repairable without disturbing adjacent materials. This is common with older shingles, discontinued products, brittle materials, continuous flooring, and integrated exterior systems.
Documentation Is Incomplete
A valid loss can still be difficult to resolve when photographs, measurements, inventories, mitigation records, invoices, and repair estimates are scattered or missing.
Our Public Adjusting Process
1. Free Claim Review
We begin by discussing what happened, when the damage occurred, what the insurance company has done, and what concerns you have about the claim.
We may review the policy, carrier estimate, payment letter, denial letter, photographs, contractor estimates, and prior correspondence.
2. Property Inspection
When appropriate, we inspect the property and identify visible conditions related to the reported loss. The inspection may include the roof, exterior, interior, detached structures, contents, or commercial areas.
3. Damage Documentation
We prepare the documentation needed to explain the claim. Depending on the loss, this may include photographs, measurements, estimates, inventories, timelines, invoices, and supporting reports.
4. Scope and Estimate Preparation
We build or review the repair scope based on the actual property conditions. We then compare our findings with the carrier’s estimate and identify omissions or disagreements.
5. Carrier Communication and Negotiation
TX Public Adjusting communicates with the insurance company, submits supporting documents, responds to claim questions, requests inspections when necessary, and negotiates disputed items.
6. Claim Resolution
We work to reach a properly supported settlement under the policy. No public adjuster can guarantee a particular outcome, but the claim should be evaluated using complete documentation rather than an incomplete first estimate.
Why Choose TX Public Adjusting
Licensed in Texas
TX Public Adjusting is operated by Rise Public Adjusting LLC under Texas License #3356839.
We Represent Policyholders
We do not work for the insurance company. Our responsibility is to document and present the property owner’s claim.
Residential and Commercial Experience
Our team has reviewed thousands of property claims involving homes, rental properties, churches, retail buildings, warehouses, offices, restaurants, multifamily properties, and other commercial risks.
Texas-Focused Claim Experience
Texas losses can involve hail, tornadoes, high wind, freeze damage, fire, water, and complex roofing systems. We focus on property claims within the state and understand the documentation these losses commonly require.
Detailed Scope Review
A claim is not simply a roof total or a single contractor quote. We examine the repair operations, quantities, related damage, depreciation, and supporting evidence.
Free Initial Claim Review
Property owners can speak with TX Public Adjusting before deciding whether representation makes sense. The initial claim review does not require an upfront fee.
Areas We Serve Near Burkburnett
TX Public Adjusting assists property owners throughout Burkburnett and surrounding portions of Wichita County.
Local service areas include:
- Downtown and City Center Burkburnett
- Residential areas surrounding Friendship Community Park
- Properties near Sheppard Road and the I-44 corridor
- Neighborhoods along the southern side of Burkburnett toward Wichita Falls
- Homes and commercial properties near the Red River corridor
- Cashion Community
- Wichita Falls
- Iowa Park
- Randlett, Oklahoma-area properties when the applicable claim and licensing requirements allow
- Other communities throughout Wichita County and North Texas
Friendship Community Park, the United Friendship Amphitheater, Boomtown Bay Family Aquatic Center, and River Creek Park Golf Course are among the city’s recognizable community destinations.
Frequently Asked Questions
What does a public adjuster in Burkburnett do?
A public adjuster represents the policyholder during a property insurance claim. The work may include inspecting the damage, reviewing the insurance policy and carrier estimate, preparing documentation, identifying missing claim items, communicating with the carrier, and negotiating the loss.
Unlike the insurance company’s adjuster, a public adjuster does not represent the carrier. TX Public Adjusting works for the homeowner, business owner, landlord, or commercial property owner who hires us.
When should I hire a public adjuster after a Burkburnett hailstorm?
You can contact a public adjuster immediately after discovering damage, before the insurance company’s inspection, after receiving a low estimate, or following a denial.
Early involvement can help preserve evidence and organize the claim correctly. However, an existing claim may still be reviewed if the carrier has already inspected the property or issued payment. Our guide explains when it may be too late to hire a public adjuster and why policy deadlines should be reviewed promptly.
Can you help if my roof claim was already denied?
A denied claim may be reviewed to determine the stated reason for the denial and whether additional evidence is available. We examine the denial letter, policy language, photographs, weather information, inspection findings, and repair documentation.
A review does not guarantee that the decision will change. It can, however, identify whether the claim was evaluated using complete and accurate information.
What if the insurance company approved only a roof repair?
We can review whether the proposed repair reflects the actual roof conditions. Relevant issues may include the number and location of damaged areas, the age and condition of the roofing material, product availability, brittleness, matching, installation method, and whether repairs can be completed without damaging surrounding materials.
The outcome depends on the policy and evidence at the property. The goal is to document the repair question properly rather than assume that either a spot repair or full replacement is automatically required.
Does homeowners insurance cover hail damage in Burkburnett?
Many Texas homeowners policies include wind and hail coverage, but deductibles, exclusions, cosmetic-damage provisions, roof schedules, and settlement terms vary. The Texas Department of Insurance recommends checking the policy and filing promptly when covered hail or wind damage is suspected.
Coverage should be confirmed using the actual policy issued for the property.
Can a public adjuster help with interior water damage from a roof leak?
Yes, when the water intrusion is connected to a covered loss. We can document affected ceilings, walls, insulation, flooring, cabinetry, contents, and other interior materials.
The carrier may still evaluate whether the roof opening was caused by wind or hail, whether the water entered suddenly, and whether any exclusions apply.
Do you handle commercial claims in Burkburnett?
Yes. TX Public Adjusting handles residential and commercial property claims. Commercial losses may involve roofing, equipment, signs, tenant improvements, inventory, business interruption, extra expense, or several insured structures.
These claims often require more documentation than a residential claim because the physical repairs and operational effects must be evaluated separately.
How are public adjusters paid?
Public adjusters commonly work under a written contingency-fee agreement based on the insurance recovery obtained through their services. The specific fee and terms should be explained before representation begins.
TX Public Adjusting provides a free initial claim review and does not charge an upfront fee for that review. Any representation terms are documented in the public-adjuster agreement.
Can you reopen a closed Burkburnett insurance claim?
A closed claim may sometimes be reviewed for supplemental or previously undocumented damage. Whether further action is available depends on the policy, loss date, prior payments, releases, applicable deadlines, and reason the claim was closed.
Property owners should not assume that “closed” always means the file can never be reconsidered, but they should seek a review promptly.
How long does a Burkburnett property claim take?
The timeline depends on the size of the loss, carrier response times, inspection scheduling, documentation, coverage questions, repair complexity, and whether the claim is disputed. The initial carrier response is only one part of the timeline. Property owners can review our explanation of how long an insurance adjuster has to contact you after a claim is reported.
A straightforward roof claim may move faster than a commercial fire or water loss involving inventories and business-income calculations. Our job is to keep the documentation organized and move the claim forward as efficiently as the circumstances allow.
Get a Free Burkburnett Claim Review
A low insurance estimate can leave a property owner trying to fund repairs that should have been evaluated as part of the claim. A denial can also feel final even when the inspection was incomplete or important evidence was never submitted.
TX Public Adjusting can review your Burkburnett hail, wind, tornado, roof, fire, water, freeze, or commercial property claim and explain the next step.
Contact TX Public Adjusting for a free claim review.
- Licensed Texas Public Adjuster
- Rise Public Adjusting LLC
- Texas License #3356839
- Residential and commercial claims
- Independent policyholder representation
- No upfront fee for the initial claim review