Property damage in Port Neches can become complicated quickly. A Gulf Coast storm may begin with wind damage to the roof, followed by wind-driven rain inside the building, damaged insulation, wet drywall, electrical concerns, and business interruption. When the insurance company’s estimate addresses only the most visible repairs, the property owner may be left trying to prove the rest of the loss.
TX Public Adjusting provides insurance claim help for residential and commercial property owners throughout Port Neches and Jefferson County. As a licensed Texas public adjuster, we represent the policyholder—not the insurance company—during the preparation, documentation, and negotiation of a property damage claim.
Our company operates as Rise Public Adjusting LLC under Texas License #3356839. We have experience reviewing thousands of residential and commercial claims involving storm, hail, roof, water, fire, and other covered property losses.
Concerned that your Port Neches insurance claim is incomplete, delayed, denied, or underpaid? Request a free claim review from TX Public Adjusting. There are no upfront fees.
Port Neches is a riverfront community in eastern Jefferson County, located along the Neches River in the Mid-County area of Southeast Texas. Its coastal-prairie setting and proximity to the Gulf make local properties vulnerable to hurricanes, tropical storms, heavy rainfall, flooding, tornadoes, hail, and damaging winds.
Why Property Owners Hire a Public Adjuster in Port Neches
An insurance company assigns an adjuster to investigate a claim on behalf of the carrier. A public adjuster performs a different role. We work for the policyholder and focus on presenting the full extent of covered damage under the applicable policy. Property owners who want a clearer explanation can review the differences between a public adjuster vs. independent adjuster.
Port Neches property claims often involve more than one type of damage. High winds may lift shingles or damage a metal roofing system while rain enters through openings and affects ceilings, walls, floors, equipment, or inventory. A commercial property can also experience lost operations, damaged mechanical systems, code-related repair requirements, and additional expenses that are not obvious during a brief inspection.
Property owners hire TX Public Adjusting when they need help with:
- Evaluating the insurance company’s estimate
- Identifying damage omitted from the original scope
- Documenting interior and exterior losses
- Reviewing repair quantities and pricing
- Organizing photographs, reports, inventories, and invoices
- Preparing a detailed claim presentation
- Communicating with the carrier and its representatives
- Addressing an underpaid, disputed, or denied claim
- Seeking supplemental payment for covered damage
Hiring a public adjuster does not guarantee a particular settlement. It does give the policyholder an experienced representative who understands insurance policies, damage documentation, repair scopes, estimating practices, and claim negotiations.
Port Neches Storm Risks and Property Claim Conditions
Port Neches is not an inland Texas community dealing with hail alone. Local claim conditions are shaped by the Neches River, the nearby Gulf Coast, Southeast Texas rainfall patterns, and the area’s exposure to tropical systems.
Hurricanes and Tropical Storms
Hurricanes and tropical storms can produce several overlapping causes of loss. Port Neches properties may experience roof damage, broken windows, damaged exterior cladding, fallen trees, fencing losses, water intrusion, electrical damage, and prolonged power outages.
After a major storm, determining how water entered the building can become one of the most important issues in a hurricane property damage claim. Wind-driven rain entering through storm-created openings may be treated differently from surface flooding or storm surge. Standard property policies commonly exclude flooding, which may require a separate flood insurance claim. The Texas Department of Insurance advises flood policyholders to notify their flood insurer promptly and notes that National Flood Insurance Program claims generally require a proof of loss within 60 days.
Our review examines the reported cause of loss, the physical damage, the policy language, and the carrier’s scope. We do not assume that all water damage should be grouped into a single category.
Heavy Rain and Flood-Related Damage
Water is part of daily life in Port Neches. The city’s northern border is formed by the Neches River, and community destinations such as Port Neches Park and the riverfront sit directly beside it.
Heavy rain can overwhelm drainage, expose weak roof areas, and allow water to enter around windows, doors, flashing, vents, and roof penetrations. Properties may suffer:
- Wet drywall and insulation
- Warped flooring or damaged subfloors
- Cabinet and millwork damage
- Mold-related remediation concerns
- Electrical system damage
- Damaged appliances or business equipment
- Contaminated contents
- Loss of use or interrupted business operations
Flood and water claims require careful documentation because different portions of the loss may fall under different policies, exclusions, endorsements, or deductibles.
Wind and Tornado Damage
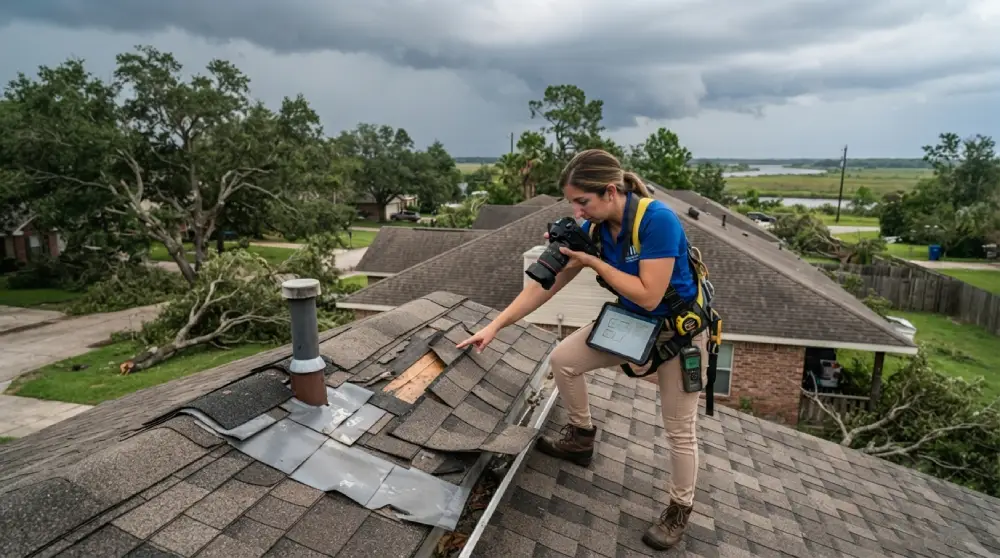
Strong straight-line winds and tornado-producing storms can damage roofing systems without removing the entire roof. Lifted shingles, opened seams, displaced flashing, damaged ridge components, bent metal panels, and loosened fasteners may be difficult to see from ground level.
Wind can also affect detached structures, exterior lighting, signs, canopies, fences, HVAC components, and commercial rooftop equipment. Port Neches has meaningful exposure to tornadoes and hurricanes in addition to moderate hail risk.
Hail Damage
Port Neches may be better known for tropical weather, but hail still creates significant roof and exterior claims. Hail can bruise asphalt shingles, fracture tile, dent metal panels, damage soft metals, break skylights, and affect gutters, vents, siding, and air-conditioning equipment.
A carrier inspection may acknowledge minor cosmetic damage while overlooking functional damage or the full number of affected roofing components. A detailed inspection should consider the roofing material, storm direction, impact pattern, age and condition of the system, and related collateral damage.
Industrial and Commercial Loss Exposure
Port Neches is part of an industrialized Southeast Texas corridor. Commercial claims in and around the city may involve warehouses, retail buildings, offices, restaurants, multifamily properties, service facilities, and industrial support operations.
These claims may include building damage as well as:
- Machinery or equipment losses
- Damaged stock and inventory
- Electronic and electrical systems
- Debris removal
- Temporary protection measures
- Business income interruption
- Extra expenses
- Tenant improvements
- Code-required repairs
Commercial claims often require more documentation than a residential loss. The policyholder may need coordinated estimates, inventories, financial records, lease information, repair schedules, and professional reports.
Common Insurance Claims in Port Neches
Hail Damage Claims
Hail damage insurance claims are not always straightforward because roof impacts may be difficult to identify from the ground. A roof may continue shedding water for a period before bruised shingles, fractured surfaces, or weakened components begin to fail.
TX Public Adjusting reviews the roof and related exterior components, compares the observed conditions with the carrier’s estimate, and documents omitted items when supported by the damage and policy.
Water Damage Claims
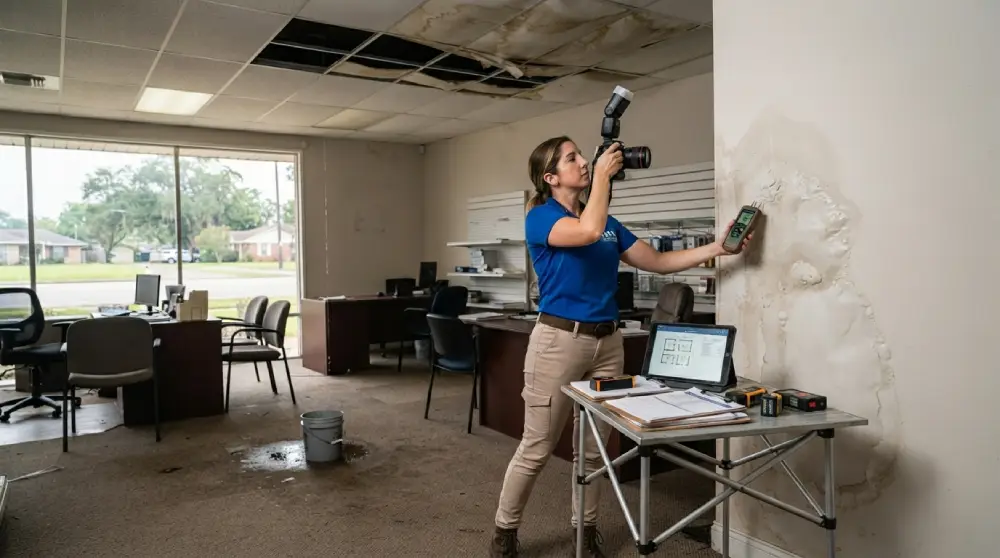
A water damage public adjuster can help document losses involving a leaking supply line, plumbing failure, roof opening, appliance discharge, or storm-related intrusion affecting several rooms and building systems. The visible stain on a ceiling may represent only a small portion of the actual loss.
A proper water damage scope may need to address drying, demolition, insulation, wall materials, flooring transitions, cabinetry, painting, contents, and temporary living or operating expenses.
Fire and Smoke Damage Claims
A fire insurance adjuster working for the policyholder evaluates more than the area touched directly by flames. Smoke, soot, heat, suppression water, and firefighting access can affect other portions of the structure.
We help document building damage, affected contents, debris removal, cleaning requirements, restoration questions, and additional expenses. Specialized testing or evaluation may be appropriate when smoke has entered insulation, ductwork, electronics, or concealed spaces.
Storm and Wind Damage Claims
Storm claims can involve multiple exterior elevations and interior rooms. We inspect the reported loss, organize evidence, and evaluate whether the insurance estimate reflects the full repair scope.
This can include roofing, siding, windows, doors, gutters, fencing, interior finishes, mechanical components, detached structures, and commercial equipment.
Roof Damage Claims
Hiring a public adjuster for a roof claim may help when the carrier’s estimate addresses only individual shingles or a small patch while omitting related roofing components.
Every roof claim is different. The required repair depends on the damage, roofing system, installation method, policy language, and applicable conditions.
Commercial Property Claims
Commercial property claims may involve larger buildings, specialized systems, numerous stakeholders, and income-related losses. Owners and managers also face pressure to protect tenants, customers, inventory, and daily operations.
Our commercial public adjuster services help Port Neches building owners document losses involving the structure, contents, equipment, inventory, and business operations.
Why Insurance Claims Become Underpaid
An underpaid claim does not always begin with an outright denial. Many disputes arise because the carrier accepts that damage occurred but values only part of the work.
Missed or Hidden Damage
A short inspection may not identify moisture behind walls, damage beneath roofing materials, affected insulation, compromised flashing, or water migration into adjacent rooms.
Scope Omissions
The estimate may include a primary repair but omit the work needed to complete it. Common omissions include demolition, disposal, access, detach-and-reset labor, surface preparation, painting adjoining areas, permits, overhead, and associated exterior components.
Low Repair Quantities or Pricing
Even when an item appears in the estimate, the quantity, labor allowance, or material price may not reflect the actual work required.
Depreciation Issues
Depreciation can significantly affect the initial payment. Property owners may also misunderstand whether depreciation is recoverable, what documents are required, and how deadlines apply.
Documentation Problems
Photographs alone may not establish the complete value of a claim. Strong documentation can include measurements, estimates, room-by-room scopes, inventories, receipts, reports, moisture records, repair proposals, and communications with the insurer.
Cause-of-Loss Disputes
This is especially important in Port Neches storm claims. A carrier may distinguish between wind-driven rain, pre-existing deterioration, plumbing discharge, rising floodwater, storm surge, or long-term seepage. The physical evidence and policy wording matter.
If the carrier’s estimate does not appear sufficient to complete covered repairs, request a free claim review from TX Public Adjusting before accepting the claim as final.
Our Public Adjusting Process
1. Claim Review
We begin by learning what happened, when the loss occurred, what the insurance company has done, and what concerns the property owner has.
We may review:
- The insurance policy and endorsements
- Carrier estimates
- Payment letters
- Reservation-of-rights or denial letters
- Photographs and videos
- Contractor estimates
- Inventories and receipts
- Prior claim communications
2. Property Inspection
Our inspection focuses on the reported damage and the parts of the property that may be connected to the loss. Depending on the claim, this can include the roof, exterior elevations, interior rooms, mechanical systems, contents, and commercial areas.
3. Damage Documentation
We organize the evidence needed to present the claim. This may include photographs, measurements, diagrams, repair estimates, inventories, professional evaluations, invoices, and supporting records.
4. Scope and Estimate Preparation
A claim estimate should describe the work required to return covered property to its appropriate pre-loss condition, subject to the policy. We compare our findings with the carrier’s estimate and identify supported differences in scope, quantity, or pricing.
5. Claim Presentation and Negotiation
TX Public Adjusting communicates with the insurance company and presents the documented basis for the requested claim adjustment. We respond to questions, address disputed items, and participate in inspections or claim discussions when appropriate.
6. Settlement and Claim Guidance
We keep the policyholder informed as the claim progresses. Our goal is to help the property owner understand the process, the carrier’s position, and the documentation supporting the claim.
Why Choose TX Public Adjusting
Licensed Texas Public Adjuster
TX Public Adjusting operates through Rise Public Adjusting LLC under Texas License #3356839.
Independent Policyholder Representation
We do not work for the insurance company. Our duty is to the property owner who hires us.
Texas Claim Experience
Our work is focused on Texas property claims, including the weather conditions and construction issues that affect Gulf Coast and Southeast Texas properties.
Residential and Commercial Knowledge
We assist homeowners, landlords, business owners, property managers, and commercial building owners.
Thousands of Claims Reviewed
Our experience reviewing thousands of claims helps us recognize common estimate omissions, documentation gaps, and scope disputes.
No Upfront Fees
A property owner can request an initial claim review without paying an upfront consultation fee. Any representation terms are explained before an agreement is signed.
Local Understanding
Port Neches is not interchangeable with Dallas, Austin, or West Texas. Local properties face a distinct combination of river proximity, tropical weather, intense rainfall, high winds, coastal claim issues, and commercial exposure.
Property Claim Help Throughout Port Neches
Port Neches is often described as a cohesive riverfront community rather than a city divided into numerous formally recognized neighborhoods. Local property owners identify areas by schools, parks, streets, riverfront destinations, and nearby communities.
We assist property owners near:
- Port Neches Park and the Neches River waterfront
- Oak Bluff
- Central Park
- Nall Street
- Magnolia Avenue
- Downtown and City Hall
- Port Neches-Groves school areas
- Residential streets near FM 365 and FM 366
- Commercial corridors leading toward Nederland and Groves
Port Neches Park, the riverfront, Neches River Wheelhouse, and Port Neches City Hall are familiar local landmarks. The community’s identity is closely tied to the river and the surrounding Mid-County area.
Areas We Serve Near Port Neches
TX Public Adjusting serves property owners throughout Jefferson County and surrounding Southeast Texas communities, including:
- Groves
- Nederland
- Port Arthur
- Beaumont
- Bridge City
- Central Gardens
- Lumberton
- Orange
- Vidor
- Sabine Pass
- Fannett
- Hamshire
A claim does not need to involve a total loss before a public adjuster can review it. We assist with significant roof, storm, water, fire, and commercial losses when documentation or valuation has become difficult.
Frequently Asked Questions
What does a public adjuster do for a Port Neches property owner?
A public adjuster represents the policyholder during a property insurance claim. The work may include reviewing the policy, inspecting the loss, documenting damage, preparing an estimate, communicating with the carrier, and negotiating disputed claim items.
This differs from the insurance company’s adjuster, who investigates the claim for the carrier. Our guide explaining what a public adjuster does provides a more detailed overview of policy review, inspections, documentation, estimating, and negotiation.
When should I contact a public adjuster after a Port Neches storm?
Contacting a public adjuster early may help preserve evidence and improve the organization of the claim. It is especially useful when the loss involves several rooms, a large roof, commercial property, substantial water intrusion, or overlapping wind and flood questions.
A public adjuster may also become involved after an initial payment when the carrier’s estimate appears incomplete. Property owners with an older or partially settled loss can also review when it is too late to hire a public adjuster.
Can you help if my Port Neches claim has already been paid?
Potentially. An initial payment does not always mean the claim is closed to further consideration. The policy, claim status, deadlines, prior documentation, release language, and remaining damage must be reviewed.
TX Public Adjusting can examine the existing estimate and explain whether supported supplemental items may remain.
Can a public adjuster help with a denied claim?
A denied claim can be reviewed to understand the carrier’s stated reason, the evidence available, and the relevant policy provisions. Some denials involve exclusions or late reporting, while others involve disagreements about the cause, date, or extent of damage.
A public adjuster is not an attorney and does not provide legal representation. When a dispute requires legal advice, the policyholder may need to consult a qualified insurance attorney.
Is hurricane flooding covered by homeowners insurance?
Standard homeowners policies generally do not cover rising floodwater or storm surge. Flood coverage is usually provided through a separate flood policy. Wind-created openings and wind-driven rain may involve different coverage questions.
Port Neches hurricane claims should be separated carefully by cause rather than treating every form of water intrusion as identical.
How do you document roof damage in Port Neches?
Documentation can include roof photographs, measurements, test areas, collateral damage, interior water staining, attic conditions, flashing, vents, gutters, metal components, and storm information.
The appropriate evidence depends on the roofing system and the nature of the loss. Asphalt shingles, standing-seam metal, exposed-fastener metal, tile, and commercial low-slope roofs require different evaluations.
Why is my insurance estimate lower than my contractor’s estimate?
The two estimates may use different quantities, labor assumptions, material pricing, repair methods, or scopes. The carrier may also omit work that the contractor believes is necessary to complete the repair.
We compare the estimates item by item and focus on differences that can be supported through physical evidence, policy provisions, repair requirements, and documentation.
Do you handle commercial property claims in Port Neches?
Yes. TX Public Adjusting assists with commercial building, contents, equipment, inventory, and business-related property claims.
Commercial losses may require financial documents, tenant information, equipment evaluations, specialized estimates, and business interruption records in addition to the building damage scope.
How much does a Port Neches public adjuster charge?
Public adjuster fees are typically based on the written representation agreement and applicable Texas requirements. The structure can depend on the type, timing, and status of the claim.
TX Public Adjusting provides a free initial claim review and explains the fee arrangement before representation begins. There are no upfront consultation fees.
How long does an insurance claim take?
The timeline depends on the size of the loss, carrier response times, inspection scheduling, document requests, coverage questions, contractor availability, and the extent of disagreement.
A straightforward roof claim may progress differently from a hurricane loss involving wind, water, contents, and business interruption. We keep clients informed and work to move documentation and negotiations forward efficiently.
Request a Free Port Neches Claim Review
You paid for insurance to protect your property. When a covered loss occurs, the claim should reflect the documented damage—not only the easiest items to see during the first inspection.
TX Public Adjusting helps Port Neches homeowners, business owners, landlords, and property managers prepare and negotiate property damage claims. We handle storm, hail, water, fire, roof, and commercial losses throughout Jefferson County and Southeast Texas.
Contact TX Public Adjusting for a free Port Neches claim review.
- Licensed Texas Public Adjuster
- Rise Public Adjusting LLC
- Texas License #3356839
- Residential and commercial claims
- Independent policyholder representation
- No upfront fees
The site’s strategy reports identify substantive, locally specific city pages and stronger links between city, claim-type, and educational content as key priorities.