Property damage in Magnolia can turn into a complicated insurance claim quickly. A severe thunderstorm can move through western Montgomery County with damaging wind and hail, a roof leak can spread moisture into insulation and drywall, or a burst pipe can affect several rooms before the water is shut off. For property owners dealing with a large, delayed, denied, or underpaid loss, working with a Public Adjuster in Magnolia, TX can provide experienced representation on the policyholder’s side.
TX Public Adjusting helps residential and commercial property owners document covered damage, review insurance estimates, prepare detailed claim scopes, and negotiate with insurance companies. We operate through Rise Public Adjusting LLC, Texas Public Adjuster License #3356839.
Magnolia sits in southwest Montgomery County, around the FM 1488 and FM 1774 corridors, with the larger Magnolia area extending into wooded acreage communities, established subdivisions, and rapidly developing residential areas. Those different property types create different insurance challenges—from hail-damaged composition roofs in newer subdivisions to wind, tree, and water losses on larger wooded properties.
Licensed Texas Public Adjuster | Residential & Commercial Claims | Free Claim Review
If your insurance company’s estimate does not appear to reflect the full extent of your damage, contact TX Public Adjusting for a Free Claim Review. No upfront fees to get started.
Why Property Owners Hire a Public Adjuster in Magnolia
A public adjuster represents the policyholder—not the insurance carrier.
That distinction becomes especially important when a property claim involves significant damage, multiple building components, disagreements over repair scope, depreciation questions, or a settlement that does not appear sufficient to complete necessary repairs.
Insurance companies have adjusters assigned to evaluate claims on behalf of the carrier. A public insurance adjuster in Magnolia approaches the loss from the property owner’s side.
Our work may include:
- Reviewing the insurance policy and applicable coverage
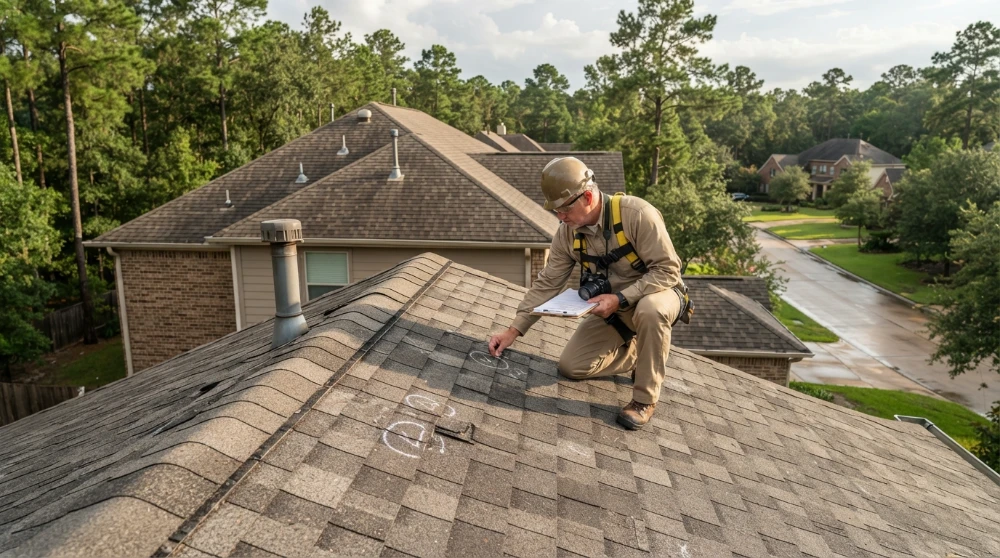
- Inspecting the damaged property
- Identifying visible and potentially overlooked damage
- Photographing and documenting the loss
- Reviewing the carrier’s scope and estimate
- Preparing detailed repair estimates
- Organizing supporting claim documentation
- Communicating with the insurance company
- Addressing scope disagreements and supplements
- Negotiating the covered property claim
Magnolia is different from a dense urban market. Properties may include newer subdivision homes, custom homes on acreage, equestrian properties, detached shops, barns, garages, commercial buildings, and heavily wooded lots.
Communities throughout the greater Magnolia area include Westwood, Mostyn Manor, High Meadow Ranch, Lake Windcrest, Thousand Oaks, Clear Creek Forest, Indigo Lake Estates, Magnolia Ridge, and Northgrove. Local real estate sources identify many of these among the area’s established and growing residential communities.
When a storm damages one of these properties, documenting only the most obvious roof problem may not tell the complete story.
Magnolia Weather Creates Real Property Claim Risks
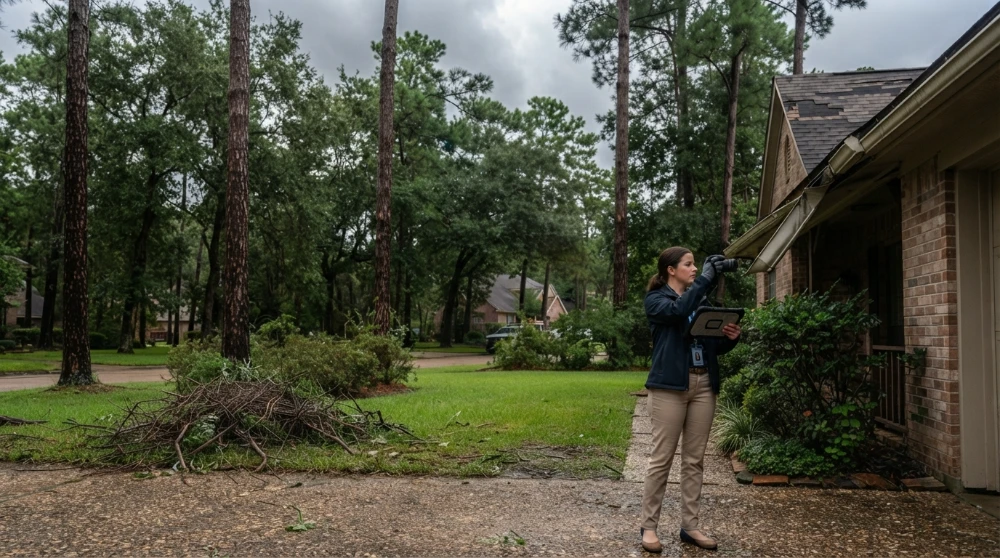
Magnolia’s location northwest of Houston exposes property owners to a mix of Gulf Coast moisture and inland severe-weather threats.
The risks are not theoretical. In August 2026, the National Weather Service issued a severe thunderstorm warning for a storm directly over Magnolia with 60 mph wind gusts and hail, noting the potential for damage to roofs, siding, and trees. Other recent storms affecting western Montgomery County have brought strong wind, heavy rainfall, lightning, and additional hail threats.
Severe Thunderstorms and Wind
Magnolia’s tall pines and mature tree cover are part of the area’s appeal, but they can also increase storm-loss exposure.
Strong thunderstorm winds may cause:
- Lifted or missing shingles
- Broken ridge caps
- Damaged flashing
- Fallen tree limbs
- Roof punctures
- Damaged fences and gates
- Detached structure damage
- Broken windows
- Siding damage
- Water intrusion through storm-created openings
A tree branch hitting a roof can create damage that extends beneath the surface. Water may enter decking, insulation, ceiling cavities, drywall, or electrical areas even when the exterior opening appears relatively small.
Hail Damage
Hail claims require careful inspection because impact damage does not always look dramatic from the ground.
Depending on the roofing material and storm intensity, hail can affect:
- Asphalt shingles
- Metal roofing
- Roof vents
- Gutters
- Downspouts
- Flashing
- Window screens
- Exterior siding
- HVAC components
- Fencing and outdoor structures
A carrier estimate may recognize certain damaged items while excluding others affected by the same storm.
Heavy Rain and Water Intrusion
Magnolia receives intense rainfall during thunderstorms and tropical-weather events. Wind-driven rain can enter around compromised roof coverings, flashing, windows, doors, and penetrations.
Water can then migrate farther than the original entry point.
A ceiling stain may be only the visible symptom. The full loss may involve insulation, framing, drywall, paint, flooring, cabinets, or electrical components.
Floodwater and rain entering through storm-created openings can also be treated differently under an insurance policy, making it important to determine how the water entered the building and what caused the damage.
Tropical Storm and Hurricane Effects
Magnolia is inland, but Gulf Coast hurricanes and tropical systems can still bring damaging winds and prolonged rainfall deep into Montgomery County.
Properties do not need to be directly on the coast to experience:
- Wind damage
- Fallen trees
- Roof openings
- Water intrusion
- Power-related losses
- Debris impacts
- Damage to detached structures
- Commercial interruption
The combination of wooded properties and long-duration winds can make post-storm inspections particularly important.
Winter Freeze and Pipe Losses
Southeast Texas freezes are less frequent than summer storms, but they can produce expensive claims when plumbing is not designed for prolonged cold.
Freeze-related losses may involve burst pipes in:
- Attics
- Exterior walls
- Garages
- Mechanical rooms
- Guest houses
- Commercial spaces
- Detached buildings
Once a pipe ruptures, water can spread through ceilings, walls, cabinetry, flooring, and personal property before the source is discovered.
Common Insurance Claims in Magnolia
Property claims in Magnolia can range from a single damaged roof to complex losses involving multiple structures and extensive interior damage.
| Claim Type | Damage We Commonly Review |
| Hail | Shingles, metal roofs, gutters, vents, siding, HVAC |
| Wind & Storm | Roofing, trees, fencing, windows, detached structures |
| Water | Drywall, insulation, flooring, cabinets, contents |
| Fire & Smoke | Structure, soot, HVAC, contents, odor, debris |
| Roof | Shingles, flashing, decking, underlayment, penetrations |
| Commercial | Buildings, equipment, inventory, tenant improvements |
Hail Damage Claims
A hail damage roof insurance claim should account for all covered damage—not simply the first damaged roof component identified during an inspection.
Our review may examine roof slopes, soft metals, vents, gutters, exterior finishes, mechanical equipment, and other storm-exposed components.
When repairability, matching, or replacement scope becomes disputed, detailed documentation becomes especially valuable. Property owners can also review our guide on how to document hail damage for an insurance claim before or during the claim process.
Water Damage Claims
Water claims often become complicated because damage continues to develop after the initial event. A water damage public adjuster can evaluate the documented cause of loss, affected materials, and differences between the carrier’s estimate and the actual repair scope.
A sudden plumbing failure or storm-created roof opening may affect:
- Flooring
- Baseboards
- Drywall
- Insulation
- Cabinets
- Electrical systems
- Personal property
- Adjacent rooms
Mitigation invoices and reconstruction scopes should also be reviewed carefully so the claim reflects the documented covered loss.
Fire Damage Claims
Fire losses are rarely limited to what burned. Working with a fire insurance adjuster who represents the policyholder can help identify structural, smoke, soot, contents, and other covered components of the loss.
Smoke and soot can travel through hallways, ceiling cavities, ductwork, insulation, and HVAC systems. Contents may require cleaning, restoration, or replacement. Structural materials may require evaluation even outside the immediate burn area.
A properly prepared fire claim may need to address:
- Structural repairs
- Smoke contamination
- Soot removal
- Contents damage
- Debris removal
- Electrical inspection
- HVAC cleaning
- Temporary living expenses when covered
Storm Damage Claims
Strong storms can affect several parts of a Magnolia property at once.
A single event might damage the roof, knock down fencing, break tree limbs, allow rain inside, and damage a detached shop or garage.
Treating each item separately without understanding the complete loss can create scope gaps.
Roof Damage Claims
Roof claims are among the most common property insurance disputes. A public adjuster for a roof claim can compare the carrier’s scope against the documented roof damage, measurements, repair requirements, and related property damage.
The issue is not always whether some damage exists. The disagreement may involve how much damage exists and what repairs are reasonably required.
Common disputes include:
- Repair versus replacement
- Number of affected slopes
- Shingle matching
- Flashing replacement
- Vent replacement
- Underlayment
- Decking
- Code-related items when applicable
- Depreciation
- Interior water damage related to the roof loss
Commercial Property Claims
Magnolia continues to grow while maintaining a mix of local businesses, retail properties, service companies, warehouses, restaurants, offices, churches, and other commercial facilities.
The city grew from its history as a lumber and agricultural shipping community and remains centered around important regional transportation corridors.
A commercial public adjuster may be especially useful when a Magnolia loss involves multiple buildings, equipment, inventory, tenant improvements, or business-income issues. Commercial claims can require significantly more documentation than residential losses because the claim may include:
- Building damage
- Roofing systems
- Business personal property
- Equipment
- Inventory
- Tenant improvements
- Debris removal
- Extra expense
- Business interruption when covered
- Multiple buildings or structures
Have an underpaid, delayed, or disputed property claim? TX Public Adjusting offers a Free Claim Review for Magnolia homeowners and business owners.
Why Insurance Claims Become Underpaid
An insurance settlement can appear detailed while still leaving significant repair items out of the scope. Hail losses can be particularly difficult when the carrier disputes the cause or extent of roof damage. If that happens, our guide explains what to do if your hail claim was denied.
Damage Was Missed
Carrier inspections can occur quickly, especially after widespread storms when adjusters are handling large claim volumes.
Items such as flashing, roof accessories, siding, interior moisture, insulation, detached structures, or damaged mechanical components may not appear in the initial estimate.
The Scope Is Incomplete
An estimate might include the primary repair while leaving out related work necessary to complete it properly.
For example, replacing storm-damaged roofing can involve more than shingles. Depending on the documented loss and policy, related work might involve vents, flashing, underlayment, gutters, or interior repairs.
Depreciation Creates Confusion
Replacement cost, actual cash value, recoverable depreciation, and nonrecoverable depreciation are different concepts.
Property owners sometimes receive an initial payment without realizing additional covered funds may depend on completing repairs or providing required documentation.
Pricing or Quantities Are Too Low
A claim estimate depends on measurements, quantities, labor assumptions, materials, and repair methods.
Small differences across dozens of line items can become substantial on a major loss.
Documentation Is Weak
A valid claim is easier to evaluate when the supporting file clearly connects the event, damage, repair scope, and claimed amount.
Photos alone may not answer every question.
Strong claim documentation can include:
- Photographs
- Measurements
- Damage diagrams
- Repair estimates
- Contractor information
- Mitigation records
- Contents inventories
- Receipts and invoices
- Relevant correspondence
- Supporting expert reports when appropriate
Our Public Adjusting Process
Every loss is different, but our objective remains the same: build a detailed, supportable claim file and represent the property owner throughout the process.
1. Claim Review
We begin by reviewing what happened, the current status of the insurance claim, and any estimates, payments, or correspondence already received.
If the carrier has already issued an estimate, we review it for potential omissions and discrepancies.
2. Property Inspection
We inspect the property with the claim in mind.
For a storm loss in Magnolia, that may mean examining roofing, exterior components, interior water intrusion, detached structures, and other affected areas instead of focusing solely on the most obvious damage.
3. Documentation and Scope Preparation
We organize the loss into a clear claim presentation supported by photographs, measurements, estimates, and other appropriate records.
Documentation is where many insurance disputes are won or lost.
4. Insurance Company Negotiation
TX Public Adjusting communicates with the insurer and presents documented differences in scope or valuation.
Our role is to advocate for the policyholder while working within the insurance policy and the documented facts of the loss.
5. Claim Settlement
We continue working through claim issues, supplemental documentation, and negotiations toward an appropriate settlement under the policy.
No public adjuster can guarantee a particular result. What we can provide is experienced claim preparation, detailed documentation, and independent representation.
Why Choose TX Public Adjusting
Licensed Texas Public Adjuster
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839.
Your property claim deserves representation from someone who understands Texas insurance claims and works for the insured.
We Work for Policyholders
The insurance company’s adjuster represents the insurer.
A public adjuster represents you.
That alignment is one of the most important differences in the claim process.
Texas-Focused Experience
Our experience includes thousands of claim reviews involving residential and commercial property losses across Texas.
That work includes:
- Hail
- Wind
- Hurricanes
- Water
- Fire and smoke
- Roof damage
- Large commercial losses
- Claim supplements
- Underpaid claims
- Disputed damage scopes
Residential and Commercial Expertise
Magnolia includes everything from subdivision homes near major corridors to acreage estates and commercial properties.
Homes in communities such as High Meadow Ranch, Lake Windcrest, Westwood, Mostyn Manor, and Indigo Lake Estates can differ substantially in roof systems, size, detached structures, and construction.
Those differences matter when preparing an accurate insurance claim.
Local Property Claims Across the Magnolia Community
Magnolia retains a distinctive small-town center even as the surrounding area grows.
The Magnolia Stroll provides a pedestrian connection through downtown, while Unity Park serves as a major recreation area. The Magnolia Depot Museum reflects the city’s history as a former railroad and shipping community.
Property types change quickly as you move outward from the town center.
Around established subdivisions, losses may involve conventional residential roofing, fences, garages, and interior water intrusion. In acreage communities such as High Meadow Ranch or Lake Windcrest, a single claim can involve a primary residence plus detached garages, workshops, barns, gates, or other structures.
That is one reason a Magnolia public adjuster should evaluate the entire insured property—not only the first obvious area of damage.
Areas We Serve Near Magnolia
TX Public Adjusting assists property owners throughout Magnolia and surrounding communities in western and southern Montgomery County. Our service area extends toward Conroe, The Woodlands, Spring, and Tomball, as well as communities throughout the greater northwest Houston region.
Magnolia itself is approximately 25 miles southwest of Conroe and has convenient access toward Houston and The Woodlands.
Frequently Asked Questions
What does a public adjuster in Magnolia do?
A public adjuster represents the property owner during an insurance claim. That can include reviewing the policy, inspecting damage, preparing estimates, documenting the loss, communicating with the insurance carrier, and negotiating disputed claim issues.
TX Public Adjusting represents policyholders rather than insurance companies.
When should I hire a public adjuster after a Magnolia storm?
You can contact a public adjuster early in the claim or after problems develop. Property owners commonly seek help when damage is extensive, the carrier’s scope appears incomplete, a claim has been denied, or the payment does not appear sufficient for documented repairs.
Getting a professional review before accepting a disputed scope can make it easier to identify missing items while evidence is still available. If your claim has already been open for some time, see our guide explaining when it is too late to hire a public adjuster.
Can a public adjuster help if my roof claim was underpaid?
Yes. Roof claims are a common reason Magnolia property owners request a second review.
A public adjuster can compare the carrier estimate against observed damage, measurements, repair requirements, and supporting documentation, then address legitimate differences with the insurer.
Does TX Public Adjusting handle hail claims in Magnolia?
Yes. We assist with hail damage claims involving residential and commercial properties.
Hail can affect shingles, metal components, vents, gutters, HVAC equipment, siding, and other exterior components. The goal is to document the complete covered loss rather than focus only on one visibly damaged area.
Can you help with water damage caused by a storm?
Yes, when the loss involves covered water damage.
The cause of the water matters. Wind-driven rain entering through a storm-created opening may be treated differently than rising surface water or flooding. We review the reported cause, resulting damage, and applicable policy language as part of the claim.
What if my insurance company already sent an adjuster?
You can still hire a public adjuster.
The insurance company’s adjuster evaluates the loss for the carrier. A licensed public adjuster independently represents the policyholder and can review the carrier’s estimate for missing damage, scope differences, or valuation issues. Our public adjuster vs. independent adjuster guide explains those roles in more detail.
Can a public adjuster reopen an insurance claim?
Some claims may still have options for supplemental documentation or further review after an initial payment or closure, depending on the policy, facts, deadlines, and status of the loss.
It is better to have the claim reviewed promptly rather than assume a closed file can always be reopened later.
Do you handle commercial claims in Magnolia?
Yes. TX Public Adjusting handles residential and commercial property claims.
Commercial losses may involve roofing, equipment, inventory, tenant improvements, multiple structures, extra expense, and business-income issues in addition to the physical building damage.
How much does a public adjuster charge in Texas?
Public adjuster compensation is governed by the written agreement and applicable Texas requirements. The fee structure should be explained clearly before representation begins.
TX Public Adjusting offers a Free Claim Review, allowing you to discuss the loss and understand whether professional claim assistance may make sense before moving forward.
Why hire TX Public Adjusting for a Magnolia property claim?
TX Public Adjusting combines Texas-focused claim experience with independent policyholder representation. We handle residential and commercial losses and have experience reviewing thousands of claims involving roofs, hail, wind, water, fire, and major storm damage.
We operate through Rise Public Adjusting LLC, Texas Public Adjuster License #3356839, so Magnolia property owners can verify who is representing them and whose interests that professional represents.
Get a Free Magnolia Insurance Claim Review
If your home or commercial property has been damaged, you do not have to rely solely on the insurance company’s estimate to determine whether the claim has been fully documented.
TX Public Adjusting can review your loss, inspect the property, identify potential scope issues, and explain the next steps.
Contact TX Public Adjusting today for a Free Claim Review.
- Licensed Texas Public Adjuster
- Residential & Commercial Claims
- Hail, Roof, Water, Fire & Storm Claims
- Independent Policyholder Representation
- Rise Public Adjusting LLC
- Texas License #3356839
- No upfront fees to get started
Get help with your Magnolia property damage claim today.