

Property damage in Kingwood can become complicated quickly. This heavily wooded community sits along the Lake Houston and San Jacinto River system, where hurricanes, tropical rainfall, wind-driven rain, falling trees, hail, plumbing failures, and interior water damage can create expensive residential and commercial insurance claims. When the carrier’s estimate does not reflect the full scope of the loss, a Public Adjuster in Kingwood, TX can independently review the damage and represent the policyholder throughout the claim.
TX Public Adjusting helps Kingwood homeowners, business owners, property managers, and commercial property owners document and negotiate property insurance claims. We work for the policyholder—not the insurance company.
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839. Our team has reviewed thousands of property claims involving roofs, water losses, fire damage, severe storms, commercial buildings, and disputed insurance estimates throughout Texas.
Free Claim Review • No Upfront Fees • Residential & Commercial Claims
If your Kingwood property has already been inspected and you received a low estimate, partial payment, denial, or confusing scope of loss, contact TX Public Adjusting for a free claim review.
Property Insurance Claims in Kingwood Are Different
Kingwood is part of far northeast Houston and lies primarily in Harris County, with portions extending into Montgomery County. The community is bordered by Lake Houston and sits near the East and West Forks of the San Jacinto River. That geography matters when evaluating storm losses and water-related property damage.
Kingwood is also unusually wooded for a major Houston-area community. Mature trees are part of what makes neighborhoods such as Bear Branch, Greentree, Sand Creek, Trailwood, Kings Point, Foster’s Mill, Hunters Ridge, and Mills Branch distinctive. Those same trees can become a serious property hazard during hurricanes and severe windstorms.
| Kingwood Property Claim Factor | Local Consideration |
| Counties | Primarily Harris County; portions extend into Montgomery County |
| Primary storm threats | Hurricanes, tropical storms, high winds, heavy rainfall, lightning and hail |
| Water-related risks | Roof leaks, wind-driven rain, plumbing losses and major flood events |
| Property characteristics | Wooded residential villages, waterfront properties and commercial corridors |
| Common claims | Roof, wind, water, fire, hail, tree impact and commercial property damage |
Why Property Owners Hire a Public Adjuster in Kingwood
An insurance company adjuster evaluates the claim on behalf of the insurer. A public adjuster approaches the same loss from the policyholder’s side. Property owners who want a clearer explanation of the roles can read our public adjuster vs. independent adjuster comparison.
That distinction can become especially important after a major storm when carrier adjusters may be handling a large volume of claims at the same time. A quick inspection can miss components that become expensive during reconstruction.
A Kingwood public adjuster may assist by:
- Reviewing your policy and existing claim documents
- Inspecting residential or commercial property damage
- Comparing the carrier estimate with observable damage
- Preparing photographs, measurements, inventories, and supporting documentation
- Identifying scope omissions or pricing discrepancies
- Communicating with the insurance carrier regarding the claim
- Preparing supplements when additional covered damage is identified
- Negotiating the documented value and scope of the loss
Property owners frequently contact us after receiving an estimate that seems too low to complete repairs, but a public adjuster can also become involved earlier when the loss is substantial or difficult to document.
Kingwood Storm Risks and Property Damage
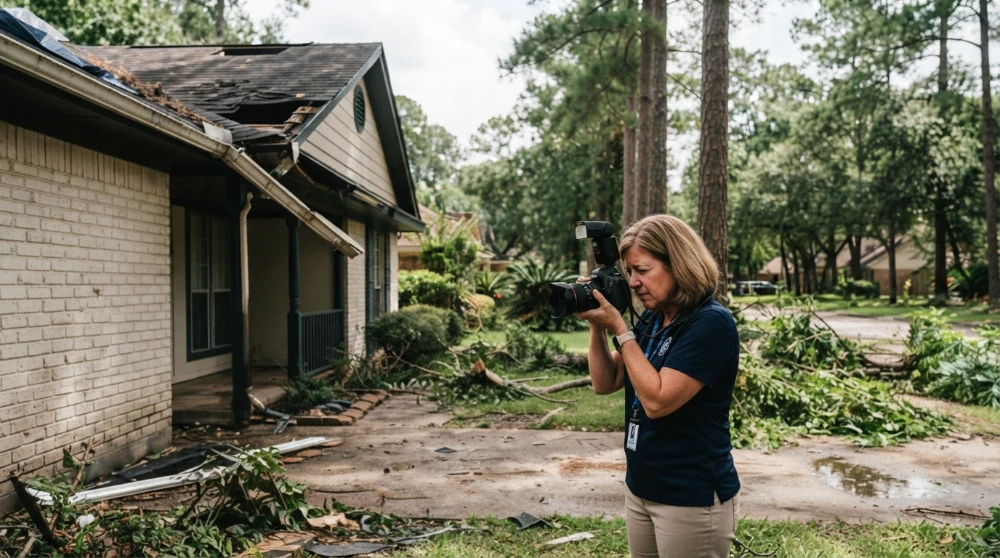
Kingwood’s storm history deserves its own discussion because water and wind risks here are different from those in many inland Texas communities.
Hurricane and Tropical Storm Damage
Because Kingwood is part of the Greater Houston region, tropical systems can bring damaging winds, prolonged rainfall, falling trees, roof failures, damaged fencing, broken exterior components, and water entering through storm-created openings.
Hurricane Beryl demonstrated the wind and tree exposure clearly in July 2024. Sand Creek Village was among Kingwood neighborhoods reporting downed trees and prolonged power outages after the storm.
A hurricane claim can involve far more than shingles. We look at the relationships between roof coverings, flashing, vents, gutters, siding, windows, fencing, interior ceilings, insulation, flooring, electrical systems, and other affected components.
For a deeper explanation of roof, interior, structural, water, debris, and other storm losses, see our Texas hurricane damage guide.
Heavy Rain and Flooding
Kingwood has experienced significant flooding during major Gulf Coast rain events. The City of Houston’s San Jacinto watershed planning materials record approximately 42 inches of rainfall during Hurricane Harvey in the Kingwood study area and 26.6 inches during Tropical Storm Imelda, along with thousands of Harvey-related flood claims in the study area.
Harvey caused substantial damage to Kingwood homes, schools, shopping areas, and businesses. Reporting after the storm documented flooding in locations including Bear Branch and the Kingwood commercial area near Lake Houston.
Flood coverage requires particular care. Rising surface water is commonly handled differently from rain entering through a storm-damaged roof or other covered opening, and coverage depends on the actual policy. A property can also suffer more than one cause of damage during the same storm. Proper documentation of how water entered the building is therefore critical.
Wind and Falling Tree Damage
The wooded character of Kingwood creates another recurring claim issue: tree impact.
High winds can send limbs into shingles, gutters, fences, windows, detached structures, HVAC equipment, and exterior finishes. A tree may also puncture a roof and allow rain into attic insulation, drywall, flooring, and contents.
The visible tree damage may be only the beginning. The structure underneath the impact area should also be evaluated.
Hail and Severe Thunderstorms
Kingwood is not exposed to hail as frequently as some parts of North Texas, but Southeast Texas thunderstorms can still produce damaging hail.
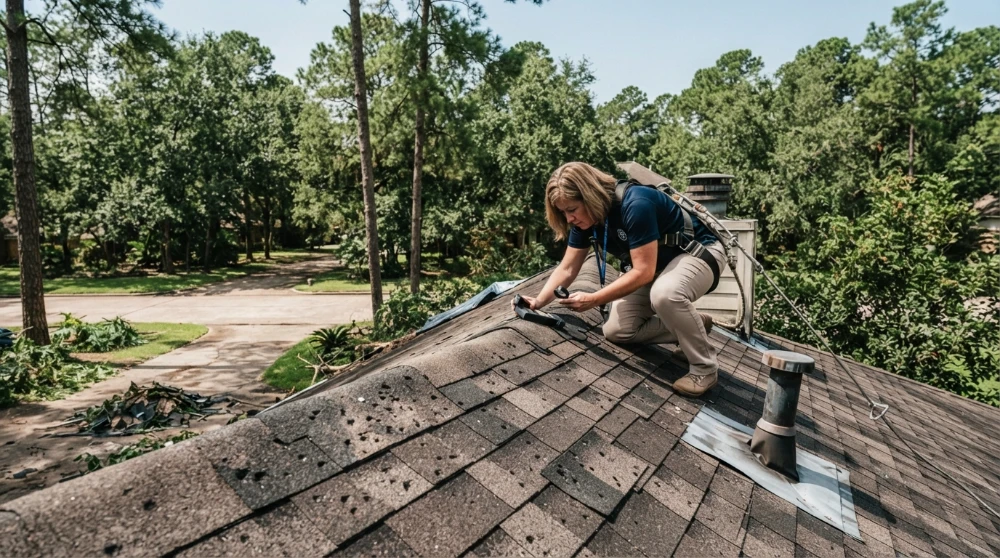
Hail claims may involve asphalt shingles, roof vents, flashing, gutters, window screens, siding, HVAC fins, soft metals, and commercial roofing membranes. Damage should be documented before repairs or material removal make the original condition harder to prove.
Common Insurance Claims in Kingwood
Hail Damage Claims
Hail damage is often difficult to evaluate from the ground. A roof may not leak immediately even though shingles, flashing, vents, or other components have sustained impact damage.
For a Kingwood hail damage roof insurance claim, TX Public Adjusting can review the roof and related exterior components, compare the observed conditions with the insurance estimate, and document legitimate differences in scope.
Property owners can also review our guide on how to document hail damage for an insurance claim before repairs or material removal begin.
Water Damage Claims
Water losses in Kingwood are not limited to hurricanes. A water damage public adjuster can help evaluate the scope of a covered loss when the carrier’s estimate does not account for all affected materials or areas.
Burst pipes, supply-line failures, leaking appliances, roof leaks, plumbing backups, HVAC condensation, and sudden interior water releases can damage drywall, cabinetry, insulation, flooring, electrical components, and personal property.
Determining the source of the water and documenting both visible and hidden damage can materially affect an insurance claim.
Fire Damage Claims
A Kingwood fire insurance adjuster working for the policyholder can help document more than the visibly burned areas. A fire claim may include direct burn damage as well as smoke residue, odor, soot, damaged contents, demolition, debris removal, electrical repairs, code-related work, and additional living expenses when applicable under the policy.
We help Kingwood property owners organize these different parts of a fire loss into a documented claim rather than treating the event as a single repair estimate.
Storm Damage Claims
Hurricanes and severe thunderstorms can produce several types of damage during one event.
A storm claim may include:
- Wind-damaged shingles
- Fallen trees and limbs
- Damaged siding
- Broken windows
- Roof penetrations
- Water intrusion
- Damaged fences
- Exterior equipment damage
- Interior ceiling and wall damage
Each component should be documented separately and tied to the reported loss.
Roof Damage Claims
Kingwood’s tree canopy and Gulf Coast storm exposure make roof claims especially important. Property owners dealing with a disputed or underpaid loss can learn more about working with a public adjuster for a roof claim and the types of scope issues that may warrant another review.
Carrier estimates sometimes address a few damaged shingles while excluding flashing, vents, decking, underlayment, steep-access charges, interior water damage, or other related items. The appropriate repair scope depends on the actual damage, construction, policy language, and site conditions.
Commercial Property Claims
Kingwood’s commercial properties range from offices and retail centers to restaurants, medical buildings, multifamily properties, and waterfront businesses.
Areas around Kingwood Drive, West Lake Houston Parkway, Town Center, and the Lake Houston corridor can experience the same wind and water losses as residential properties—but commercial claims often involve larger roofs, mechanical systems, tenant improvements, business personal property, and more complicated repair scopes.
Already received an insurance estimate? TX Public Adjusting can review the claim before you assume the carrier’s first scope is the final word. Request a Free Claim Review with no upfront fee.
Why Insurance Claims Become Underpaid
An underpaid property claim does not always result from one major mistake. More often, several smaller omissions add up.
Missed Damage
A brief inspection may focus on the most visible area of loss while overlooking secondary damage.
For example, a storm-created roof opening can affect shingles, decking, insulation, drywall, paint, flooring, and contents. Documenting only the roof can leave much of the loss outside the estimate.
Scope Omissions
Carrier estimates can omit legitimate repair operations or related components.
Common disputes involve flashing, gutters, detach-and-reset work, interior finishes, matching issues, access requirements, debris removal, and commercial roofing details.
Depreciation Issues
Property owners may receive an actual cash value payment first and misunderstand what is depreciated, what may later be recoverable, and what documentation is required.
We review how depreciation has been applied and explain the claim documentation in practical terms.
Low Repair Estimates
An estimate can appear detailed while still failing to reflect the work required to restore the property.
Quantity differences, labor assumptions, missing materials, and overlooked repair operations can create substantial gaps between an insurance estimate and the actual reconstruction scope.
Documentation Problems
Photographs taken after demolition, incomplete inventories, missing receipts, unclear timelines, and poorly documented mitigation can weaken an otherwise legitimate claim.
Strong documentation is easier to build before evidence disappears.
Our Public Adjusting Process
1. Claim Review
We begin by reviewing the reported loss, policy information, carrier correspondence, estimates, payments, and claim status.
If the claim has already been denied or underpaid, we examine the carrier’s position and identify the issues that require closer review.
2. Property Inspection
We inspect the affected areas and look beyond the obvious damage.
For a Kingwood storm loss, that may mean evaluating roofing, exterior surfaces, tree impact areas, attic conditions, interior moisture damage, and related building components.
3. Documentation
We organize the evidence needed to present the loss clearly.
Depending on the claim, documentation may include photographs, measurements, estimates, contents information, repair records, invoices, mitigation documents, and supporting professional reports.
4. Claim Presentation and Negotiation
TX Public Adjusting communicates with the carrier regarding documented differences in damage, scope, quantities, and other claim issues.
Our role is to represent your side of the insurance claim professionally and with evidence.
5. Settlement and Claim Resolution
We continue working through the documented claim issues until the adjustment process reaches resolution.
No public adjuster can guarantee a particular settlement. Our job is to build and advocate for an accurate, well-supported claim under the applicable policy.
Why Choose TX Public Adjusting for a Kingwood Claim?
Property owners do not need another person repeating what the insurance company already said. They need independent representation.
TX Public Adjusting offers:
- Licensed Texas Public Adjuster — Rise Public Adjusting LLC, License #3356839
- Policyholder representation — we work for property owners, not insurance companies
- Texas-focused experience — including storm, hail, roof, water, fire, and commercial claims
- Residential and commercial claim experience
- Thousands of claims reviewed
- Detailed damage and scope analysis
- Claim documentation and negotiation support
- Free initial claim review
- No upfront fees
Our experience includes losses involving single-family homes, commercial buildings, apartment properties, retail spaces, restaurants, offices, and other insured Texas properties.
Kingwood Neighborhoods We Serve
Kingwood is made up of distinct villages rather than one uniform residential area. Local community resources identify neighborhoods including Bear Branch, Elm Grove, Forest Cove, Foster’s Mill, Greentree, Hunters Ridge, Kings Crossing, Kings Point, Kings River, Mills Branch, Riverchase, Sand Creek, Trailwood, Woodstream, and others.
TX Public Adjusting assists property owners throughout these Kingwood communities, including properties near:
- Bear Branch Village
- Greentree Village
- Sand Creek Village
- Trailwood Village
- Kings Point
- Kings River
- Foster’s Mill
- Hunters Ridge
- Riverchase
- Mills Branch
- Forest Cove
- Kingwood Greens
- Town Center
- Kingwood Drive
- West Lake Houston Parkway
Local landmarks such as Town Center Park, River Grove Park, East End Park, Lake Houston, and the King’s Harbor area reflect how closely Kingwood is connected to wooded greenbelts and water. Town Center Park serves as a community gathering space, while River Grove Park includes direct access to Lake Houston.
Areas We Serve Near Kingwood
TX Public Adjusting also serves surrounding communities across the Lake Houston and northeast Houston region, including Humble public adjuster services, Atascocita public adjuster services, Spring public adjuster services, The Woodlands public adjuster services, and Conroe public adjuster services.
If you own more than one property—or manage residential or commercial buildings across Harris and Montgomery counties—we can review claims throughout the region.
Frequently Asked Questions About Public Adjusters in Kingwood
What does a public adjuster in Kingwood do?
A public adjuster represents the policyholder during a property insurance claim. We inspect damage, review the insurance company’s estimate, document the loss, prepare supporting information, communicate with the carrier, and negotiate documented claim differences.
TX Public Adjusting represents homeowners and commercial property owners, not insurance companies.
When should I hire a public adjuster after property damage in Kingwood?
Consider requesting a claim review when the loss is significant, the property has multiple damaged areas, the insurer’s estimate appears too low, important items were omitted, the claim was denied, or communication with the carrier has stalled.
You can also involve a public adjuster earlier when you want professional documentation before evidence is removed during repairs.
Timing can depend on the status of the claim, so property owners with an older or already-paid claim can also read when it is too late to hire a public adjuster.
Can a public adjuster help after a hurricane in Kingwood?
Yes. Hurricane losses can involve roofing, siding, windows, tree impacts, wind-driven rain, interiors, contents, and commercial building systems.
The cause of each component matters, particularly where floodwater and wind-related damage occur during the same event. Coverage is determined by the applicable policy, so documentation should distinguish the different causes of loss rather than simply labeling everything “hurricane damage.”
Can you help with a low roof claim estimate?
Yes. Roof claims are one of the most common reasons property owners request a second review.
We can compare the carrier’s scope with the property conditions and evaluate whether roofing materials, flashing, vents, gutters, related exterior components, interior water damage, or necessary repair operations were missed.
Do you handle water damage claims in Kingwood?
Yes. We assist with covered water losses involving plumbing failures, burst pipes, appliances, roof leaks, storm-created openings, and resulting interior damage.
Flooding from rising surface water is treated differently from many other water losses and may require separate flood coverage. The specific policy and source of water must be reviewed.
Can I hire a public adjuster after my insurance company has already inspected the property?
Yes. A carrier inspection does not automatically prevent you from hiring a public adjuster.
Many Kingwood property owners contact us specifically because the first inspection has already occurred and the resulting payment or repair scope does not match the damage they are seeing.
What if my Kingwood insurance claim has already been denied?
A denial does not always mean there is nothing left to review.
We can examine the denial letter, policy information, photographs, estimates, and available evidence to determine whether additional documentation or another claim step may be appropriate. Your options depend on the facts, policy, claim stage, and applicable deadlines.
If the denial involves storm-related roof damage, our guide explains what to do if your hail claim was denied and the documentation that may deserve another review.
How much does a public adjuster cost in Texas?
Public adjuster fees are addressed in the written agreement and are subject to Texas requirements. Before hiring a public adjuster, you should understand the fee structure and contract terms.
TX Public Adjusting offers a free initial claim review with no upfront fee, allowing you to discuss the claim before deciding how to proceed.
Do you handle commercial claims in Kingwood?
Yes. We assist commercial property owners with storm, roof, water, fire, hail, and other covered property losses.
Commercial claims may require evaluation of larger roofing systems, mechanical equipment, tenant improvements, business personal property, multiple building areas, and more extensive repair documentation than a typical residential loss.
Why choose TX Public Adjusting instead of relying only on the insurance company’s adjuster?
The insurance company’s adjuster is working on the insurer’s claim file. A public adjuster is retained by the policyholder.
TX Public Adjusting provides an independent review from your side of the claim. Rise Public Adjusting LLC is a licensed Texas public adjusting firm, License #3356839, with experience reviewing thousands of residential and commercial property claims.
Get a Free Kingwood Insurance Claim Review
If your Kingwood home or commercial property has suffered hurricane damage, wind damage, hail, roof damage, water damage, fire damage, tree impact, or another covered loss, you do not have to assume the first insurance estimate is complete.
TX Public Adjusting can review your property damage, existing insurance estimate, payment, denial, or claim documentation and explain what deserves a closer look.
Free Claim Review. No Upfront Fees. Residential & Commercial Claims.
Contact TX Public Adjusting — Rise Public Adjusting LLC, Texas License #3356839 — today to discuss your Kingwood property insurance claim.