

Property damage in Stowell can turn into a complicated insurance claim quickly. This part of Chambers County sits close enough to the upper Texas Gulf Coast to face tropical systems, heavy rain, strong thunderstorms, high winds, and water-related damage, while homes, agricultural properties, commercial buildings, and roofs can also be affected by hail, fire, plumbing failures, and other unexpected losses.
If your insurer has issued a low estimate, left damage out of the scope, delayed the claim, or simply made the process harder than expected, a public adjuster in Stowell, TX can represent your interests throughout the property insurance claim.
TX Public Adjusting, operated by Rise Public Adjusting LLC, represents Texas policyholders rather than insurance companies. We assist residential and commercial property owners with inspection, damage documentation, estimate review, claim presentation, and negotiation. We are a licensed Texas public adjusting firm operating under Texas License #3356839.
Need help with a Stowell property damage claim? Request a Free Claim Review from TX Public Adjusting. There are no upfront fees.
Why Property Owners Hire a Public Adjuster in Stowell
Stowell is a small Chambers County community, but the property risks here are anything but insignificant.
Located around State Highway 124 and Farm Road 65, Stowell is closely connected with neighboring Winnie and sits in the coastal plain between the Houston and Beaumont-Port Arthur regions. Homes and businesses throughout the Winnie-Stowell area are exposed to weather systems moving inland from the Gulf as well as strong seasonal thunderstorms.
After property damage, an insurance company typically sends its own adjuster or assigns an independent adjusting firm to investigate the loss. That adjuster is handling the claim on behalf of the insurance carrier.
A public adjuster has a different role.
We represent the policyholder.
Property owners in Stowell may hire TX Public Adjusting when:
- The carrier’s estimate appears too low.
- Important roof or exterior damage was omitted.
- Interior water damage was not fully documented.
- A storm caused damage in several areas of the property.
- The insurer disputes whether repairs or replacement are necessary.
- Depreciation or pricing significantly reduces the initial payment.
- A commercial loss involves multiple buildings, systems, or business components.
- The claim has become difficult to manage without professional documentation.
- A denied or underpaid claim deserves another detailed review.
Our job is to determine what damage exists, document the loss, evaluate the insurer’s scope, and present the policyholder’s position clearly and thoroughly.
For many Stowell property owners, the issue is not simply filing a claim. It is making sure the claim accurately reflects what happened to the property.
Stowell Property Damage Risks Are Closely Tied to the Gulf Coast
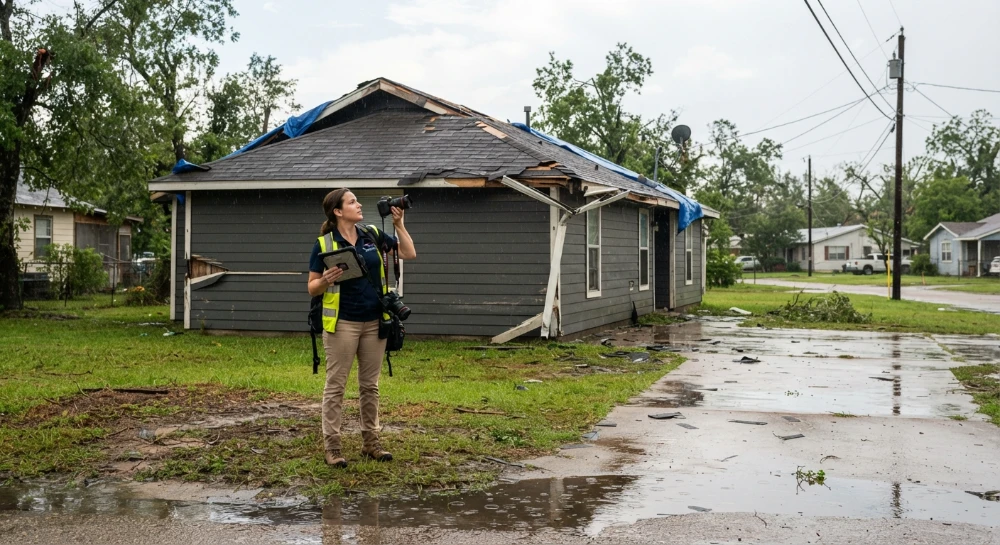
Stowell’s location gives the community a different insurance-loss profile than many inland Texas cities.
The surrounding Chambers County landscape is low and relatively flat, with bayous, canals, marshes, agricultural acreage, and coastal areas extending toward Trinity Bay and the Gulf. The community’s history is also closely connected with rice farming, drainage, canals, oil and gas activity, and the neighboring town of Winnie.
That geography matters when property claims occur.
Hurricanes and Tropical Storms
Tropical systems approaching the upper Texas coast can produce damaging winds and prolonged rainfall well beyond the immediate shoreline.
A hurricane claim in Stowell may involve:
- Lifted or missing roofing materials
- Wind-created openings
- Damaged flashing and roof accessories
- Siding damage
- Broken windows or exterior components
- Wind-driven rain
- Ceiling and wall staining
- Wet insulation
- Interior flooring damage
- Detached structures
- Fences and exterior improvements
- Commercial roofing systems
The challenge is often determining exactly how water entered the building and distinguishing covered wind-related damage from other causes.
That distinction can materially affect how an insurance claim is evaluated.
Heavy Rain and Localized Water Damage
Heavy Gulf Coast thunderstorms can dump large amounts of rain over Chambers County in a short period.
The National Weather Service regularly includes Stowell and Winnie in warnings involving strong thunderstorms, gusty winds, torrential rainfall, and localized flooding.
For property insurance claims, water damage may appear far from the original point of entry. A roof opening can allow moisture into insulation, attic materials, drywall, electrical components, cabinetry, flooring, and adjoining rooms.
A proper claim inspection should follow the damage rather than stopping at the first visible stain.
Strong Thunderstorm and Wind Damage
Stowell can experience powerful thunderstorms capable of producing damaging wind gusts.
Wind losses often create subtle problems. Shingles may remain on the roof but become creased or loosened. Metal roofing components may shift. Flashing can pull away. Commercial roofing membranes may experience uplift or attachment damage.
The carrier’s initial inspection may not always identify the complete repair scope.
Hail Damage
Although coastal wind and rain receive much of the attention in Chambers County, severe thunderstorms can also bring hail.
Hail can affect:
- Asphalt shingles
- Metal roofing
- Gutters
- Downspouts
- Roof vents
- HVAC equipment
- Window screens
- Fencing
- Siding
- Commercial roof membranes
- Soft-metal roof components
Damage may be especially difficult for property owners to recognize from ground level.
If you suspect storm damage, our Texas hail damage insurance claim guide explains what to look for and how roof damage should be documented.
Fire and Smoke Damage
Fire claims require a completely different type of investigation.
A structure fire can affect areas that were never directly touched by flames. Smoke, soot, heat, firefighting water, damaged electrical systems, contents, insulation, and odor contamination can significantly increase the scope of the loss.
TX Public Adjusting reviews residential and commercial fire claims throughout Texas, including claims involving structural repairs, contents, cleaning, demolition, and related property damage.
Common Insurance Claims in Stowell
Hail Damage Claims
Hail claims often begin with a roof inspection but should not necessarily end there.
Our adjusters inspect roofing materials and other exterior surfaces, document visible storm impacts, compare those findings with the insurance company’s estimate, and identify items that may require further consideration.
Property owners dealing with hail damage can also review our guide to hail damage insurance claims.
Water Damage Claims
A failed plumbing line, leaking appliance, roof opening, or other sudden water event can damage far more than the immediately visible area.
Water can migrate behind walls, underneath floors, into insulation, and through adjoining building materials.
Our team evaluates the visible loss as well as the surrounding areas that may need to be included in a complete repair scope.
Learn more about working through a water damage insurance claim.
Fire Damage Claims
Fire claims may involve structure, contents, smoke, soot, demolition, water from fire suppression, and temporary living or operating issues.
TX Public Adjusting helps organize these different portions of the loss so the property owner can present a detailed claim rather than relying solely on the carrier’s initial estimate.
Read more about working with a fire insurance adjuster.
Storm Damage Claims
For Stowell, storm claims can include several causes of damage occurring at the same time.
A single thunderstorm or tropical system may produce:
- Roof damage
- Wind damage
- Water intrusion
- Broken exterior components
- Fence damage
- Ceiling stains
- Interior finishes damaged by rain
- HVAC or equipment damage
That makes documentation especially important.
The goal is not simply to prove that a storm occurred. The claim should show how the storm affected the specific property.
Roof Damage Claims
Roof claims are among the property losses where scope disagreements frequently arise.
The insurer may identify a repair while the contractor believes more extensive work is required. Accessories may be omitted. Interior damage may not be connected to the roof loss. Measurements or material quantities may differ.
TX Public Adjusting reviews the roof, supporting documentation, and carrier estimate to identify discrepancies.
See our guide to hiring a public adjuster for a roof claim.
Commercial Property Claims
Commercial property losses often involve more moving parts than residential claims.
In and around Stowell and Winnie, commercial claims may involve retail buildings, agricultural facilities, warehouses, offices, restaurants, service businesses, storage facilities, metal buildings, multifamily properties, and other structures.
Commercial losses can involve roofing systems, equipment, interior build-outs, inventory, tenant improvements, and multiple damaged areas.
TX Public Adjusting handles both residential and commercial claims and can review complex losses through our commercial claims practice.
Why Stowell Insurance Claims Become Underpaid
An underpaid claim does not always result from one obvious mistake.
More often, several smaller omissions reduce the total scope.
Missed Damage
A quick inspection may identify the most obvious problem but miss secondary damage.
For example, a roof claim might include shingles while overlooking flashing, gutters, vents, interior water staining, insulation, or related exterior components.
Scope Omissions
Insurance estimates are built line by line.
If necessary work is absent from the estimate, the final claim value can be affected significantly.
Common disagreements can involve:
- Removal and replacement quantities
- Roofing accessories
- Detach-and-reset work
- Interior finishes
- Drywall
- Paint
- Flooring
- Insulation
- Debris removal
- Equipment access
- Commercial roofing components
Depreciation Issues
Many property insurance estimates apply depreciation.
Depending on the policy and claim circumstances, some depreciation may potentially be recoverable after repairs are completed. Property owners should understand how depreciation is being applied rather than looking only at the first payment amount.
Low Repair Estimates
Pricing differences can become significant after a large storm when labor and material demand increase.
A carrier estimate should be reviewed against the actual repair scope and the specific characteristics of the damaged property.
Documentation Problems
Even legitimate damage can become difficult to recover when the claim file does not clearly show what was damaged and why the proposed repairs are necessary.
Photographs, measurements, estimates, reports, inventories, correspondence, and other supporting documentation help create a more complete claim presentation.
Our Public Adjusting Process
Every property claim is different, but our work generally follows five core stages.
1. Claim Review
We begin by reviewing the current status of the insurance claim.
That may include:
- Insurance estimates
- Carrier correspondence
- Payment documents
- Denial letters
- Contractor estimates
- Photographs
- Prior inspection reports
- Relevant policy information
We identify the major areas that deserve additional review.
2. Property Inspection
Next, we inspect the property and evaluate the reported damage.
For a Stowell storm claim, that might involve the roof, exterior elevations, interior rooms, detached structures, and commercial building components.
3. Damage Documentation
We create documentation designed to show the loss clearly.
Depending on the claim, that can include photographs, measurements, repair scope information, inventories, estimates, and supporting records.
4. Claim Presentation and Negotiation
We communicate with the insurance company on behalf of the policyholder and present the documented scope of damage.
When disagreements arise, we explain the basis for the items we believe should be reconsidered.
5. Settlement and Claim Resolution
The goal is to help the policyholder pursue a fair settlement under the terms of the insurance policy.
No public adjuster can guarantee a particular result, and every policy and loss is different. What we can do is make sure the claim is investigated, documented, and presented from the policyholder’s side of the table.
Already received an insurance estimate in Stowell? Before accepting a settlement you believe is too low, contact TX Public Adjusting for a Free Claim Review.
Why Choose TX Public Adjusting for a Stowell Claim?
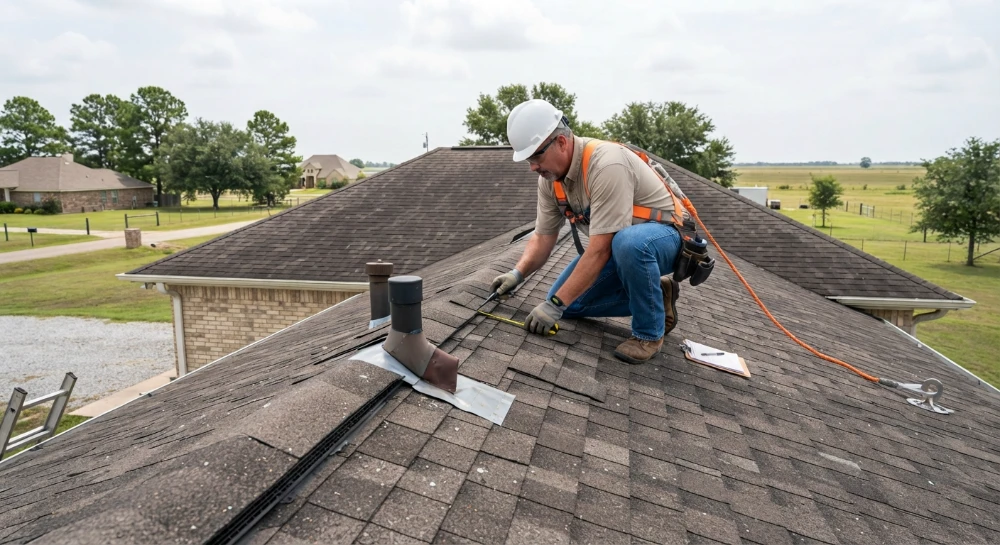
Licensed Texas Public Adjuster
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839.
We Represent Policyholders
Insurance company adjusters represent the carrier’s interests.
Public adjusters represent property owners.
Our responsibility is to the policyholder who hires us.
Texas-Focused Claim Experience
Texas claims involve everything from severe hail and wind to hurricanes, fires, burst pipes, freezes, and commercial property losses.
Our team has reviewed thousands of property insurance claims, giving us experience with both straightforward losses and complicated disputes.
Residential and Commercial Expertise
We work with homeowners as well as commercial property owners.
That means we understand the differences between documenting a residential roof loss and evaluating a multi-component commercial claim.
Detailed Claim Documentation
A strong claim is built on evidence.
Our work focuses on documenting the damage, identifying omissions, evaluating repair scope, reviewing carrier estimates, and presenting the policyholder’s position in an organized manner.
Free Claim Review
If you are unsure whether hiring a public adjuster makes sense, start with a claim review.
There are no upfront fees, and we can discuss the condition of your claim before you decide how to proceed.
Local Property Claim Help in the Winnie-Stowell Area
Stowell does not have the large named neighborhood system found in Houston or Dallas. Local property references are more naturally organized around the Winnie-Stowell community, the SH 124 corridor, the FM 65 area, rural and agricultural properties outside the community center, and nearby eastern Chambers County communities.
Stowell’s identity is particularly connected to Winnie. The two communities share long agricultural roots and are associated with the annual Texas Rice Festival, an event celebrating a crop that has played an important role in the area’s history.
Other recognizable places throughout the surrounding part of Chambers County include Winnie-Stowell Park, Anahuac National Wildlife Refuge, Fort Anahuac Park, and the natural areas extending toward Trinity Bay and the coastal marshes.
The local building environment also varies considerably. A property claim might involve an older single-family home, a rural structure, a metal building, a commercial property along a highway corridor, or agricultural improvements outside the denser portions of town.
That is why a Stowell claim should be evaluated based on the actual property rather than a generic storm-loss template.
Areas We Serve Near Stowell
TX Public Adjusting assists policyholders throughout Chambers County and surrounding Southeast Texas communities.
Nearby service areas include:
- Winnie
- Anahuac
- Hankamer
- Wallisville
- Mont Belvieu
- Beach City
- Cove
- Old River-Winfree
- Hamshire
- Smith Point
- Oak Island
We also assist property owners throughout the greater Houston-Galveston and Beaumont-Port Arthur regions when covered property damage results in a difficult insurance claim.
Frequently Asked Questions About Public Adjusters in Stowell
What does a public adjuster in Stowell do?
A public adjuster represents the policyholder during a property insurance claim. We inspect damage, review insurance estimates, document the scope of loss, prepare supporting information, communicate with the insurer, and negotiate disputed claim items when appropriate.
The important distinction is representation: TX Public Adjusting works for the property owner who hires us, not the insurance carrier.
When should I hire a public adjuster after storm damage in Stowell?
You can hire a public adjuster shortly after the loss or later if problems develop. Some Stowell property owners contact us immediately after significant hurricane, wind, hail, or water damage. Others call after receiving an estimate they believe does not cover the full repair scope.
If your claim is already underway, read our guide explaining when it may be too late to hire a public adjuster.
Can you help if my Stowell insurance claim was already paid?
Potentially. Receiving an initial payment does not automatically mean every issue in a claim has been resolved.
We can review the carrier’s estimate and compare it with documented property damage. The available options depend on your policy, deadlines, prior payments, and the condition of the claim.
Can a public adjuster help with hurricane damage in Stowell?
Yes. Hurricane and tropical storm losses are particularly relevant in Chambers County because the region can experience wind, heavy rain, wind-driven water, roof damage, and interior damage from Gulf Coast systems.
These claims often require careful documentation because multiple causes of damage may occur during the same event.
What if the insurance company says my roof only needs repairs?
A repair-versus-replacement disagreement should be evaluated based on the actual roof conditions, the damaged materials, repair feasibility, policy provisions, and other relevant claim facts.
TX Public Adjusting can inspect the property and compare our findings with the carrier’s scope. Our public adjuster for roof claim guide explains the issue in more detail.
Do you handle commercial insurance claims around Stowell and Winnie?
Yes. We handle commercial property claims throughout Texas.
In the Winnie-Stowell area, that may include retail locations, offices, warehouses, storage facilities, restaurants, agricultural buildings, service businesses, multifamily properties, and other commercial structures.
Can you help with water damage after a severe storm?
Yes, when the damage involves a potentially covered property insurance claim.
The important issue is documenting where the water entered, what materials were affected, and how far the damage extends. Water often moves beyond the first visible stain or damaged surface.
What if my insurance adjuster missed part of the damage?
Missed damage is one of the most common reasons property owners request an independent claim review.
We can compare the carrier’s estimate with the actual property conditions and identify areas that may require additional documentation or consideration.
How is a public adjuster different from the insurance company’s adjuster?
The insurance company’s adjuster works on behalf of the carrier. A public adjuster is hired by the policyholder.
Both may inspect the same property, but they represent different parties in the claim. For additional background, see our guide to public adjusters versus independent adjusters.
How do I get started with TX Public Adjusting in Stowell?
Start with a Free Claim Review.
Tell us what happened, where the property is located, what the insurance company has done so far, and what concerns you have about the claim. If available, have your carrier estimate, photographs, correspondence, and contractor documentation ready for review.
There are no upfront fees to begin the review.
Get Insurance Claim Help in Stowell, TX
Property owners in Stowell deal with a unique combination of Gulf Coast storm exposure, heavy rainfall, high winds, hail, roof damage, water intrusion, fires, and commercial property risks.
When an insurance claim does not reflect the full extent of the damage, you should not have to rely solely on the carrier’s assessment.
TX Public Adjusting represents you.
Rise Public Adjusting LLC is a licensed Texas public adjusting company serving homeowners and commercial property owners throughout Stowell, Chambers County, and communities across Texas.
If your claim has been underpaid, delayed, denied, or incompletely documented, contact TX Public Adjusting before accepting less than you believe is required to repair the covered damage.
Request your Free Claim Review today. No upfront fees.