Property damage in Dobbin can become complicated quickly. Homes, ranch properties, workshops, churches, and small commercial buildings around western Montgomery County are exposed to severe thunderstorms, hail, high winds, heavy rain, roof leaks, fire, and water losses. When the insurance company’s estimate does not reflect the full damage, a Public Adjuster in Dobbin can give the policyholder independent representation during the claim.
TX Public Adjusting helps residential and commercial property owners document damage, review insurance estimates, identify missing items, and negotiate covered property claims. We represent the policyholder—not the insurance company.
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839. If your Dobbin property claim has been delayed, denied, underpaid, or simply feels incomplete, request a Free Claim Review. There are no upfront fees to have us review your situation and explain your options.
Free Claim Review | Licensed Texas Public Adjuster | Residential & Commercial Claims
Property Claims Are Different in Dobbin, Texas
Dobbin is an unincorporated community in western Montgomery County centered near State Highway 105 and FM 1486. The community has deep agricultural and railroad roots and sits between Montgomery and Plantersville, with Magnolia to the south. The Handbook of Texas places Dobbin along Lake Creek and documents its history as a cotton, lumber, sawmill, and railroad community.
That rural setting creates a property mix that is different from what an adjuster might encounter in a dense Houston suburb. A loss here can involve a main residence along with detached garages, barns, workshops, fencing, equipment structures, outbuildings, metal roofs, older construction, acreage, or small businesses. For larger agricultural properties, TX Public Adjusting also handles public adjusting for farms and ranches throughout Texas.
Local reference points include the Dobbin Community Center on FM 1486, the historic Griffith Homesite and Cemetery, and the Highway 105/FM 1486 corridor that connects Dobbin with nearby Montgomery and Plantersville. Montgomery County lists the Dobbin Community Center approximately two miles south of Highway 105.
Those details matter after a property loss. A claim is rarely just “roof damage” or “water damage.” The complete scope may include multiple structures, exterior components, interior finishes, personal property, cleanup, temporary repairs, and other covered costs.
Why Property Owners Hire a Public Adjuster in Dobbin
Insurance companies send adjusters to investigate claims on behalf of the carrier. A public adjuster has a different role: we work for the policyholder.
That distinction becomes especially valuable when the claim involves widespread storm damage, multiple buildings, expensive roofing systems, disputed water intrusion, extensive interior damage, or an insurer estimate that does not appear sufficient to complete proper repairs.
A Dobbin public adjuster can help by:
- Reviewing the insurance policy and existing claim documentation.
- Conducting a detailed inspection of the damaged property.
- Comparing visible conditions with the insurance company’s estimate.
- Photographing and documenting damaged building components.
- Identifying potentially omitted areas of damage.
- Preparing or reviewing repair scopes and estimates.
- Organizing supporting documents, invoices, measurements, and records.
- Communicating with the insurance carrier concerning the property claim.
- Negotiating covered damage based on documentation and policy terms.
- Assisting with supplemental claims when the original scope is incomplete.
Property owners often call us after receiving an estimate that looks too low. Others contact us before the insurer has completed its inspection because the loss is large enough that they want experienced representation from the beginning.
Both situations can justify a review.
When a Second Look at Your Dobbin Claim Makes Sense
Consider having the claim reviewed when the insurer’s estimate omits obvious damage, proposes limited repairs where broader replacement may be required, applies depreciation you do not understand, disputes the cause of water intrusion, excludes detached structures from the scope, or closes a claim before all damage has been documented.
Our team has experience reviewing thousands of property claims, including residential and commercial losses throughout Texas. That experience helps us recognize scope problems that may not be apparent to a property owner reading an insurance estimate for the first time.
Storm and Weather Risks Affecting Dobbin Property
Western Montgomery County sits far enough inland that Dobbin does not experience the same storm-surge exposure as coastal communities, but that does not make the area immune from major weather losses.
The primary property risks include severe thunderstorms, damaging wind, hail, heavy rainfall, flash flooding, tornado activity, and the inland effects of tropical systems.
Recent National Weather Service warnings for Montgomery County have included thunderstorms capable of producing damaging winds and hail, and the agency has specifically warned that these conditions can damage roofs, siding, trees, and vehicles. Montgomery County also experiences flooding from intense rainfall and overflowing low-lying drainage areas and creeks.
Hail and Severe Thunderstorms
Hail does not have to punch through a roof to create an insurance issue. Asphalt shingles may lose granules or suffer fractured mats. Metal roofing, gutters, vents, flashing, siding, screens, fences, and exterior mechanical equipment can also be affected.
One challenge with a hail damage insurance claim in Dobbin is that damage may be spread across multiple elevations and structures. A house may show damage on the roof while a detached workshop, barn, or other insured structure shows different impacts.
A complete inspection should account for the entire property.
High Wind and Tornado Damage
Strong thunderstorms can lift shingles, loosen flashing, damage ridge caps, break tree limbs, deform metal roofing, damage siding, and create openings where rain later enters the structure.
Tornadoes are also a recognized hazard in Montgomery County. National Weather Service warnings have documented tornado-producing storms in the county capable of damaging roofs, windows, vehicles, and trees.
After a wind event, the visible damage on the ground may only tell part of the story. Roof coverings, vents, decking, fascia, gutters, windows, fencing, and detached buildings may all need inspection.
Heavy Rain and Water Intrusion
Dobbin’s location near Lake Creek and rural drainage areas makes heavy rainfall another concern. Intense thunderstorms can overwhelm ditches, creeks, culverts, and low-lying areas. National Weather Service advisories for Montgomery County regularly identify excessive rainfall as a cause of small-stream and low-area flooding.
Coverage depends heavily on the cause of the water.
For example, rain entering through a storm-created roof opening may be treated differently under a policy than surface flooding rising onto the property. Standard property policies commonly treat flood differently from other water losses, so identifying and documenting the actual cause is critical.
Common Insurance Claims in Dobbin
Hail Damage Claims
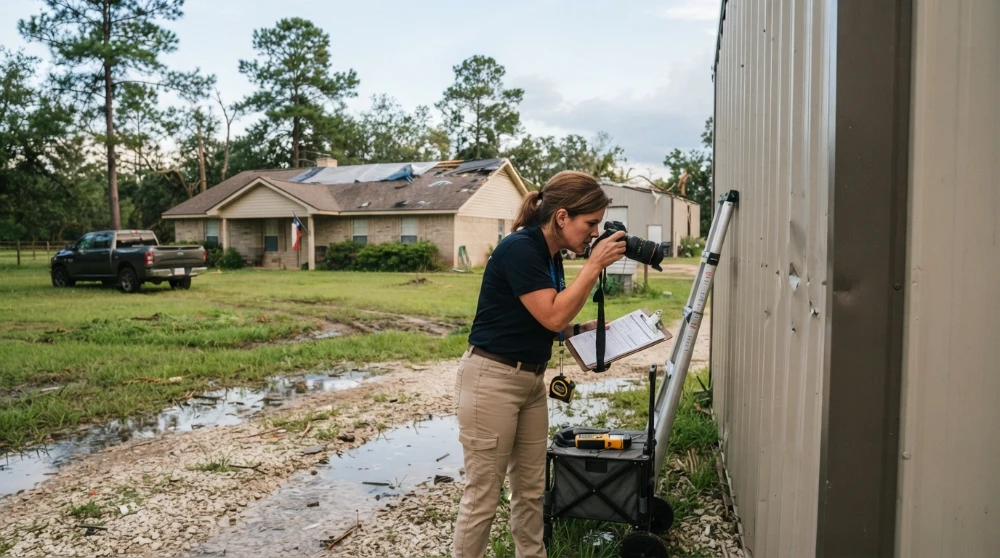
Hail claims are among the property losses where detailed documentation matters most. Damage can involve shingles, standing-seam metal roofing, gutters, downspouts, vents, window screens, siding, exterior lighting, fencing, HVAC equipment, and accessory structures.
We inspect the loss and compare the physical damage with the insurance company’s scope to determine whether covered items may have been overlooked. Property owners dealing with a hail damage roof insurance claim can also review our Texas guide explaining common roof damage, documentation issues, and claim scope problems.
Water Damage Claims
A burst pipe, plumbing failure, appliance leak, roof opening, or other sudden water event can damage much more than the immediately wet surface.
Depending on the loss, the claim may involve drywall, insulation, flooring, cabinets, baseboards, electrical components, personal property, drying equipment, demolition, and reconstruction.
We help document both the source and the resulting property damage. If the carrier’s estimate appears incomplete, learn how a water damage public adjuster can help evaluate the scope of a Texas water loss.
Fire and Smoke Damage Claims
Fire claims can involve structural damage, smoke residue, soot, odor, contents, electrical systems, HVAC contamination, demolition, debris removal, and temporary living expenses.
A small visible burn area does not necessarily mean a small insurance claim. Smoke and heat can travel well beyond the point where the fire originated.
TX Public Adjusting reviews the complete scope so the claim is not limited only to the most obvious burned materials. For larger losses, our guide to working with a fire insurance adjuster explains how fire and smoke property claims are evaluated and documented.
Storm and Wind Damage Claims
Thunderstorm and wind claims around Dobbin may affect roofing, trees, siding, windows, exterior structures, fences, garages, barns, and interiors exposed to rain.
When wind damages several parts of a rural property, every insured structure should be considered rather than focusing exclusively on the main house.
Roof Damage Claims
A roof claim may involve asphalt shingles, metal panels, flashing, vents, decking, ridge materials, gutters, or related components.
Carriers sometimes estimate a localized repair while contractors identify a larger repair problem. Our role is to document the actual damage and evaluate the insurance scope against the covered loss and applicable policy provisions. Learn more about when a public adjuster for a roof claim may help when a roof settlement is denied, disputed, or underpaid.
Commercial Property Claims
Dobbin and the surrounding Highway 105 corridor include businesses, agricultural properties, churches, shops, service buildings, storage facilities, and other commercial structures.
Commercial claims can become more complicated because the loss may affect roofing, building systems, inventory, equipment, tenant improvements, or business operations at the same time.
Our commercial public adjusting services help property owners organize these moving parts into one documented claim, including building damage, equipment, contents, and other covered components of the loss.
Why Dobbin Insurance Claims Become Underpaid
An underpaid claim does not always begin with an obvious dispute. Sometimes the problem starts with a short inspection followed by an estimate that simply leaves things out.
Missed or Hidden Damage
Roof damage may not be visible from the driveway. Moisture can travel behind walls. Smoke residue can extend into rooms far from a fire. Wind can affect flashing and roof accessories without leaving dramatic exterior evidence.
The inspection needs to match the complexity of the loss.
Scope Omissions
A carrier’s estimate may recognize one damaged item but omit related work needed to complete the repair.
For example, the estimate may include shingles while overlooking damaged vents, flashing, gutters, detach-and-reset operations, interior water damage, or another insured structure on the property.
Small omissions add up.
Depreciation Problems
Insurance estimates may contain recoverable and nonrecoverable depreciation depending on the policy and damaged item.
Property owners frequently receive a payment without understanding why money was withheld or what must happen before additional funds may become available.
We review how depreciation was applied and help the policyholder understand the claim documents.
Low Repair Estimates
Labor, material quantities, repair methods, measurements, and necessary construction operations can all affect the cost of restoring property.
When the carrier scope does not match what qualified contractors are finding at the site, the estimate deserves closer review.
Documentation Gaps
Photographs alone do not always establish the full claim.
Supporting documentation may include measurements, inventories, invoices, repair estimates, mitigation records, receipts, expert information, damaged-material photographs, and communications with the insurer.
A stronger claim file makes it easier to explain why a supplement or correction is justified.
Our Public Adjusting Process for Dobbin Claims
Step 1: Claim Review
We start by learning what happened and reviewing the available claim information. If you already have an insurance estimate, payment letter, denial, photographs, contractor estimate, or policy documents, we evaluate them for potential issues.
Step 2: Property Inspection
Next, we inspect the damaged areas of the Dobbin property.
For larger rural losses, that can mean looking beyond the residence to garages, barns, workshops, fences, exterior systems, or other insured structures affected by the same event.
Step 3: Damage Documentation
We organize photographs, measurements, repair information, estimates, inventories, and supporting documentation into a clear claim presentation.
The goal is to establish what was damaged, how the damage relates to the loss, and what the reasonable repair scope should include.
Step 4: Claim Presentation and Negotiation
TX Public Adjusting communicates with the carrier and presents the documented scope on behalf of the policyholder.
When appropriate, we address missed items, estimate differences, supplemental damage, and other disputed components of the claim.
Step 5: Settlement and Claim Resolution
We continue working through the adjustment process as the carrier evaluates the documentation.
Every insurance claim is different, and no public adjuster can guarantee a particular outcome. Our job is to make sure your position is properly documented and presented under the terms of the policy.
Already have an insurance estimate? Get a Free Claim Review before assuming the carrier’s scope is complete. TX Public Adjusting charges no upfront fees for the review.
Why Choose TX Public Adjusting for a Dobbin Property Claim
Texas-Focused Experience
Texas weather produces a distinctive mix of hail, wind, tropical weather, freeze, fire, and water claims. Working extensively within the state gives our team practical experience with the losses Texas property owners face.
Licensed Public Adjusting Representation
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839.
When you hire a public adjuster, you are choosing someone whose responsibility is to represent the policyholder’s interests during the property claim—not the insurance company’s.
Residential and Commercial Claim Experience
We work with homeowners as well as owners of commercial, multifamily, agricultural, retail, warehouse, church, and other properties.
That experience is particularly useful around Dobbin, where one insured location may contain several structures with different construction types.
Thousands of Claims Reviewed
Our team brings experience from reviewing thousands of property claims.
That volume matters because claim problems repeat: missed roofing components, incomplete water scopes, overlooked contents, improper measurements, missing exterior damage, and disagreements over necessary repair operations.
Independent Representation
The insurance company already has professionals evaluating the loss for the carrier.
A public adjuster gives the policyholder experienced representation on the other side of that process.
Areas We Serve Near Dobbin
Dobbin sits in western Montgomery County near several communities that share the Highway 105 and FM 1486 travel corridors. Nearby populated places include Montgomery, Plantersville, Magnolia, Todd Mission, Richards, Pinehurst, and Stagecoach. Smaller local areas around Dobbin include Bobville, Peel Junction, Gary, Blackberry, and Dacus.
TX Public Adjusting assists property owners throughout this part of Southeast Texas and across the state.
Frequently Asked Questions About Public Adjusters in Dobbin
What does a public adjuster in Dobbin do?
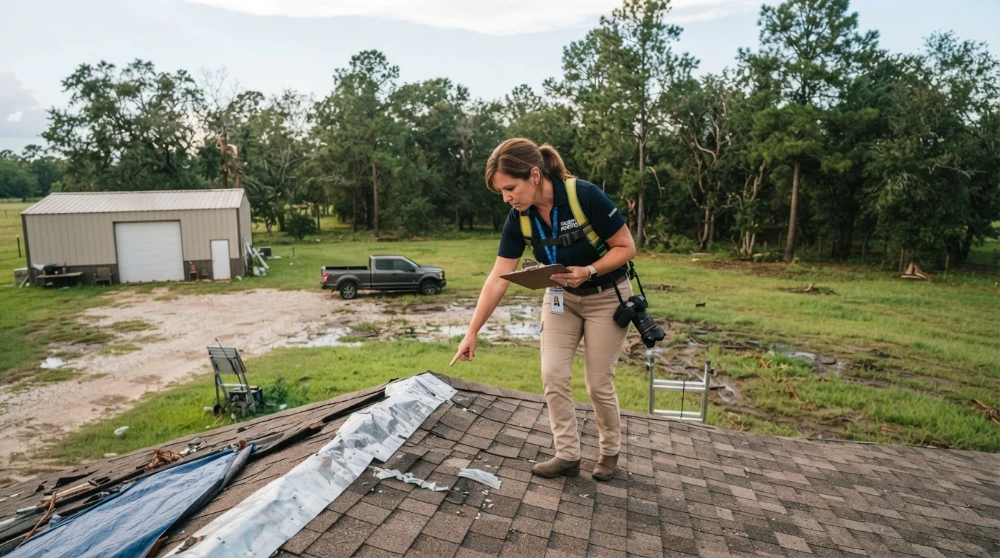
A public adjuster represents the policyholder during a property insurance claim. That can include inspecting damage, reviewing the policy and carrier estimate, preparing documentation, identifying missing items, communicating with the insurer, and negotiating the covered scope.
The important distinction is who the adjuster represents. The insurance carrier’s adjuster works within the carrier’s claim process. TX Public Adjusting works for the property owner.
When should I hire a public adjuster after storm damage in Dobbin?
You can contact a public adjuster shortly after the loss or later if problems develop. Early involvement can be useful when hail, wind, or falling trees have damaged several buildings or when substantial interior water intrusion is involved.
You may also benefit from a review after receiving a low estimate, partial denial, or settlement that does not appear to cover the documented repairs.
Can you review a claim after the insurance company has already paid me?
Potentially, yes. An initial payment does not necessarily mean every issue relating to the claim has been resolved.
We can review the carrier’s estimate, payment documentation, photographs, and available repair information to look for potentially omitted or disputed damage. Policy terms, deadlines, releases, prior settlements, and the individual claim history can affect what options remain.
What types of storm claims are common around Dobbin?
Hail, strong thunderstorms, wind, falling trees, heavy rainfall, water intrusion, and tornado-related damage are all relevant risks in Montgomery County. Tropical systems can also bring heavy rainfall and strong winds inland even though Dobbin is not on the coast.
Because rural properties may include several structures, one storm can create damage to the residence, garage, workshop, barn, fencing, roofing, and exterior equipment at the same location.
Can a public adjuster help with a hail-damaged metal roof?
Yes, when the damage is part of a covered property claim. Metal roofs require careful inspection because hail and wind may affect panels, seams, fasteners, flashing, vents, coatings, or other components.
We document the observed condition and evaluate how the insurer addressed it in the claim scope.
Does homeowners insurance cover flooding in Dobbin?
Coverage depends on the source of the water and the policies you carry. Surface flooding is generally treated differently from water entering because a covered storm damaged the building.
That distinction can be critical after heavy rainfall. We review the cause of loss and available policy information rather than assuming every type of water damage is covered in the same way.
Can you help with a ranch, barn, workshop, or detached structure claim?
Yes, provided the damaged property and cause of loss fall within the applicable insurance coverage.
Dobbin’s rural property mix makes detached structures especially relevant. During our review, we look at the insured property as a whole rather than assuming the only meaningful damage is to the main residence.
What if my insurance company says my roof only needs a repair?
A repair recommendation should be compared with the actual site conditions, the policy, the extent of covered damage, and the work reasonably required to restore the damaged property.
If your roofer or contractor believes the carrier’s scope is incomplete, we can review the claim and determine whether additional documentation should be submitted.
How long does a Dobbin property insurance claim take?
There is no single timeline. A straightforward claim with agreed damage may move relatively quickly, while a large commercial loss or disputed storm claim can take considerably longer.
Factors include the extent of damage, inspections, documentation, carrier response times, supplemental estimates, policy questions, and whether experts or additional investigation are required. Property owners waiting for an initial response can also read our guide explaining how long an insurance adjuster has to contact you after a claim is reported.
Is it too late to hire a public adjuster for an older Dobbin claim?
Not necessarily. Property owners sometimes contact us months after a storm because repairs revealed additional damage or because the original payment was insufficient.
However, insurance policies and Texas law can impose deadlines and other requirements. Older claims should be reviewed promptly rather than assuming nothing can be done. Our guide explains when it may be too late to hire a public adjuster and why timing matters after a property loss.
Get a Free Dobbin Insurance Claim Review
If your property in Dobbin has been damaged by hail, wind, water, fire, a severe thunderstorm, or another covered event, you do not have to evaluate the insurance company’s estimate by yourself.
TX Public Adjusting can review your existing claim, inspect the property, identify potential scope issues, organize supporting documentation, and represent you in communications concerning the covered loss.
TX Public Adjusting
Rise Public Adjusting LLC
Texas License #3356839
Free Claim Review
No Upfront Fees
Residential & Commercial Property Claims
Contact TX Public Adjusting and find out whether your Dobbin property claim deserves a closer look.