Property damage in Brookshire can turn into an insurance dispute quickly. Hail can bruise shingles and damage soft metals, straight-line winds can lift roofing or drive rain through openings, and a plumbing or fire loss can spread damage well beyond the room where it started. If you need a public adjuster in Brookshire, TX, TX Public Adjusting represents you—the policyholder—by inspecting the loss, documenting the damage, reviewing the insurance company’s estimate, and negotiating the property claim on your behalf.
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839. We assist residential and commercial property owners with new, underpaid, delayed, and disputed insurance claims throughout Texas.
Brookshire sits in Waller County, west of the Houston and Katy area along the I-10 corridor. The city had an estimated population of 5,495 in 2024, but its property market reaches beyond the historic town center into growing residential and industrial areas surrounding Highway 90 and Interstate 10.
Free Claim Review • No Upfront Fees • Residential & Commercial Claims
If your carrier’s estimate seems too low, an inspection missed visible damage, or you simply want a second set of experienced eyes on the claim, contact TX Public Adjusting for a free claim review before accepting a settlement you believe may not reflect the full documented loss.
Brookshire Property Claims Have a Distinct Local Risk Profile
Brookshire may be west of central Houston, but property owners here still deal with several Southeast Texas weather threats. The local risk is not theoretical. National Weather Service storm records document 1.75-inch hail roughly three miles south-southwest of Brookshire in March 2013, with reports of apartment windows being broken and hail accumulating on the ground. Earlier records also show hail reported in Brookshire itself.
Strong wind is another concern. In May 2020, a 52-knot thunderstorm wind gust was measured southeast of Brookshire at Houston Executive Airport. A separate 2017 severe-weather event included a brief tornado reported between Fulshear and Brookshire.
Flood exposure also varies considerably across Waller County. A 2024 Texas Water Development Board study identified hundreds of structures at risk within the county’s Brazos River floodplain under a 1% annual-chance event, with much of the structural exposure concentrated in southern Waller County below I-10.
| Brookshire Risk | Property Damage We Commonly Look For | Claim Concerns |
| Hail | Shingles, metal roofing, vents, gutters, windows, siding, HVAC equipment | Damage omitted from the carrier’s scope or treated as cosmetic |
| Straight-line wind | Lifted roofing, flashing, fencing, exterior finishes, openings | Repair-only estimates that may not address the complete damaged area |
| Heavy rain | Roof leaks, ceiling stains, drywall, flooring, insulation | Determining the cause and documenting the path of water intrusion |
| Tropical systems | Wind-driven rain, roof and exterior damage, debris impact | Multiple causes of loss within the same storm event |
| Fire and smoke | Structure, contents, soot, odor, electrical components | Incomplete inventories and overlooked secondary damage |
| Plumbing losses | Drywall, cabinets, flooring, insulation, contents | Moisture migration and damage extending beyond the visible leak |
Tropical systems can also reach Brookshire after moving inland from the Gulf Coast. Hurricane Beryl, for example, made landfall near Matagorda in July 2024 before moving through Southeast Texas. Inland communities can still experience wind, heavy rain, and related property damage from these systems.
Coverage always depends on the specific policy and cause of loss. Rising surface water, for example, may be handled differently from rain entering through a storm-created opening or a sudden plumbing failure. Our role is to document what happened and evaluate the claim against the policy that applies to the property.
Why Property Owners Hire a Public Adjuster in Brookshire
An insurance company’s adjuster investigates the claim for the carrier. A public adjuster works for the policyholder. Property owners who want a deeper explanation of the different roles can read our comparison of a public adjuster vs. independent adjuster.
That difference becomes especially important when a Brookshire property has multiple damaged components or the carrier’s estimate does not match what the owner, contractor, or other professionals are seeing.
Property owners often call us when:
- A roof or storm claim was paid far below the expected repair scope.
- The insurance inspection seemed rushed or incomplete.
- Hail damage was called cosmetic or attributed to wear and tear.
- Interior damage was paid but the source of the water intrusion was not fully addressed.
- A fire claim involves structure, contents, smoke, soot, and temporary expenses.
- The insurer omitted damaged materials from its estimate.
- A commercial property claim involves a large roof system, inventory, equipment, or multiple buildings.
- The claim has become difficult to manage alongside work, family, or business operations.
- A prior claim was denied or closed and the owner wants the file reviewed.
TX Public Adjusting brings experience from reviewing thousands of property claims, including both residential and commercial losses. We focus on the details that determine the scope of the claim—not simply the most obvious damage.
Common Insurance Claims in Brookshire
Hail Damage Claims
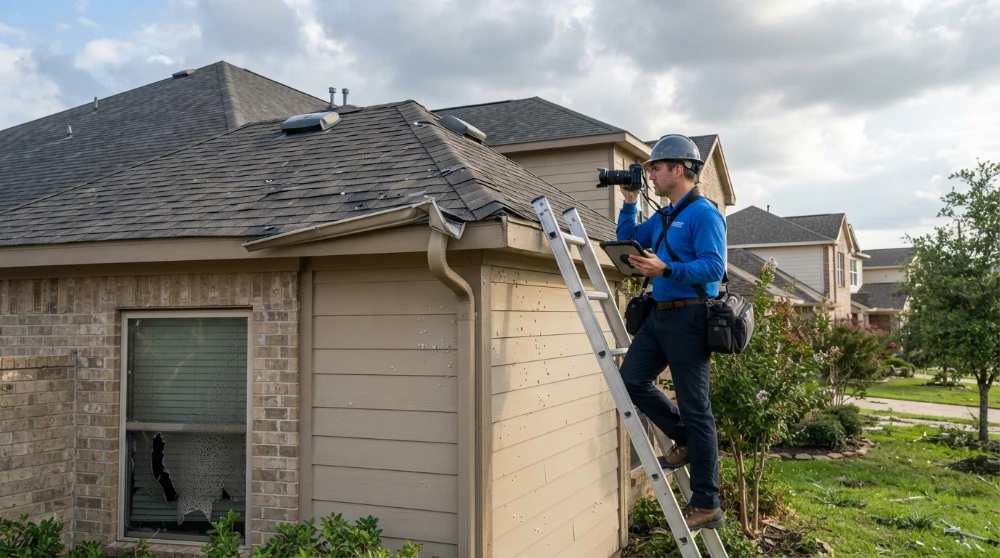
Hail deserves special attention in Brookshire because documented local storms have produced hail large enough to damage windows and exterior building components.
A hail claim should not stop at a quick look at the shingles. Depending on the property, an inspection may need to address:
- Asphalt shingles or metal roofing
- Ridge caps and roof accessories
- Gutters and downspouts
- Window screens and glazing
- Siding and exterior finishes
- Fence staining or impact
- HVAC fins and rooftop equipment
- Metal vents, flashing, and other soft metals
- Commercial roof membranes
Property owners dealing with a hail damage roof insurance claim should document more than the obvious shingle impacts. Gutters, flashing, vents, siding, windows, HVAC equipment, and other exterior components may also show storm damage.
The problem we frequently see in hail claims is a narrow scope. Property owners can also review our guide on how to document hail damage for an insurance claim before damaged materials are repaired or discarded. An estimate might acknowledge one damaged component while leaving surrounding or related materials out. A Brookshire public adjuster can compare the physical damage, photographs, measurements, and carrier estimate to determine what deserves a closer review.
Water Damage Claims
A leaking pipe, failed appliance connection, roof opening, or storm-related water intrusion can affect more of a building than the visible stain suggests.
Water can move behind drywall, beneath flooring, through insulation, into cabinets, and between rooms. By the time materials begin swelling or finishes discolor, the actual affected area may be larger than the first estimate indicates.
For Brookshire water damage claims, documentation may include the source and path of the water, damaged building materials, mitigation work, photographs, measurements, and repair requirements. A water damage public adjuster can also review whether the carrier’s scope accounts for damage extending beyond the visibly wet area.
Not every type of water loss is covered the same way. Flooding from rising surface water is a different coverage issue from a sudden plumbing loss or certain forms of storm-created water intrusion. The policy and facts of the loss control the analysis.
Fire Damage Claims
A fire claim is rarely limited to what burned. Smoke, soot, heat, water, and damaged contents can expand the scope substantially, which is why working with an experienced fire insurance adjuster for the policyholder can be valuable on larger losses.
Smoke and soot can travel through rooms that were never touched by flames. Heat may damage electrical systems, finishes, appliances, and nearby materials. Water used for suppression can create additional cleanup and restoration work.
Our fire claim review may address:
- Structural fire damage
- Smoke and soot contamination
- Contents and personal property
- Odor-related damage
- Electrical components
- Drywall and insulation
- Flooring and finishes
- Water from firefighting efforts
- Debris removal
- Applicable temporary living or operating expenses under the policy
Detailed inventories are particularly important. Once damaged contents are discarded without proper documentation, proving what existed and what condition it was in can become harder.
Storm and Wind Damage Claims
Severe thunderstorms can produce damaging wind even when there is no tornado. Brookshire-area weather records include significant measured thunderstorm winds as well as a brief tornado between Brookshire and Fulshear.
Wind losses can involve roof coverings, flashing, gutters, fences, siding, windows, exterior equipment, and interior water damage after an opening develops.
A carrier estimate may focus on the most obvious missing shingles while failing to address less visible lifting, surrounding components, resulting water damage, or other storm impacts. That is why a complete inspection matters.
Roof Damage Claims
Roof claims are among the most disputed property claims because several causes can produce similar-looking conditions.
The carrier may attribute a problem to age, maintenance, installation, deterioration, or prior damage. A property owner may believe the condition resulted from a recent hail or wind event.
A public adjuster does not simply assume every roof condition is storm damage. When a carrier’s roof estimate does not appear to address the full documented loss, a public adjuster for a roof claim can compare the insurer’s scope with the roof conditions, related components, and supporting claim documentation. We document what is present, review the reported date and cause of loss, compare the carrier’s findings with the physical evidence, and identify portions of the scope that may need additional consideration.
Brookshire contains a mix of established properties and newer construction in the surrounding 77423 market. Communities in and around the Brookshire area include Willow Creek Farms, Kingsland Heights, and Crystal Lakes, in addition to older homes and businesses near Downtown Brookshire and the Highway 90 corridor.
Different building ages, roofing systems, exterior materials, and construction methods can produce very different storm-loss scopes.
Commercial Property Claims
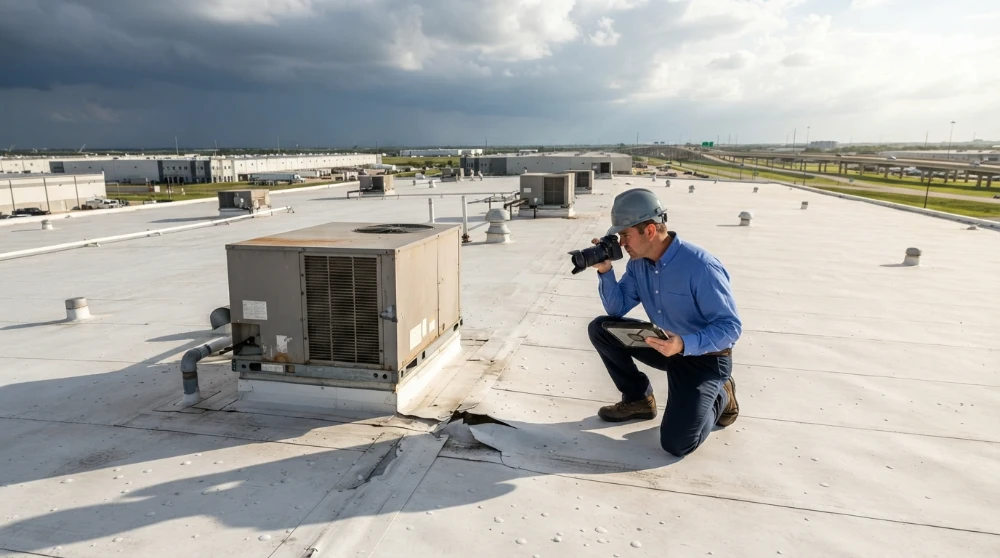
Brookshire’s location along I-10 and Highway 90 has also made the area increasingly significant for industrial and distribution development. Projects such as Empire West and other business parks along the corridor include substantial warehouse and distribution space.
A commercial claim can be far more involved than a residential loss. We may need to evaluate:
- Large low-slope or membrane roofs
- Metal roofing systems
- Rooftop HVAC units
- Loading areas and exterior building components
- Interior finishes
- Equipment and business personal property
- Multiple tenant spaces
- Warehouses and distribution facilities
- Retail or office property
- Documentation related to covered operational impacts
Large commercial roofs are a good example of why small omissions matter. Missing a damaged roof section, insulation layer, flashing component, drainage item, or rooftop unit can materially change the overall scope.
Have an underpaid Brookshire property claim? TX Public Adjusting offers a Free Claim Review with no upfront fees. We can review the carrier estimate, photographs, claim documents, and visible damage to identify issues that may deserve further attention.
Why Insurance Claims Become Underpaid
An underpaid claim does not always result from one major mistake. More often, several smaller omissions add up.
Missed Damage
A carrier inspection may not identify every affected component. Roof accessories, soft metals, exterior elevations, hidden water damage, or secondary rooms can be overlooked.
Scope Omissions
The estimate may recognize damage but leave out related work necessary to restore the property. That can include removal, access, disposal, detach-and-reset operations, adjoining materials, or other components affected by the repair.
Depreciation Issues
Depreciation can significantly affect an initial payment. Property owners sometimes have questions about how depreciation was calculated or what documentation is required to recover amounts that may be available under their policy.
Low or Incomplete Estimates
Two estimates can differ because they include different quantities, materials, labor operations, or assumptions about what needs to be repaired.
We compare the carrier’s scope against the documented property damage instead of focusing only on the total dollar figure.
Documentation Problems
An otherwise valid claim can become difficult when there are too few photographs, no detailed contents inventory, missing invoices, incomplete mitigation records, or poor documentation of the original condition.
Strong claim documentation makes the loss easier to explain and support.
Our Public Adjusting Process
Our Brookshire claim process is designed to turn a complicated insurance file into a documented, organized presentation of the loss.
| Step | What We Do |
| 1. Claim Review | We review your policy situation, carrier correspondence, estimates, photographs, payments, and concerns about the claim. |
| 2. Property Inspection | We inspect the reported damage and identify areas that may require additional documentation. |
| 3. Documentation & Scope | We organize photographs, measurements, inventories, estimates, and other supporting information relevant to the loss. |
| 4. Carrier Communication & Negotiation | We present the documented claim and communicate with the insurance company on your behalf. |
| 5. Settlement Review | We review carrier responses and payments against the documented scope and continue addressing unresolved claim items as appropriate. |
Every claim is different. A Brookshire hail claim on a single-family home may require a different approach from a commercial storm loss along the I-10 corridor or a fire claim involving both structure and contents.
The objective stays the same: document the loss carefully and advocate for the policyholder under the applicable insurance policy.
Why Choose TX Public Adjusting
Licensed Texas Public Adjuster
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839.
We Represent Policyholders
We do not work for the insurance carrier on your claim. Our responsibility is to the property owner who hires us.
Texas-Focused Experience
Texas property claims frequently involve hail, wind, hurricane-related damage, water losses, fires, roof disputes, and large commercial losses. Our experience includes reviewing thousands of claims across residential and commercial properties.
Residential and Commercial Claim Experience
We work with homeowners as well as owners and operators of warehouses, retail properties, multifamily buildings, restaurants, churches, offices, industrial facilities, and other commercial properties.
That experience is particularly relevant in Brookshire, where traditional residential areas now sit near expanding warehouse and distribution development along I-10 and Highway 90.
Detailed Claim Documentation
A claim is stronger when the damage can be explained clearly. We focus on photographs, measurements, estimates, inventories, documentation, and the connection between the physical loss and the claim being presented.
Free Claim Review and No Upfront Fees
You can have us review the situation before deciding how to proceed. There are no upfront fees for the initial claim review.
Brookshire Landmarks and Property Areas We Know
Brookshire is compact, but the local property landscape is varied. The Brookshire Convention Center, the Brookshire-Pattison Library, Downtown Brookshire, and public facilities around the Waller County Annex provide recognizable anchors near the traditional center of the community.
Outside the historic center, the I-10 and Highway 90 corridors increasingly include newer subdivisions, warehouses, distribution buildings, and other commercial development. That mix means a Brookshire insurance claim might involve anything from an older residential roof to a newer suburban home or a large commercial roof system.
Local familiarity does not replace the policy or evidence, but it helps us understand what kinds of structures and storm exposures we are likely to encounter.
Areas We Serve Near Brookshire
TX Public Adjusting assists property owners in Brookshire and surrounding communities across western Greater Houston and Waller County, including:
- Pattison
- Waller
- Katy
- Fulshear
- Simonton
- Sealy
- Hockley
- Rural areas throughout Waller County
Brookshire is positioned approximately seven miles west of Katy along the I-10 corridor, making it closely connected to the rapidly developing western Houston market.
Frequently Asked Questions About Public Adjusters in Brookshire
What does a public adjuster in Brookshire do?
A public adjuster represents the property owner during an insurance claim. We inspect damage, review the policy and carrier estimate, document the scope of loss, organize supporting information, communicate with the insurance company, and negotiate the claim for the policyholder.
That is different from the insurance company’s adjuster, who is handling the claim for the carrier.
When should I call a public adjuster after a Brookshire hailstorm?
You can contact a public adjuster early in the claim if the damage appears significant or the loss involves several building components. You can also call after the insurance company has inspected if the estimate seems incomplete.
The sooner the property is properly documented, the easier it usually is to preserve photographs, damaged materials, invoices, and other evidence.
Can you help after the insurance company has already inspected my property?
Yes. Many Brookshire property owners contact us after the carrier’s inspection.
We can review the estimate, photographs, payment information, and physical damage to determine whether the scope appears to omit items that deserve further documentation. The fact that an insurer has already inspected the property does not automatically mean every damaged item was identified.
Can TX Public Adjusting review an underpaid roof claim?
Yes. Underpaid hail, wind, and roof claims are a major part of our work.
We compare the carrier’s estimate with the documented condition of the roof and related components. Depending on the loss, that can include shingles, metal, flashing, vents, gutters, exterior finishes, and resulting interior damage.
Does a public adjuster work for my insurance company?
No. A public adjuster is hired by the policyholder.
TX Public Adjusting represents homeowners and commercial property owners, not the insurance carrier. That independent representation is one of the primary reasons owners hire a public adjuster when the claim becomes disputed or difficult to manage.
What types of Brookshire properties do you handle?
We assist with both residential and commercial property claims.
That includes homes, rental properties, retail spaces, warehouses, distribution facilities, offices, multifamily properties, restaurants, churches, and other insured buildings. Brookshire’s combination of established residential neighborhoods and growing industrial development makes experience with both types of claims especially useful.
Can you help with a water damage claim in Brookshire?
Yes. We handle covered water-damage claims involving issues such as sudden plumbing losses, appliance failures, and certain storm-related water intrusion.
The source of the water matters because policies treat different causes differently. We document the affected materials and circumstances of the loss while reviewing the coverage that applies to the specific claim.
How much does it cost to have TX Public Adjusting review my claim?
The initial claim review is free, and there are no upfront fees.
If representation makes sense for your situation, the fee structure and terms are explained before you sign an agreement. You should understand the arrangement before authorizing any public adjuster to represent your claim.
Is it too late to hire a public adjuster if my claim was denied or closed?
Not necessarily. A denied, underpaid, or closed claim may still deserve a review, but the available options depend on the policy, claim history, circumstances, and applicable deadlines. Our guide explaining when it is too late to hire a public adjuster covers this issue in more detail.
Contacting us promptly gives us a better opportunity to examine the documents and determine what options may still be available rather than allowing additional time to pass.
What should I do immediately after property damage in Brookshire?
Start with safety. Take reasonable steps to prevent additional damage when it is safe to do so, photograph the property before major cleanup when possible, preserve damaged materials when practical, keep receipts and invoices, and report the loss according to your policy requirements.
Avoid throwing away important evidence too quickly. For a significant hail, wind, water, fire, or commercial property loss, a detailed claim review early in the process can help identify documentation gaps before they become harder to correct.
Get a Free Brookshire Insurance Claim Review
If your Brookshire property was damaged by hail, wind, water, fire, a severe storm, or another covered event, you do not have to rely solely on the insurance company’s assessment of the loss.
TX Public Adjusting can review the damage, carrier estimate, claim documents, and payment history and explain what we see.
TX Public Adjusting
Rise Public Adjusting LLC
Texas License #3356839
Free Claim Review • No Upfront Fees • Residential & Commercial Claims
Contact TX Public Adjusting before accepting a settlement you believe may not reflect the full documented damage to your Brookshire property.