

Property damage in Sienna Plantation can turn into a complicated insurance claim quickly. A severe thunderstorm can damage roofing and fencing in one afternoon; tropical systems can bring high winds and wind-driven rain; plumbing failures can affect multiple rooms before the leak is discovered. When the carrier’s estimate does not reflect the full scope of damage, a public adjuster in Sienna Plantation, TX can represent the policyholder and help document what the claim should actually include.
TX Public Adjusting represents residential and commercial property owners throughout Texas. We work for policyholders—not insurance companies. Our team reviews policies, inspects damaged property, prepares claim documentation, evaluates insurance estimates, and communicates with carriers throughout the adjustment process.
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839. If your Sienna Plantation property claim has been underpaid, delayed, denied, or simply feels incomplete, contact us for a Free Claim Review with no upfront fees.
Sienna Plantation is now generally marketed simply as Sienna, a large master-planned community in eastern Fort Bend County near Missouri City and Sugar Land. The community has grown across thousands of acres near the Brazos River and includes extensive residential development, parks, recreation facilities, schools, lakes, trails, and commercial property.
Need help with an insurance claim? Contact TX Public Adjusting for a Free Claim Review.
Why Property Owners Hire a Public Adjuster in Sienna Plantation
An insurance claim involves more than pointing out visible damage and waiting for a check. The amount ultimately considered by the insurer can depend heavily on how the loss is inspected, scoped, measured, documented, estimated, and supported.
That matters in Sienna Plantation because many properties are substantial single-family homes with multiple roof slopes, attached garages, exterior structures, upgraded interiors, fences, outdoor living areas, and landscaping. Damage from one storm can involve several different components of the property at once.
A public adjuster provides an independent assessment from the policyholder’s side of the claim.
Property owners commonly contact TX Public Adjusting when:
- The insurance company estimate seems too low.
- Roof or storm damage was only partially approved.
- Important rooms, elevations, materials, or components were omitted.
- The carrier says certain damage is wear and tear rather than storm related.
- Water damage extends farther than the initial inspection documented.
- A commercial claim involves multiple trades or areas of damage.
- The claim has stalled or requires extensive supplemental documentation.
- The property owner does not have time to manage inspections, estimates, photographs, communications, and negotiations.
- A previously closed claim may need another review.
A carrier adjuster may be professional and experienced, but that adjuster works within the insurance company’s claim process. A public insurance adjuster in Sienna Plantation represents the insured property owner. Understanding the difference between a public adjuster vs. independent adjuster can help property owners understand who actually represents them during an insurance claim.
That distinction becomes especially important when thousands or tens of thousands of dollars in repairs may depend on the accuracy of a scope.
Property Damage Risks in Sienna Plantation and Fort Bend County
Sienna’s location in the Houston metropolitan region gives local property owners a different risk profile from homeowners in North Texas or the Hill Country.
The community lies in Fort Bend County, approximately southwest of Houston and near the Brazos River. Sienna is a large master-planned community with extensive residential development and neighborhood infrastructure.
Tropical Storm and Hurricane Damage
Fort Bend County is inland, but it is still part of the greater Houston region exposed to tropical weather.
A hurricane or tropical storm does not need to place Sienna Plantation directly on the coastline to create property losses. Strong winds and prolonged rainfall can result in:
- Missing or lifted shingles
- Roof membrane damage
- Damaged flashing
- Fence and gate damage
- Broken tree limbs
- Exterior impact damage
- Window or door intrusion
- Wind-driven rain
- Ceiling and drywall damage
- Attic moisture
- Damage to detached structures
One recurring claim issue is separating the source of water from the resulting damage. Wind-driven rain entering through storm-created openings can present different coverage questions from rising surface water. The policy language and documented cause of loss matter. Property owners dealing with tropical weather can also review our guide to property damage after a hurricane for additional information about documenting storm-related losses.
Severe Thunderstorms and Wind
Warm-season thunderstorms can move through the Houston region rapidly.
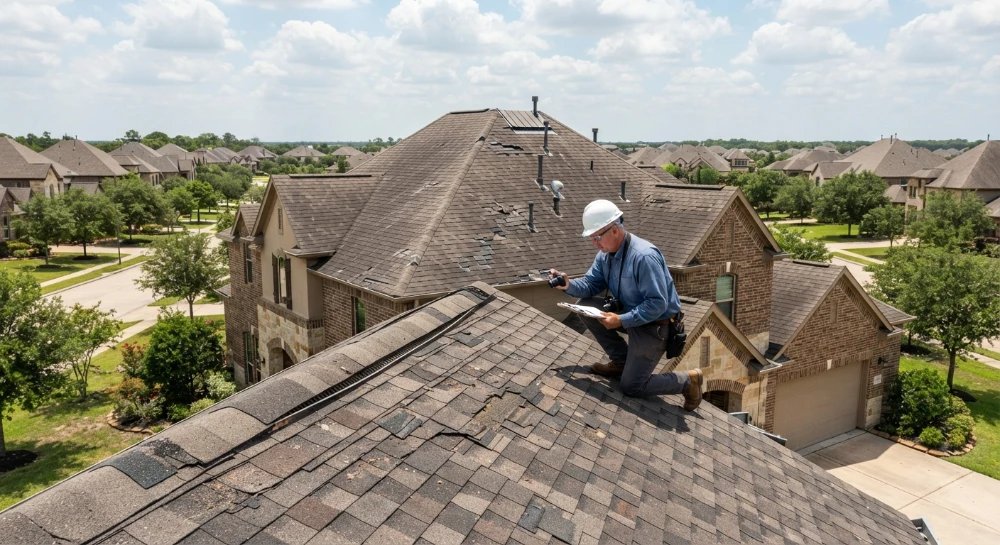
A property may look intact from ground level while roofing components have suffered lifted shingles, damaged ridge material, loosened flashing, displaced vents, or other storm-related effects.
Around communities such as Sawmill Lake, Avalon at Sienna, Village of Bees Creek, Sienna Point, and established sections of Sienna Plantation, roof configuration, age, material, tree exposure, and surrounding structures can all affect how storm damage presents.
Sienna contains numerous separately developed sections and neighborhoods, including established Sienna Plantation sections, Sienna Point, Sienna Acreage Estates, Sienna Crossing, and newer Sienna sections recorded within Fort Bend County.
Hail Damage
Sienna Plantation is not exposed to hail as frequently as some parts of the Dallas–Fort Worth region, but hail-producing thunderstorms still occur along the Gulf Coast.
Hail claims can involve more than shingles. We look at applicable damaged components such as:
- Asphalt roofing
- Metal roofing components
- Gutters and downspouts
- Roof vents
- Flashings
- Window screens
- Exterior trim
- Garage doors
- Fencing
- HVAC components
- Outdoor structures
Small dents or impact marks can be easy to dismiss individually. Across a large residential roof system, however, documentation of the entire affected area can become significant.
Water and Plumbing Damage
Water losses are another major source of property insurance claims in Sienna Plantation.
Leaks may originate from:
- Supply lines
- Plumbing fixtures
- Appliances
- Water heaters
- Drain systems
- Attic plumbing
- HVAC drain lines
- Roof openings
- Failed seals
A leak affecting one room can migrate beneath flooring, into cabinetry, through wall cavities, or down into lower floors.
The visible stain is rarely the entire scope.
Freeze-Related Damage
Houston-area property owners also learned during major Texas freezes that Gulf Coast homes can experience significant plumbing failures when temperatures remain below freezing long enough.
Burst supply lines can affect ceilings, insulation, drywall, flooring, cabinets, electrical components, personal property, and multiple rooms. When a home has extensive interior finishes, the resulting repair scope can become complicated quickly.
Common Insurance Claims in Sienna Plantation
Hail Damage Claims
A hail claim should be based on documented conditions, not assumptions from the ground.
TX Public Adjusting can review the carrier’s estimate against the observed damage and supporting documentation. When appropriate, the evaluation may include roofing materials, accessories, elevations, metal components, and related exterior property.
If your roof or exterior was affected by hail, our hail damage insurance claim guide explains how these losses are documented and evaluated.
Water Damage Claims
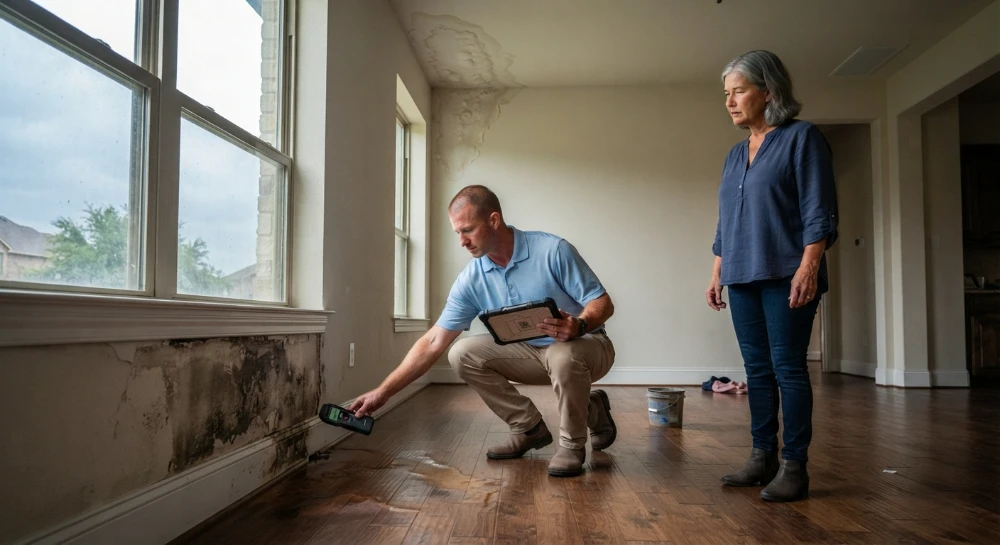
Water claims often become disputed because the cause, extent of migration, required removal, drying work, and resulting repairs are not always captured during the first inspection.
For example, water entering a kitchen may affect more than one cabinet box. Flooring may continue beneath cabinets or adjoining rooms. Wet insulation can be concealed behind finished surfaces.
A detailed scope helps identify what actually needs to be evaluated. For larger or disputed losses, a water damage public adjuster can help identify damage that may extend beyond the initially visible area.
Fire Damage Claims
Fire losses can involve structural damage, smoke contamination, soot, heat damage, water from firefighting efforts, electrical systems, personal property, debris removal, and temporary living issues.
The loss does not stop at the visibly burned area.
TX Public Adjusting has experience reviewing residential and commercial fire claims and organizing the documentation needed for complicated losses.
Our fire insurance adjuster guide explains how structural damage, smoke, soot, contents, and related losses are evaluated during a fire claim.
Storm Damage Claims
Storm claims around Sienna Plantation may combine roof damage, fencing, windows, trees, exterior finishes, interior water intrusion, and detached structures.
A single storm can therefore create several scopes under one claim.
The job of the public adjuster is to help make sure those components are identified and supported rather than treating the claim as only a roof inspection.
Roof Damage Claims
Roof claims are among the most frequently disputed property claims because roof conditions can involve overlapping questions about storm damage, age, maintenance, prior repairs, material availability, matching, and policy provisions.
We inspect and document the loss and compare the carrier’s conclusions with conditions at the property. Learn how a public adjuster for a roof claim can help when storm damage is overlooked, disputed, or underpaid.
Commercial Property Claims
Sienna has grown far beyond a residential subdivision. TX Public Adjusting handles both residential and commercial property claims throughout Sienna Plantation and the surrounding Fort Bend County area. The surrounding Sienna Parkway and Highway 6 areas include retail, professional services, schools, restaurants, medical users, multifamily property, and other commercial occupancies.
Commercial claims can involve:
- Building damage
- Roofing systems
- Interior finishes
- Equipment
- Tenant improvements
- Inventory
- Water mitigation
- Business-related coverage issues
- Multiple buildings or units
Commercial losses often require a much more detailed claim scope than a straightforward residential repair.
Why Insurance Claims Become Underpaid
An underpaid claim does not always begin with a dramatic denial.
More often, the problem is a collection of omissions.
Missed Damage
A short inspection may identify the obvious damage but overlook adjoining rooms, elevations, roof accessories, exterior items, insulation, cabinets, flooring transitions, or concealed moisture.
Scope Omissions
Even when damage is acknowledged, necessary repair activities can be left out of an estimate.
A scope should reflect the work reasonably required to repair covered damage—not merely the most visible material.
Depreciation Issues
Property claims frequently involve depreciation.
Policy provisions, replacement cost, actual cash value, recoverable depreciation, age, condition, and documentation can all affect how an estimate is presented and what may be recoverable.
We review these calculations as part of the claim rather than looking only at the bottom-line figure.
Low Estimates
Two estimates can describe the same property loss very differently.
The issue may involve measurements, labor operations, quantities, material selection, repair methodology, code-related considerations, or simply omitted line items.
Our job is to understand why the estimates differ.
Documentation Problems
Carriers make claim decisions based in part on the information in the file.
Poor photographs, missing measurements, incomplete inventories, unclear timelines, or unsupported supplemental requests can make a legitimate claim harder to evaluate.
That is why documentation is central to public adjusting.
Sienna Plantation Properties Require a Local Approach
Sienna is unusual compared with many Texas service areas because it functions almost like a city within a city.
The community spans approximately 10,800 acres according to the current Sienna master plan, and its amenities include extensive parks and trail systems as well as facilities such as Sawmill Lake Club and the 160-acre Camp Sienna sports complex.
That scale creates varied property characteristics.
A claim in an established portion of Sienna Plantation may involve an older roofing system and mature trees. A newer property near Sawmill Lake may have different roofing materials, elevations, finishes, and construction details. Acreage properties around Sienna Point present still another inspection environment.
Neighborhood and community references we serve include areas around:
- Sawmill Lake
- Avalon at Sienna
- Village of Bees Creek
- Sienna Point
- Sienna Acreage Estates
- Waters Lake
- Sienna Crossing
- Heritage Park
- Sienna Parkway
- Camp Sienna
The goal is not to assume that every Sienna Plantation claim looks the same. It does not.
Our Public Adjusting Process
Step 1: Claim Review
We start by understanding what happened.
That may include reviewing the policy, carrier correspondence, claim estimate, payment information, denial letters, photographs, contractor estimates, and prior documentation.
If you have already received an insurance estimate, we can compare it against the actual loss.
Step 2: Property Inspection
We inspect the affected property and document relevant damage.
Depending on the claim, that can involve roofing, exterior elevations, interior rooms, water-affected materials, fire damage, commercial spaces, or other components.
Step 3: Documentation and Scope Preparation
We organize the evidence needed to support the claim.
That can include:
- Photographs
- Measurements
- Damage descriptions
- Repair scope
- Estimates
- Contents information
- Supporting invoices
- Reports
- Claim correspondence
Step 4: Claim Presentation and Negotiation
We communicate with the insurance company on behalf of the policyholder within the scope of our Texas public adjusting license.
When the carrier’s estimate differs from ours, we work through those differences item by item.
Step 5: Settlement and Claim Resolution
Our objective is to help the policyholder pursue the insurance benefits supported by the policy and documented loss.
No public adjuster can guarantee a specific settlement. What we can provide is experienced claim preparation, documentation, analysis, and representation.
Already received a low estimate? Do not assume it is the final word. Request a Free Claim Review from TX Public Adjusting.
Why Choose TX Public Adjusting
TX Public Adjusting is built around property insurance claims in Texas.
Our team has experience reviewing thousands of claims across residential and commercial losses. We understand that a fire claim requires a different approach from a roof claim, and a multi-building commercial loss requires different documentation from a plumbing leak in a single-family home.
Property owners choose us because we provide:
- Licensed Texas Public Adjuster representation
- Rise Public Adjusting LLC
- Texas License #3356839
- Residential property claim experience
- Commercial property claim experience
- Storm, hail, roof, water, and fire claim knowledge
- Independent representation for the policyholder
- Detailed claim documentation
- Scope and estimate review
- Direct communication throughout the claim
- Free Claim Review
- No upfront fees
The insurance company has professionals handling its side of the claim.
You have the right to have a licensed professional working on yours.
Areas We Serve Near Sienna Plantation
TX Public Adjusting assists property owners throughout Sienna Plantation and surrounding Fort Bend County communities. Because Sienna is closely connected with Missouri City, property owners can also visit our Public Adjuster Missouri City page for local claim assistance. We also serve neighboring Sugar Land through our Public Adjuster Sugar Land page. For properties farther into the metropolitan area, our Public Adjuster Houston page covers the broader Houston service area.
Sienna itself is closely associated with Missouri City and sits only minutes from Sugar Land, making claims in these communities part of the same broader Fort Bend service corridor.
Frequently Asked Questions About Public Adjusters in Sienna Plantation
What does a public adjuster in Sienna Plantation do?
A public adjuster represents the insured property owner during a property insurance claim. We evaluate damage, review policy and claim documents, prepare supporting documentation, analyze estimates, and communicate with the insurance carrier about the scope and value of the loss.
Unlike the carrier’s adjuster, TX Public Adjusting represents the policyholder.
When should I hire a public adjuster after property damage in Sienna?
You can contact a public adjuster early in the claim, but property owners also hire us after receiving a low estimate, partial payment, denial, or request for additional documentation.
Getting involved earlier can make documentation easier because the property may not yet have undergone extensive cleanup or repairs. However, an existing claim may still be reviewable depending on its status and applicable deadlines. If your claim is already underway, see our guide explaining when is it too late to hire a public adjuster and the stages at which representation may still be possible.
Can you help if my Sienna Plantation roof claim was underpaid?
Yes. Roof claims are a major part of public adjusting work.
We can review the insurer’s roof measurements, scope, damage findings, photographs, line items, depreciation, and related exterior damage. If there are documented differences, we can present the claim information to the carrier and work through those issues.
Can a public adjuster help with hurricane or tropical storm damage in Sienna?
Yes, when the loss involves covered property damage under the applicable policy.
Storm losses may involve wind damage, damaged roofing, broken exterior components, fallen debris, or interior water intrusion associated with storm-created openings. Coverage depends on the actual policy and cause of loss, so those details need to be evaluated rather than assumed.
What if my insurance company says the damage is wear and tear?
A carrier may conclude that certain roof or building conditions result from age, deterioration, installation issues, or maintenance rather than a covered event.
That does not automatically mean every damaged component is excluded. We examine the property conditions, timing, documentation, and carrier findings to identify where additional evidence or clarification may be warranted.
Do you handle water damage claims in Sienna Plantation?
Yes.
We assist with covered water losses involving plumbing failures, appliance leaks, roof intrusion, and other property damage scenarios. Water can move far beyond the point where it first becomes visible, which makes careful documentation particularly important.
Do you work with commercial property owners near Sienna Parkway?
Yes. TX Public Adjusting handles both residential and commercial property insurance claims.
Commercial claims can involve offices, retail buildings, restaurants, multifamily property, warehouses, churches, and other insured properties. The documentation may include building damage, roofing, interiors, equipment, inventory, tenant improvements, and other applicable claim components.
Can you review a claim that has already been paid?
Potentially.
Receiving an insurance payment does not necessarily tell us whether every available claim issue has been resolved. We can review the carrier estimate, settlement documents, damage scope, and current claim status to determine whether there appear to be unresolved items that warrant further evaluation.
How much does it cost to have TX Public Adjusting review my claim?
The initial Claim Review is free, and there are no upfront fees for retaining TX Public Adjusting under our applicable engagement terms.
Before representation begins, the fee arrangement and public adjusting agreement are explained so you understand the terms.
Why hire a Sienna Plantation public adjuster instead of handling the claim myself?
Some small claims can be handled directly by a property owner. Larger or disputed claims become different.
A roof replacement, major water loss, fire, or commercial storm claim can involve hundreds of individual estimating decisions, extensive documentation, policy questions, depreciation, repair methodologies, and repeated carrier communication.
Hiring a public adjuster gives you a licensed professional focused on presenting the policyholder’s side of that process.
Get a Free Sienna Plantation Insurance Claim Review
You paid for insurance to protect your property. When damage occurs, the claim should be evaluated using a complete and properly documented picture of the loss.
If your Sienna Plantation home or commercial property has suffered hail, wind, storm, roof, water, fire, or other covered property damage, TX Public Adjusting can review what happened and help you understand the next step.
TX Public Adjusting
Rise Public Adjusting LLC
Texas Public Adjuster License #3356839
Free Claim Review. No upfront fees. Residential and commercial claims.
Contact TX Public Adjusting today to have your Sienna Plantation property insurance claim reviewed.