Property damage in Graham can turn into an insurance dispute faster than many property owners expect. A spring thunderstorm can leave hail marks across a roof, damage gutters and exterior metals, and drive rain through openings created by wind. A plumbing failure can spread water through several rooms. Fire and smoke losses can affect the structure, contents, electrical systems, and temporary living arrangements all at once. When the insurance company’s estimate does not reflect the full scope of the damage, a public adjuster in Graham, TX can represent the policyholder throughout the claim.
TX Public Adjusting helps Graham homeowners, business owners, commercial property owners, and other policyholders document and present property insurance claims. We are Rise Public Adjusting LLC, a licensed Texas public adjusting firm operating under Texas License #3356839. Our role is different from the insurance company’s adjuster: we represent the policyholder’s interests during the claim.
Graham is the Young County seat in North Central Texas, with a projected 2026 population of 8,839. Its compact downtown, established residential neighborhoods, commercial properties, ranching country, and nearby lake properties create a wide range of insurance-loss situations. When damage is significant, complicated, denied, or apparently underpaid, TX Public Adjusting can provide a free claim review with no upfront fees.
Have an insurance claim in Graham that does not look right? Contact TX Public Adjusting for a free claim review before accepting the carrier’s estimate as the final word.
Why Property Owners Hire a Public Adjuster in Graham
An insurance adjuster assigned by the carrier evaluates the loss for the insurance company. A public insurance adjuster is hired by the insured and can negotiate with the insurer on the policyholder’s behalf. The Texas Department of Insurance specifically describes public adjusters as licensed professionals who can help negotiate an insurance claim settlement.
That difference can matter after substantial property damage in Graham. An estimate may identify obvious shingle damage but leave out damaged gutters, vents, flashing, fencing, siding, interior water damage, or other affected components. With a water claim, the disagreement might involve how far moisture traveled, which building materials need to be removed, or what is required to restore the property. Fire claims can become even more detailed because structural damage, smoke, contents, debris removal, and temporary living expenses may all need separate documentation.
If you want a deeper explanation of what a public adjuster does, the role generally includes reviewing the claim from the policyholder’s side, inspecting the property, documenting damage, evaluating estimates, and communicating with the carrier. That means examining the property, reviewing available policy information, documenting damage, developing a scope, evaluating estimates, communicating with the carrier, and negotiating disputed claim items.
For Graham property owners who are already trying to protect a home, reopen a business, or coordinate repairs, professional claim representation can also remove a substantial administrative burden.
Graham Storm Risks and Property Damage
Graham’s location makes hail and severe thunderstorms especially relevant to local property claims.
That is not a theoretical concern. On May 9, 2026, the National Weather Service issued a severe thunderstorm warning covering Young County and specifically identified Graham in the storm’s path. The warning called for hail up to 1.5 inches and wind gusts up to 60 mph, with the NWS warning of potential roof, siding, window, vehicle, and tree damage.
Hail Damage in Graham
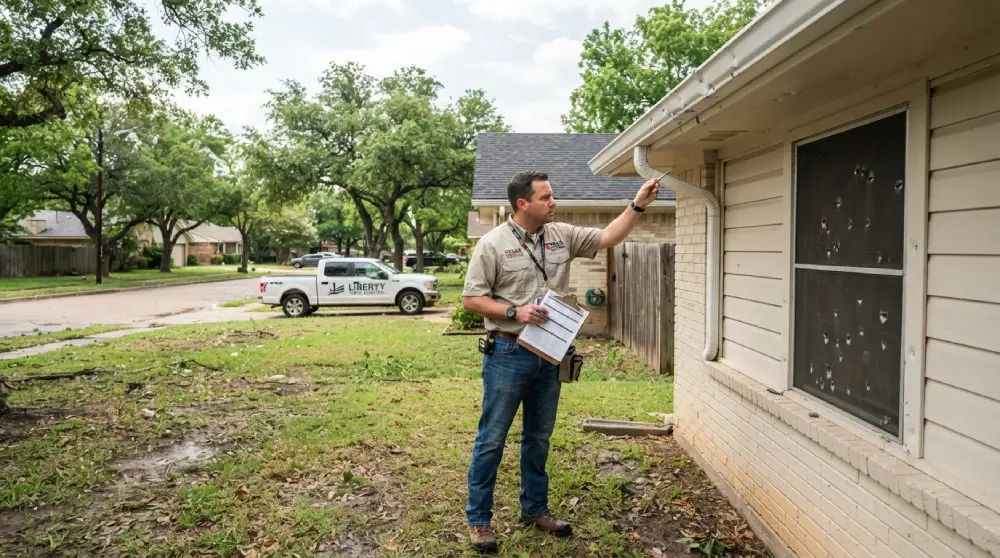
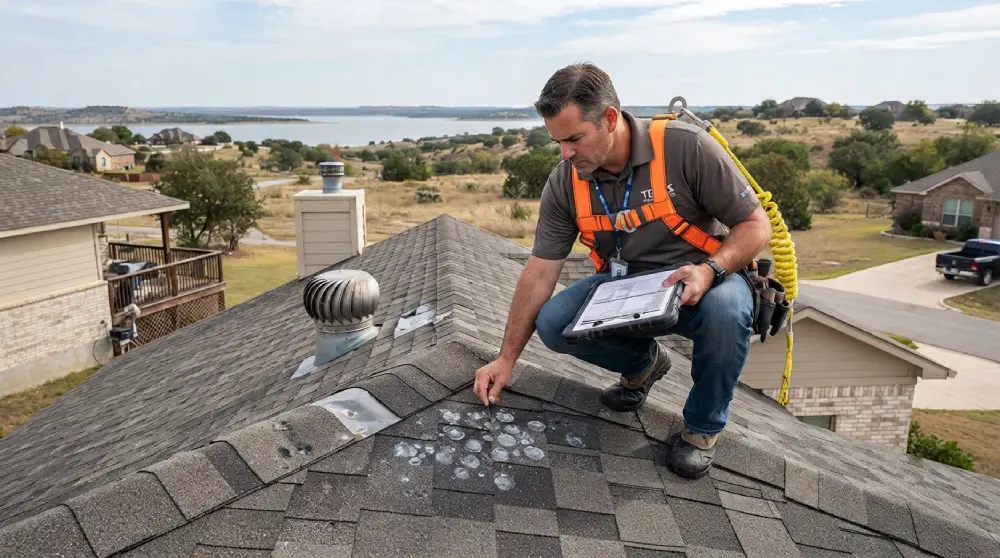
Hail can affect far more than shingles. A proper hail inspection may need to consider roofing materials, metal vents, flashing, gutters, downspouts, window screens, siding, fences, HVAC equipment, skylights, and other exterior surfaces.
One problem with hail claims is that damage is not always obvious from ground level. A roof may still appear intact even when impacts have affected shingles or roofing components. Commercial roofing systems can have an entirely different damage pattern from residential asphalt shingles.
For a Graham hail damage insurance claim, documenting the complete storm-related scope is often just as important as identifying the primary roof damage.
Wind and Storm Damage
Strong thunderstorm winds can lift roofing materials, loosen flashing, damage fences, break branches, and create openings that allow rain inside the building.
That combination can create a claim involving both exterior and interior damage. If the carrier treats only the visible roof issue while overlooking resulting water intrusion, the estimated repair scope may not restore the entire loss.
Water Damage
Graham water claims are not limited to thunderstorms. A water damage public adjuster can help review losses involving burst pipes, failed plumbing connections, appliance leaks, storm-created roof openings, and other covered water events. Burst pipes, failed plumbing connections, appliance leaks, roof openings, and other sudden water events can cause damage behind walls and beneath flooring.
A successful claim requires more than photographs of standing water. The cause of loss, affected materials, moisture migration, mitigation work, and necessary repairs may all become part of the documentation.
Freeze-Related Property Damage
North Texas cold snaps can also create property losses when plumbing freezes or pipes rupture. These claims can spread quickly because a broken supply line can release a significant amount of water before the property owner discovers it.
Coverage always depends on the individual policy and circumstances, but documenting the origin and resulting damage promptly can make the eventual claim much easier to evaluate.
Common Insurance Claims in Graham, TX
| Claim Type | Common Property Damage | Issues That Can Complicate the Claim |
| Hail Damage Claims | Shingles, metal roofing, vents, gutters, siding, windows, HVAC components | Damage missed during inspection, repair-versus-replacement disagreements, incomplete exterior scope |
| Water Damage Claims | Drywall, insulation, flooring, cabinetry, ceilings, contents | Hidden moisture, incomplete demolition scope, cause-of-loss disagreements |
| Fire Damage Claims | Structure, electrical systems, contents, smoke and soot contamination | Contents documentation, smoke damage, debris removal, repair scope |
| Storm Damage Claims | Roofs, siding, windows, fences, trees and interior finishes | Multiple types of damage from one weather event |
| Roof Damage Claims | Asphalt shingles, metal roofs, flashing, decking, vents and accessories | Missed components, low estimates, depreciation disputes |
| Commercial Property Claims | Roofing systems, interiors, equipment, inventory and business property | Large scopes, multiple trades, business interruption considerations |
Hail Damage Claims
For many Graham property owners, hail is one of the most relevant claim concerns. When a storm crosses Young County, neighboring houses can experience very different damage depending on roof orientation, construction, hail size, wind direction, and building materials.
TX Public Adjusting examines the loss as a whole instead of assuming every hail claim is simply a roofing claim.
Water Damage Claims
Water losses can become expensive when the initial visible area represents only part of the affected building materials. Documentation may need to establish what became wet, what was removed during mitigation, and what must be repaired or replaced to return the property to its pre-loss condition, subject to policy terms.
Fire Damage Claims
A serious fire claim can involve structure, contents, smoke, soot, debris, electrical damage, temporary relocation, and multiple contractors. Working with a fire insurance adjuster who represents the policyholder can help organize these moving parts into a documented claim presentation.
Storm and Wind Damage Claims
After a major thunderstorm, damaged roofing may be only one part of the loss. Wind can affect siding, exterior features, fencing, windows, trees, detached structures, and interior finishes when rain enters through a storm-created opening.
Roof Damage Claims
Property owners considering a public adjuster for a roof claim often do so because an incomplete roof scope can affect every later repair estimate. We review roofing materials and related components rather than evaluating only the most visible damaged area.
Commercial Property Claims
Graham’s downtown and surrounding commercial corridors include properties that can face significantly different claim issues from a single-family residence. A commercial public adjuster can assist with losses involving commercial roofing systems, multiple tenant spaces, equipment, inventory, specialized finishes, and other business property. Commercial roofing, multiple tenant spaces, equipment, inventory, specialized finishes, and operational interruptions can increase the complexity of the claim.
Property around Graham’s historic downtown square, for example, may require a very different claim scope from a newer commercial building or a rural property outside the city core. The City of Graham identifies the downtown area, National Theatre, Graham Drive-In, Young County Arena, and other community facilities among prominent local destinations.
Why Insurance Claims Become Underpaid
A low insurance payment does not always mean the dispute centers on the policy limit. Often, the real disagreement is the scope of damage: what happened, what was damaged, which repairs are necessary, and how much those repairs should reasonably cost.
Common problems include:
- Missed or overlooked damage during the carrier’s inspection
- Roofing accessories or exterior components omitted from the estimate
- Interior damage separated from the originating storm loss
- Depreciation calculations the policyholder does not understand
- Repair quantities that do not reflect actual measurements
- Pricing or labor assumptions that differ from the work required
- Incomplete contents documentation after fire or water losses
- Photographs and supporting records that do not clearly establish the loss
- Supplements that are never fully documented or pursued
- Property owners accepting the first estimate without realizing items are missing
A public adjuster’s job is not simply to argue that a claim should be higher. The stronger approach is to identify what is missing and support the requested scope with documentation.
If your Graham insurance payment seems low, TX Public Adjusting can review the estimate and damage before you decide what to do next. The initial review is free.
Our Public Adjusting Process
| Step | What We Do |
| 1. Claim Review | Review the existing claim, available policy information, carrier estimates, payments, correspondence, and known areas of dispute. |
| 2. Property Inspection | Inspect the Graham property and identify visible damage associated with the reported loss. |
| 3. Documentation | Build supporting documentation using photographs, measurements, estimates, inventories, reports, and other available evidence as appropriate. |
| 4. Claim Presentation & Negotiation | Present the documented scope and communicate with the insurance company regarding disputed or omitted items. |
| 5. Settlement | Work through the adjustment process toward resolution of the covered claim under the applicable policy. |
Every loss is different. A residential hail claim in College Heights will not necessarily require the same documentation as a commercial storm loss near downtown Graham or a large water loss near Lake Graham.
Local Claim Help Throughout Graham
Graham is not a sprawling metro, but property conditions vary considerably across the city and surrounding area. Local real-estate data identifies residential areas including Lakeview Hills, College Heights, Ridgeway, Shawnee Park, Mountain Heights, Country Club Estates, Roselawn, and Westridge.
That local mix matters during inspections. An established house beneath mature trees can experience wind and impact damage differently from a newer open-lot property. Lake-area homes may have different exterior exposures. Commercial buildings around the city core often use roofing and construction systems that require a different inspection approach from a residential shingle roof.
Graham’s downtown square and Young County Courthouse are central local landmarks, while the National Theatre and Graham Drive-In reflect the city’s distinctive built environment. Lake properties are also part of the broader Graham property market. Possum Kingdom Lake lies about 18 miles southeast of Graham, according to the Texas Water Development Board.
For us, localization is not simply adding “Graham” to a claim form. It means understanding that a residential hail claim in Lakeview Hills, a roof dispute in Country Club Estates, and a commercial loss near the downtown square can require very different documentation.
Why Choose TX Public Adjusting in Graham?
TX Public Adjusting focuses on property insurance claims throughout Texas. Our team has experience reviewing thousands of claims, including residential and commercial losses involving hail, wind, water, fire, roofing systems, and major property damage.
| Trust Factor | What It Means for Graham Property Owners |
| Licensed Texas Public Adjuster | Rise Public Adjusting LLC operates under Texas License #3356839 |
| Policyholder Representation | We represent the insured rather than the insurance carrier |
| Residential & Commercial Experience | We work with homeowners and business/property owners |
| Claim Documentation | We focus on creating a supported scope rather than relying on verbal disagreement |
| Texas-Focused Experience | Our work centers on Texas property losses and Texas claim conditions |
| Free Claim Review | Property owners can have the situation reviewed before deciding whether to hire us |
| No Upfront Fees | You can discuss the claim with our team without paying an upfront fee |
The Texas Department of Insurance requires public insurance adjusters operating in the state to be licensed. That is one reason property owners should verify licensing before allowing anyone to represent them on an insurance claim.
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839.
Areas We Serve Near Graham
Our Graham public adjusting services extend beyond the city limits into surrounding Young County communities and nearby North Texas properties.
We can assist qualifying property owners in and around Olney, Newcastle, Loving, Eliasville, South Bend, Fort Belknap, Lake Graham, and the broader Young County area. Graham is the Young County seat, with Olney and Newcastle also located within the county and smaller communities spread through the surrounding rural area.
Properties toward Possum Kingdom Lake may also fall within the broader service area depending on location. Possum Kingdom extends through the Brazos River region southeast of Graham and into neighboring counties.
If your property is outside Graham, contact TX Public Adjusting and we can confirm service availability for your location.
Frequently Asked Questions About Public Adjusters in Graham
Do I need a public adjuster after a hailstorm in Graham?
Not every hail claim requires a public adjuster. If the carrier’s inspection is thorough, the scope appears complete, and the payment reasonably reflects covered damage, professional representation may not be necessary.
A public adjuster becomes more valuable when the loss is substantial, the roof or exterior scope seems incomplete, the claim is denied, or the carrier’s estimate is significantly below the documented repair scope. Given Graham’s exposure to hail-producing thunderstorms, having a questionable roof claim reviewed can be worthwhile before repairs begin.
Can you help if my Graham roof claim has already been paid?
Yes, depending on the policy, claim status, timing, and circumstances. Receiving an initial insurance payment does not automatically mean every covered item has been addressed.
We can review the carrier’s estimate against the observed damage and available documentation. If material items appear to have been omitted, we can explain possible next steps after reviewing the actual claim. Timing can affect the available options, so property owners with an older or previously settled claim may also want to review when it is too late to hire a public adjuster.
What if the insurance company says my roof only needs repairs?
Repair-versus-replacement disagreements are common in roof claims. The answer depends on the observed damage, roofing system, repairability, applicable policy provisions, and other claim-specific factors.
Our role is to inspect and document the condition rather than assume in advance that every roof needs replacement. When we disagree with the carrier’s scope, we support that position with evidence.
Does a Graham public adjuster work for my insurance company?
No. A public insurance adjuster represents the insured policyholder. The insurance company’s adjuster represents or works on behalf of the carrier. TDI recognizes public adjusters as professionals hired to help insureds negotiate their property claims.
That distinction is fundamental. TX Public Adjusting works for the property owner who hires us, not the insurer paying the claim.
How much can a public adjuster charge in Texas?
The Texas Department of Insurance states that public adjusters may charge up to 10% of the total amount the insurance company will pay on the claim. The exact fee and terms should be clearly stated in the written agreement before representation begins.
TX Public Adjusting offers Graham property owners a free initial claim review and no upfront fees so you can understand your options before deciding whether representation makes sense.
Can a public adjuster help with water damage in Graham?
Yes. Water damage claims can involve plumbing failures, storm-created openings, burst pipes, appliance leaks, and other causes. Coverage depends on what caused the loss and the terms of the policy.
We focus on documenting the resulting property damage, reviewing the carrier’s scope, and identifying affected areas or repairs that may have been missed.
Do you handle commercial insurance claims in Graham?
Yes. TX Public Adjusting handles residential and commercial property claims.
Commercial losses can be particularly detailed because they may involve larger roofing systems, tenant improvements, equipment, inventory, multiple repair trades, and interruption to normal operations. A claim affecting a downtown Graham business can therefore require a substantially different adjustment strategy from a typical residential claim.
Can you inspect properties around Lake Graham or Possum Kingdom Lake?
Yes, subject to the property’s location and the specifics of the claim. Lake-area homes, vacation properties, commercial facilities, and other structures can experience hail, wind, water, fire, and roof losses just like properties inside Graham.
Contact us with the property address and we can confirm service availability.
How long does a Graham property insurance claim take?
There is no responsible one-size-fits-all timeline. Claim duration depends on the extent of damage, insurer response, documentation required, whether estimates are disputed, whether experts are involved, and other claim-specific issues.
Our focus is to keep the claim documented and moving while responding to requests and addressing disputed scope items. We do not promise a settlement date we cannot control.
What if my Graham insurance claim was denied?
A denial deserves careful review. The first step is understanding exactly why the carrier denied the claim and what policy language, inspection findings, or documentation it relied upon.
TX Public Adjusting can review the claim to determine whether public adjusting services may help. If the dispute instead requires legal advice or involves issues outside a public adjuster’s authority, the property owner may need to speak with a qualified attorney.
Get a Free Graham Insurance Claim Review
If your property in Graham has been damaged by hail, wind, water, fire, a roof loss, or another covered event, you do not have to evaluate the insurance company’s estimate alone.
TX Public Adjusting can review the claim, inspect the damage when appropriate, identify potential scope issues, document the loss, and represent you in communications and negotiations with the insurance company.
TX Public Adjusting
Rise Public Adjusting LLC
Texas License #3356839
Free Claim Review | No Upfront Fees | Residential & Commercial Claims
Contact TX Public Adjusting today for a free claim review and find out whether your Graham property insurance claim deserves a closer look.