

Property damage in Bonney can become an insurance problem long before the repairs actually begin. A Gulf Coast storm can lift shingles or push rain through a vulnerable roof. A severe thunderstorm can damage siding, gutters, fencing, and exterior equipment. A plumbing failure can spread water through flooring and walls before anyone realizes how far it traveled.
When the insurance estimate does not reflect the full loss, a Public Adjuster in Bonney, TX can give the property owner independent representation.
TX Public Adjusting represents homeowners, business owners, landlords, and other policyholders—not insurance companies. Our team reviews the policy, inspects the damage, develops claim documentation, identifies missing or undervalued items, and communicates with the carrier about the amount required to properly address covered damage.
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839. We have experience reviewing thousands of Texas property claims involving residential and commercial losses.
Free Claim Review | Licensed Texas Public Adjuster | Residential & Commercial Claims | No Upfront Fees
If your Bonney insurance claim has been underpaid, delayed, denied, or simply does not make sense, contact TX Public Adjusting for a free claim review.
Property Claims in Bonney Are Different From Claims in Other Parts of Texas
Bonney is a small Brazoria County community with a distinctly Gulf Coast exposure. The Village is located approximately 10 miles north of Angleton and about 37 miles south of Houston, near the State Highway 288 corridor. Village Hall and the municipal complex sit along FM 521.
That location matters when evaluating property claims. Brazoria County sits on the Gulf Coastal Plain, where tropical systems, heavy rainfall, flooding, thunderstorms, and high winds have long been recurring hazards. County hazard planning also specifically identifies localized stormwater flooding, hail, lightning, tornadoes and straight-line winds, hurricanes, and tropical storms as hazards residents should consider.
| Bonney Property Claim Factor | Local Relevance |
| County | Brazoria County |
| Primary corridors | FM 521 and nearby SH 288 |
| Local residential references | Pradera Oaks, Cannon’s Pear Orchard and surrounding 77583-area communities |
| Major weather concerns | Hurricanes, tropical storms, severe thunderstorms, wind, hail and heavy rainfall |
| Common losses | Roof, water, storm, fire, hail and commercial property damage |
| Nearby communities | Angleton, Rosharon, Iowa Colony, Manvel and Alvin |
Local development records specifically reference Pradera Oaks and Cannon’s Pear Orchard in Bonney. The broader Bonney/77583 property market also includes areas commonly identified as Suncreek Estates and The Oaks at Suncreek Estates, so claim conditions can range from established rural properties to newer residential construction.
Why Property Owners Hire a Public Adjuster in Bonney
Your insurance company has an adjuster handling the claim for the carrier. A public adjuster gives the policyholder someone working from the other side of the table. Understanding the difference between a public adjuster vs. insurance adjuster for hail claims can be particularly helpful after a major Bonney storm.
That distinction becomes especially important when the loss involves more than one damaged building component. A wind event that starts with missing shingles may also involve ridge material, flashing, vents, gutters, fencing, attic moisture, insulation, drywall, paint, flooring, or personal property.
An abbreviated carrier estimate can make a complicated loss look simple.
A public insurance adjuster in Bonney can assist by:
- Reviewing the insurance policy and applicable endorsements.
- Inspecting visible and potentially related property damage.
- Comparing the carrier’s estimate against the actual repair scope.
- Organizing photographs, estimates, inventories, invoices, and other supporting documentation.
- Identifying omitted or undervalued claim items.
- Presenting documented disagreements to the insurance carrier.
- Managing claim communication and negotiation for the policyholder.
The goal is not to manufacture a larger claim. It is to document the covered loss accurately and make sure the claim reflects damage that can actually be supported.
Bonney Storm Risks and Property Damage Claims
Bonney’s position in Brazoria County creates a combination of Gulf Coast and severe-thunderstorm risks.
Hurricanes and Tropical Storms
Tropical systems can affect Bonney even when the center of a storm does not pass directly over the Village. Strong winds, repeated gusts, prolonged rainfall, flying debris, and wind-driven rain can produce damage across roofing systems and building exteriors.
The resulting insurance claim may involve shingles, roof decking, flashing, gutters, exterior finishes, windows, doors, fencing, interior ceilings, insulation, electrical components, and business equipment.
Brazoria County’s history includes repeated hurricane and flood events, which makes tropical-weather preparation especially relevant for properties in this part of Texas.
Severe Thunderstorms and Straight-Line Wind
Bonney also experiences the more localized severe storms common around the Houston-Galveston region.
A particularly local example occurred on August 28, 2026, when the National Weather Service included Bonney in a severe thunderstorm warning for central Brazoria County. The warning cited radar-indicated wind gusts up to 60 mph and specifically advised that roofs, siding, and trees could be damaged.
That is exactly the kind of storm where a property may look mostly intact from the ground while shingles, flashing, soft metals, siding, fencing, or exterior equipment have sustained damage.
Hail Damage
Hail does not need to break through a roof to produce a claim issue. Asphalt shingles may sustain bruising or granule loss, while metal surfaces can show impact marks. Gutters, vents, window screens, HVAC fins, and other exterior components can provide additional evidence of a hail event.
A complete Bonney hail claim should consider the property as a system rather than focusing only on one obvious roof slope.
Heavy Rain and Water Intrusion
Water claims require particular care in Brazoria County because the source of the water matters.
Rain entering through storm-created roof or exterior damage may be treated differently from rising surface water or flooding. Standard property insurance policies often contain important distinctions and exclusions involving flood damage.
We review the policy and documented cause of loss rather than assuming all water damage falls into the same category.
Common Insurance Claims in Bonney
Hail Damage Claims
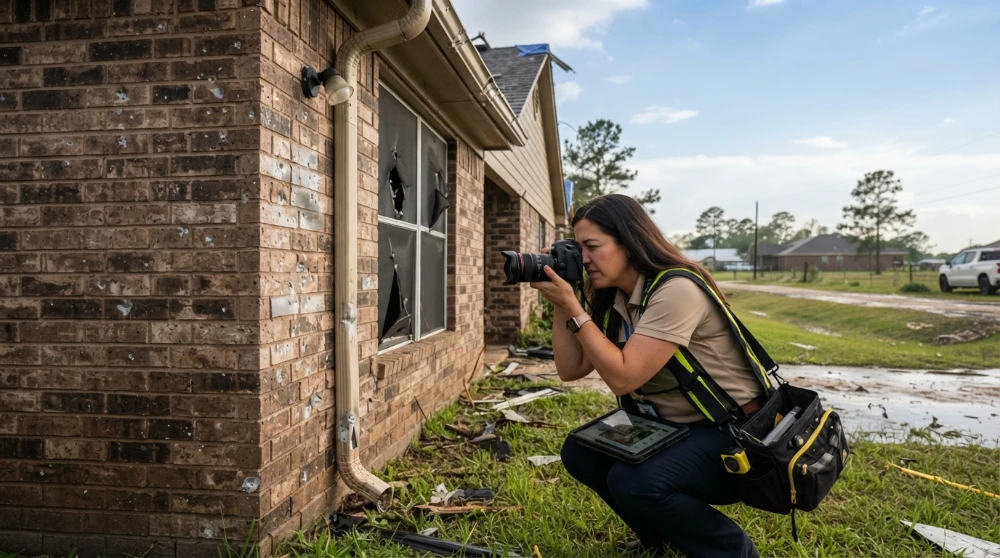
A hail claim may involve much more than visible roof dents. Property owners dealing with a hail damage roof insurance claim should consider the entire roofing system, not just the most obvious impact marks. We inspect roofing materials and associated exterior components and compare the documented storm damage with the carrier’s estimate.
Important items can include shingles, metal roofing, flashing, vents, gutters, downspouts, siding, screens, exterior paint, HVAC equipment, and related interior water damage. Property owners can also review our guide explaining how to document hail damage for an insurance claim before damaged materials are repaired or replaced.
Water Damage Claims
Burst pipes, plumbing failures, appliance leaks, roof leaks, and storm-created openings can cause water to migrate well beyond the place where the problem started. A water damage public adjuster can review whether the insurer’s scope accounts for the full extent of covered damage.
A water damage claim may require documentation of drywall, insulation, flooring, cabinets, trim, paint, contents, demolition, drying, mitigation, and reconstruction. When the carrier’s scope stops at the visible stain, significant repair costs can be missed.
Fire Damage Claims
Fire claims often involve separate layers of loss: direct burning, heat damage, smoke and soot contamination, firefighting water, debris removal, damaged contents, and temporary living or business interruption issues when applicable under the policy. A fire insurance adjuster working for the policyholder can help organize these different components into a documented claim presentation.
For Bonney property owners dealing with a significant fire, detailed documentation is especially important before damaged materials are discarded or reconstruction begins.
Storm and Wind Damage Claims
Storm claims may involve roofing, exterior cladding, fences, windows, doors, detached structures, trees, interior finishes, and water intrusion.
Wind can also create disagreements over causation. A carrier may attribute a roof condition to age or deterioration while the property owner believes the storm caused or materially worsened the damage. That dispute requires evidence—not assumptions.
Roof Damage Claims
Roof claims are among the losses most likely to develop scope disagreements. If the insurer’s inspection or estimate does not reflect the damage you are seeing, working with a public adjuster for a roof claim can provide an independent review of the documented loss.
A carrier estimate might approve a limited repair while contractors identify a broader restoration need. Other disputes involve matching, roof accessories, flashing, code-related work, underlayment, depreciation, or whether storm damage exists at all.
A public adjuster can compare the insurer’s scope against the documented condition of the complete roofing system.
Commercial Property Claims
Bonney’s location near FM 521 and the SH 288 corridor also places commercial, agricultural, investment, and development-related properties within the surrounding service area.
Working with a commercial public adjuster can be especially valuable when a loss involves multiple building systems or significant documentation. Commercial claims can involve roof systems, building interiors, machinery, inventory, tenant improvements, exterior structures, mitigation costs, and business-related coverage. Larger losses often require considerably more documentation than a standard residential claim.
Have a Bonney claim that does not match the actual repair cost? Get a Free Claim Review from TX Public Adjusting before assuming the carrier’s first estimate is the final answer.
Why Bonney Insurance Claims Become Underpaid
A low insurance payment is not always caused by one dramatic coverage dispute. Frequently, the difference comes from smaller omissions spread throughout the estimate.
Missed Damage
A short inspection may identify the obvious loss while overlooking collateral or secondary damage.
For example, a roof estimate may address shingles but fail to account for vents, flashing, gutters, damaged interior finishes, or other storm-related components.
Scope Omissions
The carrier can acknowledge that damage is covered while still disagreeing about what work is actually required.
Missing demolition, preparation, disposal, material quantities, labor steps, or related building components can materially affect the final repair cost.
Depreciation Issues
Property estimates may contain depreciation depending on the policy and damaged item. Property owners can struggle to understand what has been withheld, what may be recoverable, and what documentation is required.
We review how depreciation is being applied as part of the overall claim analysis.
Low or Incomplete Estimates
An insurance estimate is an opinion about the scope and value of the loss. It is not automatically the only valid estimate.
When legitimate repair items are missing or pricing does not reflect the documented scope, those differences should be addressed with supporting evidence.
Documentation Problems
Photos taken too late, disposed materials, incomplete inventories, missing mitigation records, and poorly organized contractor information can weaken an otherwise valid claim.
Good claim preparation creates a clear connection between the event, the damage, the repair requirement, and the amount being requested.
Our Public Adjusting Process
1. Claim Review
We begin by learning what happened, reviewing the status of the claim, and examining the carrier’s estimate, correspondence, and relevant policy information.
The claim may be brand new, already under review, underpaid, delayed, or denied.
2. Property Inspection
We inspect and document the property with the claim in mind.
For storm losses, that can include roofing, exterior components, interior areas, accessory structures, and signs of related water intrusion.
3. Documentation and Scope Development
We organize the evidence and determine what needs to be included in the claim presentation.
Depending on the loss, that may include photographs, measurements, repair estimates, inventories, mitigation records, contractor information, invoices, and other supporting documentation.
4. Claim Communication and Negotiation
TX Public Adjusting communicates with the insurance carrier about documented differences in scope, pricing, damage, and other claim issues within the services permitted under our public adjusting engagement.
You have a representative whose job is to advocate for the policyholder rather than the insurer.
5. Settlement and Claim Resolution
We continue working through documented claim issues as the carrier reviews the information and the claim moves toward resolution.
No public adjuster can guarantee a particular payment. What we can provide is experienced representation, detailed documentation, and a claim position based on the evidence and policy.
Why Choose TX Public Adjusting for a Bonney Property Claim?
TX Public Adjusting focuses on Texas property insurance claims. That means our work is centered on the losses Texas property owners repeatedly encounter—hail, wind, hurricanes, roof damage, water losses, fire, and large commercial claims.
Property owners choose us because we offer:
- Licensed Texas representation: Rise Public Adjusting LLC, Texas License #3356839.
- Independent policyholder advocacy: We work for the insured, not the insurance company.
- Residential and commercial experience: From individual homes to complicated business-property losses.
- Thousands of claims reviewed: Experience helps us identify where estimates and documentation commonly break down.
- Storm and catastrophe experience: Including hail, hurricanes, wind, water, roof, and fire losses.
- Free Claim Review: An opportunity to understand the claim before deciding what to do next.
For a small community such as Bonney, local relevance also matters. A claim involving a residence around Pradera Oaks or property near FM 521 should not be treated like a generic loss copied from another part of Texas. Municipal records show ongoing residential development around Pradera Oaks, including multiple sections and newly accepted roads, reinforcing how Bonney includes a mix of established and developing properties.
Areas We Serve Near Bonney
TX Public Adjusting assists property owners throughout Bonney and surrounding Brazoria County communities, including Angleton, Rosharon, Iowa Colony, Manvel, Alvin, Bailey’s Prairie, and other nearby areas along the SH 288 corridor.
The Village itself sits about 10 miles north of Angleton, making Bonney part of a connected Brazoria County property market rather than an isolated service point.
Frequently Asked Questions About Public Adjusters in Bonney
What does a public adjuster in Bonney do?
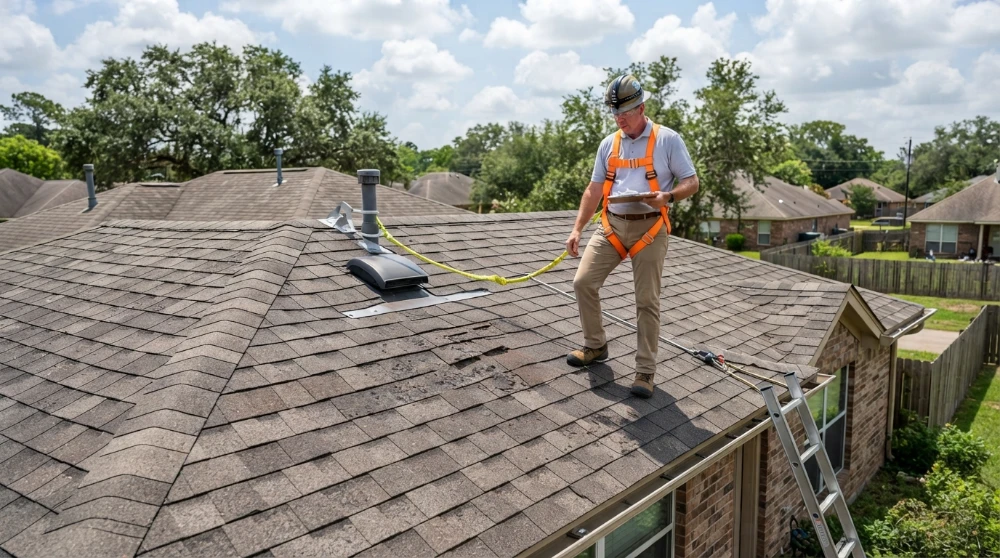
A public adjuster represents the policyholder during a property insurance claim. We review the policy and carrier estimate, inspect and document damage, prepare supporting claim information, and communicate with the insurance company about documented differences.
Unlike the carrier’s adjuster, the public adjuster’s client is the property owner.
What types of claims are common in Bonney?
Bonney property owners can face wind, hurricane, tropical-storm, hail, water, roof, fire, and severe-thunderstorm losses. Brazoria County’s location along the Gulf Coastal Plain also makes heavy rainfall and localized flooding relevant considerations.
The correct claim approach depends on the actual cause of damage and the wording of the policy.
Can a public adjuster help after a hurricane or tropical storm in Bonney?
Yes. Hurricane and tropical-storm claims can become complicated because one event may involve wind damage, roof damage, water intrusion, contents, exterior structures, and additional repair costs.
We document the covered loss and help separate the different components of the claim rather than treating everything as one generic storm item.
What if the insurer says my Bonney roof damage is just wear and tear?
A disagreement over storm damage versus age or deterioration should be evaluated using the physical evidence, storm history, roof condition, and applicable policy language.
A public adjuster can inspect the property, review the carrier’s position, document relevant storm-related conditions, and present supported claim differences to the insurer.
Can you help with water damage if flooding occurred?
Possibly, but the source of the water is critical. Damage from a burst pipe, roof opening, or other covered event may be treated differently from rising surface water.
We review the claim and policy rather than promising that every form of water damage is covered. Separate flood insurance may apply to certain flood losses.
Can I hire a public adjuster after I already filed my claim?
Yes. Property owners often seek public-adjuster assistance after the claim has already started. If you are unsure when it is too late to hire a public adjuster, the answer can depend on the status of the claim, applicable deadlines, and what actions have already been taken.
A useful time to request a review is when you receive the carrier’s estimate, discover additional damage, encounter delays, or believe the payment does not reflect the actual repair scope. Waiting until deadlines or final claim-resolution documents have passed can reduce available options.
Can TX Public Adjusting review an underpaid Bonney claim?
Yes. Underpaid claims are a major reason property owners request a review.
We can compare the insurer’s estimate with the documented property damage and look for missing scope, incorrect quantities, pricing differences, overlooked components, depreciation questions, and other claim issues that may justify further discussion with the carrier.
Do you handle commercial property claims around Bonney?
Yes. TX Public Adjusting handles both residential and commercial property claims.
Commercial losses may involve roofing systems, interior buildouts, equipment, inventory, tenant spaces, mitigation expenses, and other property-related coverage. These claims often benefit from careful documentation because one omitted building component can create substantial repair-cost differences.
What parts of Bonney do you serve?
We assist property owners throughout the Village and surrounding area, including properties near FM 521, the SH 288 corridor, Pradera Oaks, and the broader 77583 area.
We also serve nearby Brazoria County communities such as Angleton, Rosharon, Iowa Colony, Manvel, Alvin, and Bailey’s Prairie.
How much does it cost to have TX Public Adjusting review my claim?
The initial claim review is free. There is no obligation to hire us simply because we review your situation.
If professional public-adjusting representation makes sense, the fee arrangement and services are explained in writing before an agreement is signed. You should always understand the contract and fee structure before hiring any public adjuster.
Get a Free Bonney Insurance Claim Review
If your Bonney home, commercial building, rental property, or other insured property has been damaged, you do not have to rely solely on the insurance company’s interpretation of the loss.
A low estimate can contain missing items. A roof denial can involve a genuine causation disagreement. A water loss may extend farther than the visible damage. A major storm claim can require substantially more documentation than the initial inspection captured.
TX Public Adjusting can review your claim and help you understand what the documentation actually shows.
Free Claim Review
No Upfront Fees
Residential & Commercial Property Claims
Rise Public Adjusting LLC — Texas License #3356839
Contact TX Public Adjusting to request a free claim review and find out whether your Bonney property insurance claim deserves a closer look.