

Property damage in Bayou Vista can turn into a complicated insurance claim quickly. This is not a typical inland Texas community. Bayou Vista sits in Galveston County near Jones Bay and Highland Bayou, with homes built along dredged canals that connect toward Galveston Bay and the Gulf. Many properties are waterfront, elevated, and exposed to a combination of hurricane winds, wind-driven rain, hail, tidal water, and tropical storm conditions.
When the insurance estimate does not reflect the full damage, a public adjuster in Bayou Vista can represent the property owner—not the insurance company. TX Public Adjusting helps homeowners, landlords, investors, and commercial property owners document losses, review carrier estimates, identify missed damage, and negotiate property insurance claims.
TX Public Adjusting is operated by Rise Public Adjusting LLC, Texas License #3356839. Our team has experience reviewing thousands of residential and commercial property claims across Texas.
Free Claim Review • Licensed Texas Public Adjuster • Residential & Commercial Claims • No Upfront Fees
If your Bayou Vista insurance claim was underpaid, delayed, denied, or simply does not seem to match the damage you can see, contact TX Public Adjusting for a free claim review before assuming the carrier’s first estimate is the final word.
Why Property Owners Hire a Public Adjuster in Bayou Vista
Insurance claims are heavily dependent on documentation, repair scope, causation, policy language, and the evidence presented to the insurance company. Those issues become especially significant in a waterfront community such as Bayou Vista.
A hurricane, for example, can cause several different types of damage during the same event. High wind can lift roofing materials. Wind-driven rain can enter through storm-created openings. Water can damage drywall, flooring, insulation, cabinets, electrical components, and personal property. At the same time, rising tidal water may create a separate coverage question.
That distinction matters.
Standard homeowners insurance generally does not cover flooding caused by rising water, which is why Galveston County specifically encourages coastal residents to evaluate separate flood insurance. Wind, roof openings, wind-driven rain, and other storm damage may be evaluated differently depending on the policy involved.
A Bayou Vista public adjuster can help organize the claim so that the cause and extent of each damaged component are clearly documented rather than treating the entire loss as one undifferentiated event.
Property owners commonly contact us when:
- The insurance company’s estimate appears too low.
- Roof or exterior damage was omitted.
- Wind damage is being attributed to age or deterioration.
- Interior water damage was only partially included.
- The carrier disputes whether wind or water caused the loss.
- Depreciation significantly reduced the initial payment.
- A supplement has been rejected or ignored.
- The property suffered multiple types of damage during one storm.
- The claim has already been paid but repairs cost substantially more.
- A commercial or investment property claim has become difficult to manage.
Our job is to build a detailed, supportable claim based on the property, the damage, and the applicable insurance policy.
Bayou Vista Property Damage Has a Distinct Coastal Risk Profile
Bayou Vista’s geography changes the way property losses should be evaluated. The community developed around a network of residential canals, and Galveston County MUD No. 12 identifies the City of Bayou Vista, Original Bayou Vista, and neighboring Omega Bay as canal communities in its service area.
Galveston Central Appraisal District records also identify Bayou Vista, Bayou Vista Section 2, Bayou Vista Section 3, and New Bayou Vista-related areas. Local property records show New Bayou Vista additions extending through multiple numbered sections.
That means a property inspection here may involve more than the main dwelling. Depending on the policy and the specific property, a loss may involve elevated living areas, lower-level enclosures, stairs, decking, siding, roofing, mechanical equipment, docks, fences, exterior structures, and other improvements.
Hurricanes and Tropical Storms
Hurricane risk is central to property ownership along this part of the Texas Gulf Coast.
Hurricane Ike made landfall near Galveston in September 2008 and produced extensive wind and storm-surge damage around Galveston Bay. The National Weather Service estimates storm surge on Galveston Island and the west side of Galveston Bay reached roughly 10 to 15 feet in areas affected by Ike.
More recently, Hurricane Nicholas passed through the region in 2021. The National Weather Service recorded a 59-mph observation approximately two miles east-southeast of Bayou Vista during that storm.
Hurricane Beryl in 2024 again produced significant impacts across Galveston County. The National Weather Service reported widespread high winds in the county, including coastal gusts above 80 mph, along with downed trees, power lines, and building damage. A rainfall observation northwest of Bayou Vista measured 2.34 inches.
For a Bayou Vista insurance claim, these events illustrate why damage should not be evaluated only by looking for missing shingles. Hurricane losses can affect the full exterior envelope of a building.
Wind and Roof Damage
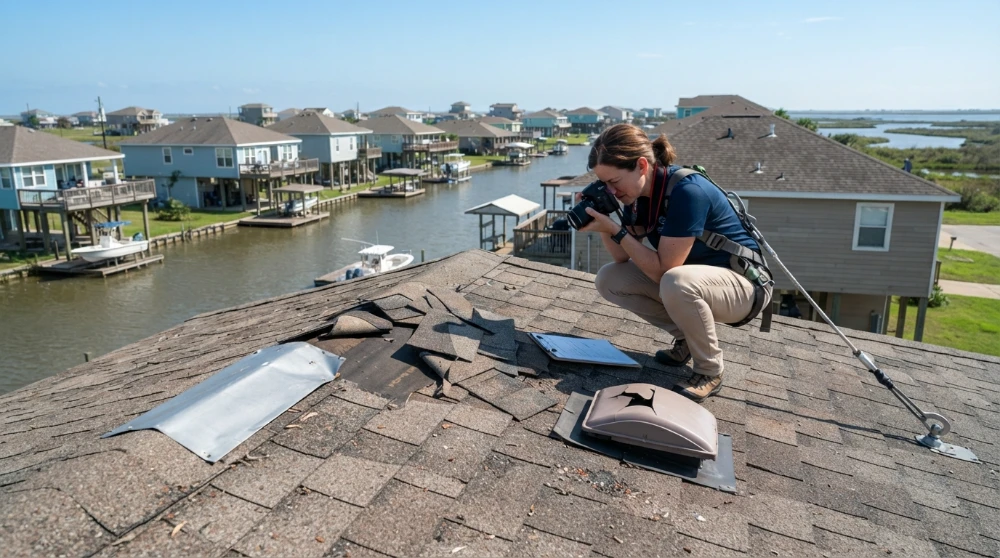
Strong Gulf Coast wind can lift shingles, break seals, displace flashing, damage ridge components, loosen siding, affect soffits and fascia, and allow rain into the structure.
Some damage is obvious. Some is not.
A roof can remain in place while still sustaining functional damage that contributes to later leaks. That is why a proper Bayou Vista roof claim should include collateral evidence and related building components rather than focusing exclusively on one visible area.
Galveston County is also within Texas’s designated catastrophe area for windstorm insurance. Depending on the property owner’s insurance arrangement, wind and hail coverage may involve a separate policy such as coverage through the Texas Windstorm Insurance Association.
When multiple policies may be involved, documentation and causation become even more important.
Storm Surge, Tidal Water, and Flood-Related Damage
Bayou Vista’s waterfront setting means water-related losses require careful attention.
FEMA maintains effective flood hazard mapping for Bayou Vista, with the community’s currently listed effective FIRM dating to August 15, 2019.
For claim purposes, the critical question is often how the water entered the property.
Rain entering through a storm-created roof opening can present a different coverage issue from water rising from a canal, bay, street, or surrounding ground. Property owners should avoid making assumptions about coverage until the relevant policies, endorsements, exclusions, and physical evidence have been reviewed.
Severe Thunderstorms and Hail
Hurricanes receive most of the attention along the coast, but Bayou Vista can also experience hail and severe thunderstorms.
Hail can affect:
- Composition shingles
- Metal roofing
- Roof vents and flashing
- Gutters
- Window screens
- Siding
- HVAC equipment
- Exterior light fixtures and other soft metals
Small impact marks can be easy to overlook during a rushed inspection. When a hail claim is disputed, evidence on vents, flashing, gutters, and other exterior surfaces can help establish the pattern and direction of impact.
Freeze and Plumbing Losses
Coastal Texas is associated with heat and hurricanes, but freeze events can also create expensive property claims.
Frozen or damaged pipes can release water into walls, ceilings, floors, cabinets, insulation, and lower-level spaces. In an elevated Bayou Vista home, plumbing routes and exposed components may make the resulting damage pattern different from a conventional slab-on-grade house.
The initial plumbing repair is often only one part of the loss. The full claim may also require documentation of demolition, drying, damaged finishes, insulation, flooring, cabinetry, paint, and reconstruction.
Common Insurance Claims in Bayou Vista
Hail Damage Claims
A hail claim should document more than a few roof impacts.
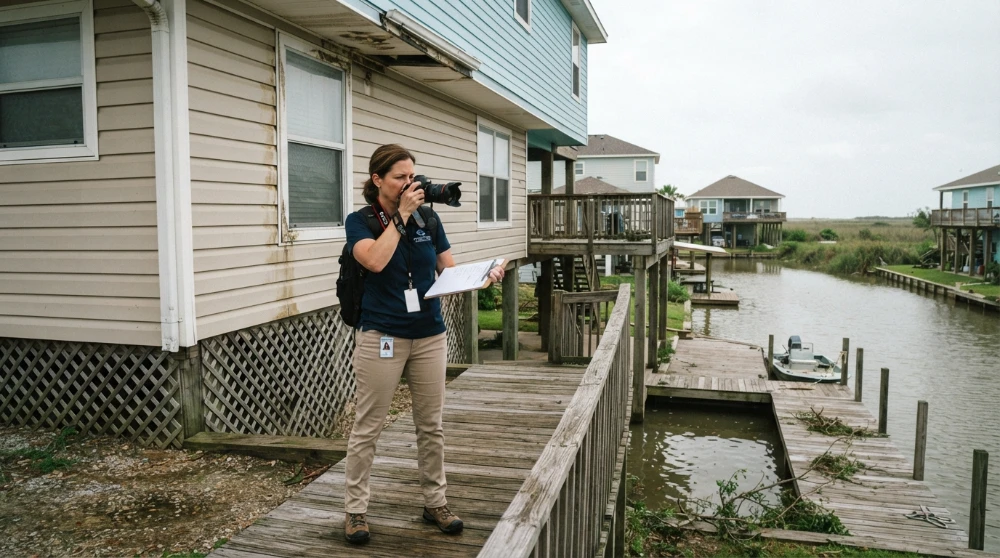
TX Public Adjusting evaluates the entire affected property for storm-related evidence. That can include shingles, metal roofing, vents, flashing, gutters, siding, windows, exterior fixtures, and interior water damage connected to the storm.
Property owners can also review our Texas Hail Damage Insurance Claim Guide and our more detailed Hail Damage Roof Insurance Claim Guide. Both are included in the site’s existing content structure.
Water Damage Claims
Bayou Vista water claims may involve plumbing failures, roof leaks, wind-driven rain, appliance failures, or storm-related openings.
We document both visible and related damage. That may include drywall, ceilings, insulation, flooring, trim, cabinets, electrical components, contents, and necessary demolition.
For more detail, see our Water Damage Public Adjuster Guide.
Fire Damage Claims
Fire losses can involve far more than what burned.
A proper fire claim may include structural damage, smoke contamination, soot, electrical damage, contents, demolition, debris removal, cleaning, temporary housing expenses, and reconstruction.
TX Public Adjusting handles residential and commercial fire-loss documentation. Read more in our Fire Insurance Adjuster Guide.
Storm and Hurricane Damage Claims
Storm damage is particularly relevant in Bayou Vista because wind, rain, tidal conditions, and flying debris may affect the same property during one event.
We separate the damage into components, document causation where evidence permits, compare the property condition with the insurance estimate, and identify items that may require additional investigation.
Our existing resources include the Hurricane Property Damage Guide and Hurricane Beryl Claims Process Guide.
Roof Damage Claims
Roof claims are among the most common reasons property owners seek insurance claim assistance in Bayou Vista.
The carrier’s estimate may include only a repair when the actual scope involves additional roofing materials, flashing, ventilation, underlayment, accessories, labor, or connected interior damage.
Our Public Adjuster for Roof Claims Guide explains how roof claims can become disputed when damage is missed or attributed to wear.
Commercial Property Claims
Bayou Vista itself is heavily residential, but we also represent commercial property owners and businesses throughout Galveston County.
Commercial claims may involve apartment properties, retail buildings, restaurants, offices, warehouses, marinas, self-storage facilities, churches, and other insured properties.
Commercial losses require careful attention to building damage, business personal property, mitigation, repair pricing, and applicable business-income provisions. Learn more about Commercial Property Claims.
Why Bayou Vista Insurance Claims Become Underpaid
An insurance company can acknowledge a covered loss and still issue an estimate that does not reflect everything required to repair the property.
Several recurring problems can reduce a Bayou Vista claim.
Missed Damage
A short inspection may capture the obvious roof or siding damage but miss flashing, soffits, fascia, interior moisture, insulation, decking, electrical components, exterior structures, or related finishes.
On canal-front properties, there may also be multiple exterior components at different elevations that need to be inspected separately.
Scope Omissions
A claim estimate is not only about price. It is also about scope.
If necessary work is missing from the estimate, even accurate unit pricing will still produce an inadequate repair budget.
Wind Versus Water Disputes
This is especially significant after a tropical system.
One insurer may be evaluating wind damage while another policy addresses flood-related damage. Establishing where the building first failed, how rain entered, what materials were damaged, and whether tidal or surface water contributed can affect the claim.
Depreciation
Replacement-cost policies commonly involve depreciation in the initial calculation. Property owners may also encounter disputes about the condition or age of damaged materials and what depreciation is recoverable under their policy.
We review those calculations against the policy and estimate.
Low Repair Estimates
The carrier’s estimate may omit labor operations, quantities, material requirements, code-related work, demolition, access, or other costs necessary to complete repairs.
Our job is not to inflate a claim. It is to document what is reasonably required to repair covered damage and support that scope with evidence.
Documentation Problems
Insurance companies make decisions from the claim file.
If photos are incomplete, damaged materials are discarded too early, mitigation records are missing, or repair estimates lack detail, the carrier may not have enough information to evaluate the full loss.
Already received an estimate? Send it to TX Public Adjusting for a Free Claim Review. We can compare the carrier’s scope with the documented damage and explain whether important items deserve a closer look.
Our Public Adjusting Process
1. Claim Review
We begin by reviewing the existing claim, insurance documents, estimates, correspondence, payments, photographs, and other available information.
If the claim is already underway, we identify the current status and what has already been documented.
2. Property Inspection
We inspect the damaged property with the insurance claim in mind.
For Bayou Vista properties, that may mean evaluating multiple levels of an elevated structure, roof and exterior components, interior water paths, canal-facing elevations, and other insured improvements.
3. Documentation and Scope
We organize photographs, measurements, estimates, inventories, supporting records, and other documentation needed to present the loss clearly.
Our scope identifies covered damage we believe should be evaluated and the work reasonably necessary to restore it.
4. Insurance Company Communication and Negotiation
Once retained, TX Public Adjusting communicates with the insurer regarding the claim within the scope of our representation.
We respond to estimate differences, inspection issues, missed items, and requests for additional documentation.
5. Claim Resolution
The goal is a properly documented settlement based on the applicable policy and covered damage.
No public adjuster can guarantee a specific outcome. What we can do is make sure the claim is presented professionally and that overlooked damage or scope issues are not ignored simply because the property owner did not know how to document them.
Why Choose TX Public Adjusting in Bayou Vista?
Bayou Vista property claims require an adjuster who understands Texas insurance claims and the special issues that come with coastal property.
TX Public Adjusting offers:
- Licensed Texas representation: Rise Public Adjusting LLC, License #3356839.
- Independent policyholder representation: We represent homeowners and property owners, not the insurance company.
- Texas-focused experience: Our work is centered on property claims throughout Texas.
- Residential and commercial experience: Our team has reviewed thousands of claim files involving homes, businesses, roofs, water losses, fire losses, hail, hurricanes, and major storms.
- Detailed claim documentation: We focus on the physical damage, repair scope, estimates, photographs, policy provisions, and evidence supporting the claim.
- Free Claim Review: Property owners can find out whether an estimate or claim deserves further review before deciding what to do next.
A public adjuster is different from an insurance company adjuster. The distinction is who the adjuster represents. You can read our Public Adjuster vs. Independent Adjuster Guide for a deeper explanation.
Areas We Serve Near Bayou Vista
TX Public Adjusting serves property owners throughout Bayou Vista and surrounding Galveston County communities.
That includes Original Bayou Vista, the New Bayou Vista sections, and the broader canal community around neighboring Omega Bay. We also assist property owners in nearby Hitchcock, La Marque, Texas City, Tiki Island, and Galveston.
Bayou Vista lies just off the I-45/Highway 6 corridor, roughly eight miles west-northwest of Galveston and five miles south of Texas City. Jones Bay, Highland Bayou, the Galveston Causeway area, and the waterways leading toward Galveston Bay help define the local landscape.
For nearby service-area pages, see Public Adjuster Galveston and Public Adjuster Texas City. Both locations are included in the current TX Public Adjusting site structure.
Frequently Asked Questions About Public Adjusters in Bayou Vista
What does a public adjuster in Bayou Vista do?
A public adjuster represents the policyholder during a property insurance claim. TX Public Adjusting can inspect the damage, review the policy and carrier estimate, prepare supporting documentation, identify missed scope items, and communicate with the insurance company.
That role can be particularly valuable in Bayou Vista when a storm produces several types of damage at once—such as roofing damage, wind-driven rain, interior water damage, exterior damage, and questions about rising water.
When should I hire a public adjuster after a Bayou Vista hurricane?
You can involve a public adjuster early in the claim, but property owners also contact us after an insurance inspection, after receiving an estimate, or after discovering the payment will not cover the documented repair scope.
Earlier involvement can make evidence preservation easier. If your claim is already several weeks or months old, do not automatically assume you waited too long. Our guide on When It Is Too Late to Hire a Public Adjuster explains the issue in more detail.
Can TX Public Adjusting help with an underpaid Bayou Vista roof claim?
Yes. We can compare the insurance company’s roof estimate with the property damage and determine whether components appear to have been omitted or undervalued.
Typical review areas include roof coverings, ridge and hip components, flashing, vents, underlayment, gutters, exterior surfaces, and interior damage connected to a storm-created opening. Coverage remains subject to the specific policy.
What if the insurer says my damage was caused by flooding instead of wind?
Wind-versus-water causation can become a major issue on the Texas coast. Rising water is generally treated differently from rain entering through a storm-created opening, and separate wind or flood policies may apply.
We can document the physical evidence and review the insurance claim materials so the damage is divided and presented as accurately as possible. Final coverage depends on the language and conditions of the policies involved.
Can a public adjuster help with a TWIA claim in Bayou Vista?
Galveston County is within Texas’s designated catastrophe area, and eligible properties may obtain windstorm and hail coverage through TWIA.
If your property has separate wind coverage, the first step is identifying which policy applies to which portion of the loss. TX Public Adjusting can review the claim documents and explain how we may be able to assist based on the specific circumstances.
Can I hire a Bayou Vista public adjuster after the insurance company already paid me?
Possibly. Receiving an initial payment does not necessarily mean every claim issue is resolved.
Property owners often discover omissions after contractors begin preparing detailed repair estimates. Whether additional amounts can still be pursued depends on the policy, claim status, documentation, applicable deadlines, and any settlement documents already signed.
Do you evaluate docks, decks, bulkheads, and lower-level structures?
We evaluate damaged property that is relevant to the insurance claim, but coverage for docks, bulkheads, detached structures, lower enclosures, fences, decks, and other improvements varies significantly by policy.
That is especially relevant in Bayou Vista because waterfront properties often include improvements that an inland home does not. We identify the damaged components and then review how the policy addresses them rather than assuming everything receives the same coverage.
Do you handle commercial insurance claims near Bayou Vista?
Yes. TX Public Adjusting works on both residential and commercial property claims.
We serve commercial property owners throughout Galveston County, including businesses and investment properties affected by hurricanes, wind, hail, water, fire, roof damage, and other covered losses.
How much does it cost to have TX Public Adjusting review my Bayou Vista claim?
The initial Claim Review is free, with no upfront fee for the review. If you decide to retain TX Public Adjusting, the compensation structure and terms of representation are explained in the written agreement before work begins.
We recommend having the claim reviewed before accepting assumptions about what an underpaid or disputed loss may be worth.
What should I send for a free Bayou Vista insurance claim review?
Start with whatever you already have. That may include the insurance estimate, claim payment documents, denial or coverage letters, policy documents, photographs, contractor estimates, mitigation invoices, engineering reports, and correspondence with the carrier.
You do not need to organize everything perfectly before contacting us. We can tell you what additional documentation would be useful after reviewing the existing file.
Get a Free Bayou Vista Insurance Claim Review
A waterfront property claim can involve details that are easy to miss during a rushed inspection. Roof damage may connect to interior water damage. Exterior components may be omitted. Wind and water causation may be disputed. Separate coastal insurance policies may complicate the claim even further.
You do not have to rely solely on the insurance company’s estimate.
TX Public Adjusting represents policyholders—not insurance companies.
Rise Public Adjusting LLC
Texas License #3356839
Free Claim Review • No Upfront Fees • Residential & Commercial Claims
Contact TX Public Adjusting today and let us review your Bayou Vista property damage claim, insurance estimate, and supporting documentation.