Property damage in Panorama Village can turn into an insurance dispute faster than many homeowners expect. Hail can bruise shingles and damage gutters, straight-line winds can affect roofing and trees, heavy rain can expose leaks or drainage problems, and a burst pipe or fire can create damage across several parts of a home at once. When the insurance company’s estimate does not reflect the full loss, a public adjuster in Panorama Village, TX can represent your interests throughout the claim.
TX Public Adjusting helps Panorama Village homeowners and commercial property owners document damage, review insurance estimates, identify missing items, and negotiate covered property claims. We represent policyholders—not insurance companies.
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839, serving residential and commercial property owners throughout Texas.
Need help with a denied, delayed, or underpaid claim? Request a Free Claim Review from TX Public Adjusting. There are no upfront fees for our public adjusting services.
Panorama Village is an incorporated Montgomery County community just north of Conroe along the I-45 corridor. The community developed around Panorama Golf Club and sits near the headwaters of White Oak Creek, with Lake Conroe only a short distance to the west. Those local features matter when evaluating property losses because this part of Montgomery County is exposed to severe thunderstorms, high winds, intense rainfall, falling tree limbs, hail, and tropical-weather effects.
Why Property Owners Hire a Public Adjuster in Panorama Village
An insurance claim involves more than showing the carrier that something was damaged. The amount ultimately considered in the claim can depend on how completely the loss is inspected, photographed, measured, estimated, and connected to the covered event.
The insurance company assigns an adjuster to investigate the claim on its behalf. A public adjuster works on the other side of that relationship: for the policyholder. Understanding the difference between a public adjuster vs. independent adjuster can help property owners understand exactly who each professional represents.
For Panorama Village property owners, our work can include:
- Reviewing the insurance policy and claim documents
- Inspecting residential or commercial property damage
- Photographing and documenting affected building components
- Comparing the carrier’s estimate with observed damage
- Identifying omitted or underestimated repair items
- Preparing a detailed scope of loss
- Organizing supporting documentation
- Communicating with the insurance carrier
- Negotiating the claim based on documented covered damage
- Assisting with supplemental claims when additional damage is identified
This can be particularly valuable when a claim involves multiple building components. A storm that damages a roof may also affect ridge caps, vents, flashing, gutters, screens, fencing, siding, exterior paint, or interior finishes after water intrusion. A carrier estimate that focuses on only one component may not represent the complete repair scope.
Our team has experience reviewing thousands of property claims, including residential and commercial losses throughout Texas.
Property Damage Risks in Panorama Village and Montgomery County
Panorama Village has a different property-risk profile from a dense Houston neighborhood or a more exposed Gulf Coast community. The wooded surroundings, golf-course development, proximity to Lake Conroe, and location in northern Montgomery County create a combination of wind, rain, hail, tree, roof, and water-damage concerns.
Severe Thunderstorms and Wind Damage
Strong thunderstorms are a recurring concern in Montgomery County. National Weather Service alerts have specifically included Panorama Village during storms capable of producing strong wind gusts, frequent lightning, and downed tree limbs.
For properties around Panorama Golf Club, Thunderbird, Indian Creek, Hallmark of Panorama, Cherry Hills, Green Briar, and nearby residential sections, mature trees can add another layer of exposure. Limbs may strike roofing, fences, gutters, detached structures, vehicles, or exterior mechanical equipment during strong winds.
Wind claims can involve more than obviously missing shingles. We often look for:
- Lifted or creased shingles
- Ridge and hip damage
- Flashing displacement
- Damaged vents
- Gutter and downspout damage
- Fence damage
- Siding impact
- Broken exterior fixtures
- Tree-impact damage
- Wind-driven rain entering through storm-created openings
The important question is not simply whether the roof is still standing. It is whether the covered event caused damage that requires repair or replacement under the policy.
Hail Damage Claims in Panorama Village
Hailstorms can produce property damage that is easy to overlook from the ground. Property owners dealing with a hail damage insurance claim should document more than the most obvious roof impacts because gutters, vents, flashing, screens, siding, and HVAC components may also show evidence of the storm.
An asphalt-shingle roof may show bruising, fractured mats, displaced granules, or impact marks. Metal roof components, gutters, vents, flashing, window screens, garage doors, fencing, and HVAC fins can also provide evidence of hail activity. Taking clear photographs before temporary repairs begin can also strengthen the claim file. Our guide on how to document hail damage for an insurance claim explains what property owners should photograph and preserve after a storm.
One reason hail claims become disputed is that cosmetic-looking damage and functional damage are not always evaluated the same way under every policy. The construction material, policy language, age of the roof, repair feasibility, and overall damage pattern can all matter.
A Panorama Village public adjuster can review the carrier’s inspection and compare it with the documented condition of the property.
Heavy Rain and Water Damage
Heavy rainfall is another significant local concern. National Weather Service flood advisories have specifically identified Panorama Village among Montgomery County communities facing urban and small-stream flooding during periods of excessive rainfall.
Not every type of water damage is covered, and homeowners insurance is not the same thing as flood insurance. The cause of the water matters.
Potential claims may involve water entering after storm-created roof damage, plumbing failures, broken supply lines, appliance leaks, or other covered events. A proper claim review should distinguish the source of the water and document how it traveled through the building.
Water may affect:
- Attic insulation
- Roof decking
- Drywall
- Paint
- Flooring
- Baseboards
- Cabinets
- Electrical components
- Interior framing
- Personal property
Moisture can travel beyond the area where a stain first appears. That makes documentation and moisture assessment especially important.
Tropical Storm and Hurricane-Related Damage
Panorama Village is inland from the Texas Gulf Coast, but inland does not mean immune from tropical systems.
Storms moving into southeast Texas can bring prolonged rain, wind gusts, falling trees, power interruptions, and wind-driven water well north of Houston. By the time a tropical system reaches Montgomery County, the claim may look less like dramatic coastal destruction and more like scattered roofing damage, tree impact, water intrusion, fencing damage, or interior moisture.
Those less dramatic losses still need to be properly documented.
Freeze and Pipe Damage
North Montgomery County can also experience winter freezes capable of stressing plumbing systems. A frozen or ruptured pipe can release a large amount of water before the source is discovered, particularly when the failure occurs inside a wall, attic, ceiling cavity, or vacant portion of a property.
Pipe-loss claims can become complicated when there are questions about the damaged plumbing component versus the resulting water damage. We review the policy and documentation rather than assuming every part of the loss will be handled the same way.
Common Insurance Claims in Panorama Village
Hail Damage Claims
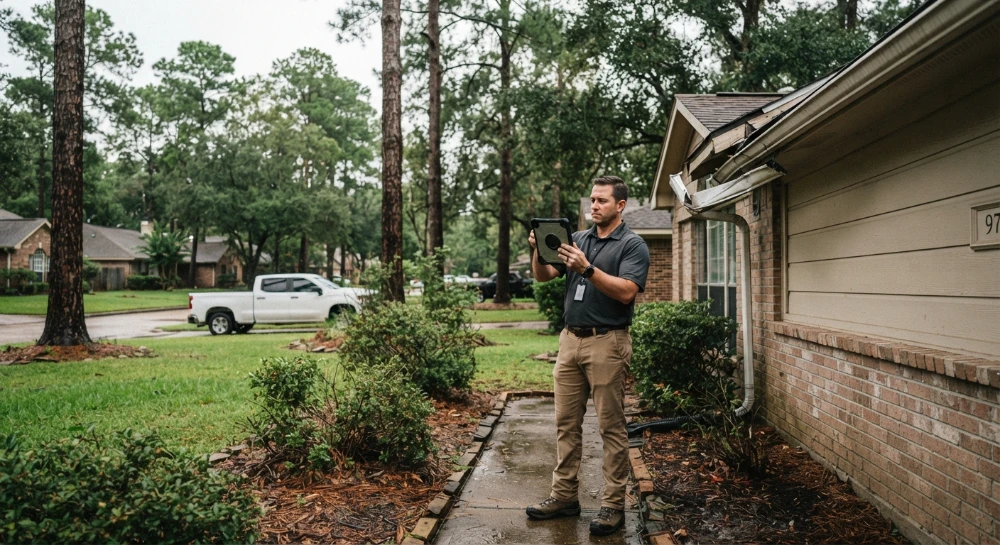
A hail claim should evaluate more than shingles alone. Roofing accessories, gutters, vents, soft metals, screens, siding, fencing, HVAC equipment, and other exterior surfaces may contain evidence of the same storm.
TX Public Adjusting documents the entire loss and compares the damage against the insurance company’s scope.
Water Damage Claims
Water damage may spread through ceilings, walls, insulation, flooring, cabinetry, and personal property before it becomes visible. If the carrier has already inspected the loss, our guide to dealing with an insurance adjuster after water damage explains several issues property owners should review before accepting the claim as complete.
When a covered water claim in Panorama Village has been underpaid or incompletely documented, we can review the cause, inspection records, mitigation documentation, photos, repair scope, and carrier estimate.
Fire and Smoke Damage Claims
Fire claims frequently involve several different categories of loss at the same time. Because these losses can involve structure, contents, smoke, debris removal, and additional living expenses, understanding the role of a fire insurance adjuster can be especially useful before accepting a carrier’s scope.
A house fire can cause direct flame damage, smoke contamination, soot deposits, heat damage, water damage from firefighting efforts, damaged contents, debris-removal costs, and temporary living expenses.
Smoke can also migrate into rooms that were never touched by flames. Building materials, HVAC systems, insulation, clothing, furniture, electronics, and porous surfaces may require separate evaluation.
TX Public Adjusting helps organize the different pieces of a fire claim so the loss is documented as a whole.
Storm Damage Claims
Panorama Village storms can bring combinations of wind, lightning, hail, rainfall, falling limbs, and flying debris.
When several causes of damage appear after one weather event, documentation becomes especially important. Photos, weather information, inspection findings, measurements, material identification, and repair estimates can help establish what occurred.
Roof Damage Claims
Roof claims are one of the most common reasons property owners seek insurance claim assistance in Panorama Village. When the insurer and property owner disagree about the necessary repair scope, a public adjuster for a roof claim can review the carrier’s estimate against the documented storm damage and repair requirements.
A carrier may conclude that only a small repair is necessary. The property owner or contractor may believe the damaged area is substantially larger.
That difference can involve:
- Missed shingles or roofing sections
- Repairability concerns
- Matching considerations
- Flashing
- Underlayment
- Ridge components
- Vents
- Steep or high-access charges
- Waste calculations
- Code-related items where applicable
- Interior damage associated with the same storm
We review the scope rather than relying only on the final dollar figure.
Commercial Property Claims
Commercial claims can involve much more than the physical repair of a building.
TX Public Adjusting assists businesses and commercial property owners with commercial property claims involving roofing systems, building interiors, inventory, equipment, tenant spaces, water intrusion, storm damage, fire damage, and other covered property losses.
Commercial policies can have different limits, deductibles, endorsements, valuation provisions, and documentation requirements. A careful policy and scope review is especially important when the loss affects operations or multiple building systems.
Why Panorama Village Insurance Claims Become Underpaid
A low insurance payment does not automatically mean the carrier acted improperly. Sometimes the difference comes from incomplete information, differing estimates, or damage that was not visible during the first inspection.
The important thing is determining why the numbers differ.
Missed Damage
Some damage is easy to overlook during a short inspection. Roofing accessories, flashing, siding, gutters, interior moisture, fencing, or secondary rooms may not make it onto the initial estimate.
Scope Omissions
An estimate may acknowledge a damaged component without including everything needed to perform the actual repair.
For example, replacing a roof involves more than a line item for shingles. Depending on the loss and construction, related components can affect the final scope.
Depreciation and Valuation Issues
Insurance estimates may apply depreciation based on age, condition, material, or policy provisions.
Property owners sometimes focus only on the first payment without understanding recoverable depreciation, actual cash value, replacement cost provisions, or documentation that may be required later.
We help clients understand how the claim estimate is structured and what documentation may still be necessary.
Low Repair Estimates
Pricing differences can arise from labor assumptions, material pricing, quantities, waste factors, access conditions, missing trades, or an incomplete scope.
Rather than simply saying an estimate is too low, we document the specific items that support a different scope.
Documentation Problems
Insurance carriers make decisions based heavily on what is contained in the claim file.
Weak photos, incomplete inventories, missing invoices, poor measurements, or unclear descriptions can make it harder to establish the full loss.
Good documentation gives the claim a stronger factual foundation.
Our Public Adjusting Process
1. Claim Review
We start by reviewing what happened and where the claim currently stands.
If available, we examine the policy, carrier estimate, payment information, denial letter, photographs, contractor estimates, mitigation records, correspondence, and other relevant documents.
2. Property Inspection
We inspect the reported damage and look beyond the most obvious affected area.
For a Panorama Village storm claim, that can mean evaluating roofing, exterior components, interior water damage, fencing, detached structures, and other areas connected to the event.
3. Claim Documentation
We organize photographs, measurements, damage descriptions, repair information, estimates, inventories, and supporting claim documents.
The goal is to develop a clear, defensible description of the covered loss.
4. Carrier Communication and Negotiation
TX Public Adjusting communicates with the insurance company regarding the documented claim.
When the carrier estimate differs from our findings, we identify specific scope or pricing differences and present supporting documentation.
5. Claim Resolution
We continue working through the claim process toward an appropriate settlement based on the policy and documented covered damage.
Every claim is different. No public adjuster can legitimately promise a particular settlement amount, but strong documentation can help ensure the carrier has the information needed to evaluate the complete loss.
A Local Approach to Panorama Village Property Claims
Panorama Village is not simply another Houston-area city name.
The community developed around Panorama Golf Club and remains closely tied to its wooded, golf-course setting. It sits immediately north of Conroe, close to Interstate 45 and within easy reach of Lake Conroe.
Residential areas associated with the Panorama Village market include Thunderbird, Indian Creek, Cherry Hills, Green Briar, Parkside of Panorama, Hallmark of Panorama, Quail Creek, Westchester, Apple Valley, and Forest Creek North.
That local housing pattern influences the types of losses we pay attention to. Golf-course and wooded properties may have tree exposure during storms. Older roofs can make hail and wind evaluations more complicated. Properties near low areas or drainage paths may see different water issues than homes on higher ground.
A useful claim inspection has to evaluate the actual building and actual event—not apply a generic checklist.
If your Panorama Village claim has already been inspected and the carrier’s payment seems too low, TX Public Adjusting can review the scope before you accept the claim as complete. Request a Free Claim Review.
Why Choose TX Public Adjusting
Licensed Texas Public Adjuster
TX Public Adjusting operates through Rise Public Adjusting LLC, Texas License #3356839.
Licensing matters because public adjusting involves representing a policyholder during a financial insurance claim. Property owners should know who is handling their claim and verify that the person or company is properly authorized.
We Represent Policyholders
We do not work for the insurance carrier.
Our role is to represent the homeowner, business owner, association, or commercial property owner making the claim.
Texas Property Claim Experience
Our work is focused on Texas property losses, including hail, wind, water, roof, fire, storm, hurricane-related, and commercial property claims.
Our team has reviewed thousands of claims and understands how documentation, estimating, policy provisions, and repair scope interact during the adjustment process.
Residential and Commercial Expertise
A residential roof claim and a large commercial property loss do not require the same documentation.
We work with both residential and commercial claims and adjust our process based on the property, policy, loss, and complexity of the damage.
Independent Claim Review
Property owners should not have to guess whether important damage is missing from an insurance estimate.
We review the claim independently and explain the differences we identify.
Areas We Serve Near Panorama Village
TX Public Adjusting serves policyholders throughout Montgomery County and surrounding Texas communities.
Close to Panorama Village, TX Public Adjusting also assists property owners throughout the surrounding Montgomery County area. Property owners immediately south of Panorama Village can learn more about working with a Public Adjuster in Conroe. We also serve communities farther south along the I-45 corridor through our Public Adjuster Oak Ridge North and Public Adjuster Shenandoah service pages.
Panorama Village’s position along I-45 also places it close to Willis and the broader north Montgomery County corridor. The city itself is only about five miles north of Conroe.
Frequently Asked Questions About Public Adjusters in Panorama Village
What does a public adjuster in Panorama Village do?
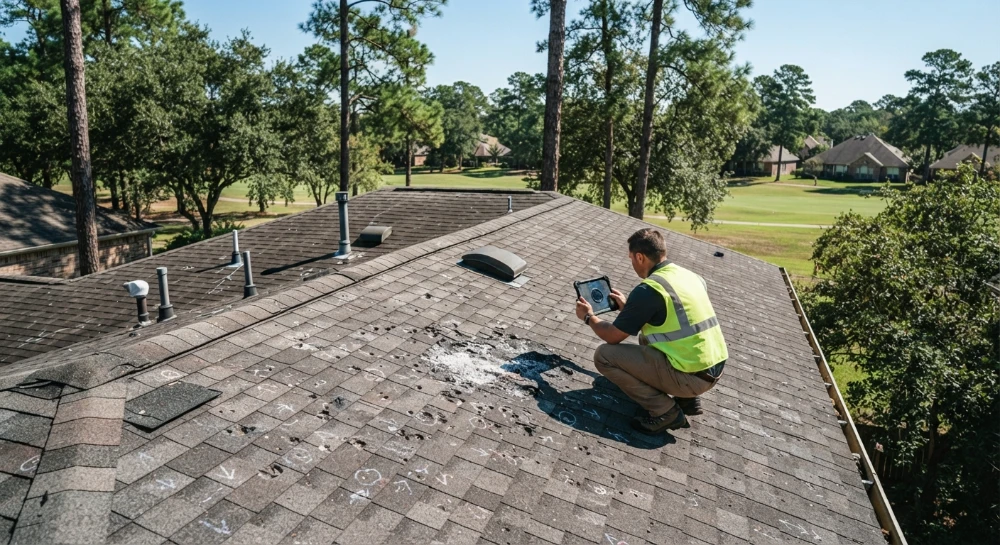
A public adjuster represents the property owner during an insurance claim. That can include inspecting the loss, documenting damage, reviewing the policy and carrier estimate, preparing a repair scope, communicating with the insurance company, and negotiating documented differences.
TX Public Adjusting works for the policyholder, not the insurance carrier.
When should I hire a Panorama Village public adjuster?
Property owners often contact us when a claim is large or complicated, when the insurance company’s estimate appears incomplete, after receiving a low payment, following a denial, or when additional damage is discovered after the initial inspection. If your claim is already underway, our guide explaining when it is too late to hire a public adjuster covers when a public adjuster may still be able to become involved and when deadlines or final claim documents may limit your options.
You do not necessarily have to wait until a disagreement develops. Early documentation can be valuable on substantial hail, water, roof, storm, commercial, and fire claims.
Can you help if my Panorama Village roof claim was underpaid?
Yes. We can review the carrier’s roof estimate and compare it with the observed damage and repair requirements.
We look for omitted roofing components, exterior damage, quantity differences, repairability issues, interior damage associated with the storm, and other documented discrepancies.
Does homeowners insurance cover hail damage in Panorama Village?
Many Texas property policies provide some form of wind or hail coverage, but deductibles, exclusions, cosmetic-damage provisions, roof-payment schedules, endorsements, and valuation terms vary substantially.
The correct answer depends on your specific policy. We review the actual coverage documents rather than assuming every Panorama Village homeowner has identical protection.
Can a public adjuster help with water damage?
Yes, when the loss involves a potentially covered cause.
A pipe break, plumbing failure, appliance leak, or rain entering through covered storm damage can involve very different policy questions from rising surface water. We examine the reported cause and policy terms before determining how the claim should be documented.
What if the insurance company already inspected my property?
You can still request an independent claim review.
Many clients contact TX Public Adjusting only after they receive the insurance company’s estimate and realize the proposed scope does not match the damage or contractor findings. We can compare the existing claim documents with the condition of the property.
Can you reopen or supplement an insurance claim?
Some claims may be eligible for supplemental consideration when covered damage or repair items were omitted, although policy deadlines and individual circumstances matter.
If you believe a Panorama Village claim was closed too quickly or additional damage has been discovered, we can review the documents and explain the options that may still be available.
How much does a public adjuster cost in Panorama Village?
Public adjusting fees are generally governed by the agreement between the public adjuster and policyholder and applicable Texas requirements.
TX Public Adjusting offers a Free Claim Review and no upfront fees for our public adjusting services. We explain the fee arrangement before you decide whether to move forward.
Can you handle commercial claims in Panorama Village?
Yes. TX Public Adjusting handles residential and commercial property claims.
Commercial losses may involve roofs, interiors, equipment, inventory, multiple tenants or structures, water mitigation, fire damage, storm damage, and other policy considerations that require more extensive documentation than a typical residential claim.
Why hire TX Public Adjusting instead of relying only on the insurance company’s adjuster?
The insurance company’s adjuster evaluates the claim for the carrier. TX Public Adjusting represents the policyholder.
Having your own licensed public adjuster gives you someone focused on documenting your loss, reviewing the carrier’s estimate, identifying missed damage, preparing supporting information, and advocating for your position throughout the claim.
Get a Free Panorama Village Insurance Claim Review
A property insurance claim can affect your roof, home, business, savings, and ability to complete repairs. You should understand what the carrier included—and what may have been left out—before assuming the first estimate tells the whole story.
TX Public Adjusting helps Panorama Village, TX property owners with:
- Hail damage claims
- Wind and storm claims
- Roof damage claims
- Water damage claims
- Fire and smoke claims
- Underpaid insurance claims
- Denied property claims
- Commercial property claims
- Supplemental claim documentation
We represent policyholders, not insurance companies.
TX Public Adjusting
Rise Public Adjusting LLC
Texas License #3356839
Request your Free Claim Review today. No upfront fees. Contact TX Public Adjusting to discuss your Panorama Village property damage claim.